
China Property Investment: Markets, Strategies and Risks
China property investment requires a more detailed approach than simply assessing whether Chinese property prices are rising or falling. The country contains a vast collection of metropolitan, regional and specialist property markets, each influenced by different combinations of population, employment, infrastructure, development, housing supply and economic activity.
For an international investor, the first question should therefore be where and what to invest in. Beijing, Shanghai, Shenzhen, Guangzhou and other major cities have very different property characteristics from smaller cities, industrial centres, tourism destinations and newly developing districts. Within each city, individual neighbourhoods can also behave very differently.
China's property sector has also undergone a substantial structural adjustment. Current investment research therefore needs to distinguish between established market fundamentals, short-term market conditions and the longer-term transformation of China's property sector.
China Property Investment Is Not One Market
China should not be treated as a single property investment market. The economic structure of a major international city can be very different from that of a provincial capital or smaller regional centre.
Employment, household formation, population movement, infrastructure and development supply all affect local property demand. A city with a strong and diversified economy may have different investment characteristics from a location dependent on one industry or a shrinking population.
The same principle applies within cities. Established central districts, suburban developments, redevelopment zones and new urban areas can have different levels of demand, supply and liquidity.
Investors should therefore move from country to city, from city to district and finally from district to individual property rather than relying on a national property forecast.

|
PHILIPPINES |
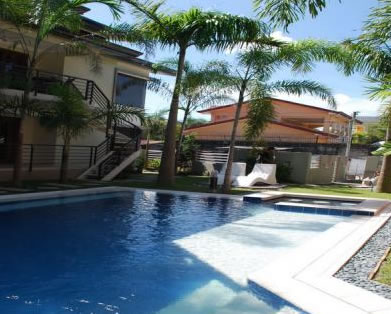
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


China's Major Investment Markets
China's largest metropolitan areas remain important to international property research because of their economic scale, infrastructure and depth of property markets.
Beijing has a particularly strong concentration of government, professional services, education, research and corporate activity. Shanghai is a major financial, commercial and international business centre. Shenzhen has a strong technology and innovation economy and is closely connected with the wider Greater Bay Area. Guangzhou combines manufacturing, commerce, logistics and services within one of China's largest urban economies.
These cities should not, however, be treated as interchangeable investments. Property prices, rental demand, development patterns, regulations and the characteristics of individual districts differ substantially.
The IPD China property markets guide provides the broader market framework before investment research is narrowed to a particular location.
Secondary Cities Can Require More Research
China's secondary cities can offer a very different investment proposition from the major metropolitan markets. Some have substantial manufacturing, technology, university, logistics or service economies, while others are more dependent on particular industries or government-related activity.
Lower property prices do not automatically make a smaller city more attractive. An investor needs to establish the reason people are moving to the city, where employment is being created and whether there is sufficient demand to support both rental and resale markets.
Population trends are particularly important. A market experiencing population decline may still contain attractive individual properties, but the long-term demand assumptions need to be different from those used in a growing employment centre.
Residential Property Investment
Residential property is likely to be the most familiar form of Chinese real estate investment for an overseas buyer, but residential property itself contains several different markets.
New-build apartments, existing apartments, luxury housing and properties in emerging districts can have different buyer profiles and levels of liquidity. The distinction between a property intended for owner occupation and one intended primarily for investment is also important.
An investment analysis should consider the likely tenant or resale buyer before the property is purchased. A property may look attractive because of its size, design or price while having limited appeal to the people who actually rent or purchase in that location.
Rental Investment Requires Local Demand
Rental property should be assessed through the local tenant market rather than through an advertised rental yield alone.
Investors should identify who the likely tenants are and what brings them to the location. Employment centres, universities, hospitals, business districts, transport connections and established residential communities can all support rental demand.
The supply side is equally important. A large number of new apartments entering the same rental market can put pressure on rents even where the wider city has a substantial population.
Operating expenses, management fees, maintenance, taxes, vacancies, furnishing and letting costs also need to be incorporated into the investment calculation. The advertised rent is not the same as the investor's net income.
For regional comparison, see the IPD guide to East Asia rental markets.
Commercial Property Investment
Commercial property creates a different investment analysis. Offices depend on business activity and employment, retail property depends on consumers and accessibility, while industrial and logistics property can be closely connected to manufacturing, trade and transport infrastructure.
Investors should therefore identify the economic activity supporting the property before considering its potential income.
An office building in an established employment centre has a different demand profile from an office development in a newly planned district. Similarly, a logistics property close to major transport infrastructure may have different fundamentals from a commercial building that relies on future infrastructure proposals.
Industrial and Logistics Investment
China's manufacturing, export and domestic distribution networks create substantial industrial and logistics property markets. These markets can be particularly location-sensitive.
Ports, airports, highways, rail connections, manufacturing clusters and major population centres can all influence the suitability of a logistics location. The property itself needs to be considered alongside access, permitted use, tenant demand and competing supply.
Industrial investment also requires careful investigation of land-use rights and planning. The investor should establish exactly what can legally be done with the property rather than relying on the way an asset is described in marketing material.
Development Property Is a Different Investment
Investing in a completed property is fundamentally different from investing in land or a development project.
A development investor is exposed to planning, financing, construction, contractor, sales, infrastructure and market risks. The value of the investment depends partly on what can be built and whether the completed project can be sold or occupied at economically viable prices.
China's recent property adjustment has made developer financial strength and project completion particularly important areas of due diligence. The investor should investigate the developer, project structure, construction status, funding arrangements, contractual protections and delivery arrangements before committing capital.
IPD's China property development research can be used alongside individual development due diligence.
The Importance of Property Supply
Supply is one of the most important variables in Chinese property investment. A location can have strong economic activity and still produce disappointing investment results if large quantities of competing property are being built.
Investors should examine completed properties, developments under construction and significant future projects. The analysis should distinguish between total construction and the particular type of property competing with the investment.
For example, a residential investment should be compared with competing residential supply in the same market rather than with the total amount of construction across an entire city.
China's Property Adjustment Changes the Investment Analysis
China's property sector has moved through a major adjustment following the long period of rapid development that preceded the current market environment. International institutions including the IMF have identified property-sector weakness, developer financial stress, inventories and changing housing demand as important factors in China's economic outlook.
This does not mean that every Chinese property market has the same investment characteristics. It means that investors need to examine the underlying economics more carefully and avoid assuming that historical patterns of property development will simply continue.
The adjustment also increases the importance of distinguishing between different developers, locations and property types. Market conditions can create opportunities in some segments while increasing risk in others.
Developer Strength Matters
The financial position and track record of a developer can be particularly important when purchasing new property before completion.
Investors should investigate the developer's previous projects, delivery record, ownership structure, financing arrangements and current development pipeline. The condition of the particular project should also be established independently of sales material.
A completed apartment and an apartment being purchased during construction are not equivalent investments. The latter contains an additional layer of development and delivery risk.
Price Does Not Equal Investment Value
A lower purchase price can make a property appear attractive, but price needs to be considered against income, demand, supply and liquidity.
An inexpensive property in a declining or oversupplied market may have weaker investment characteristics than a more expensive property in a location with stronger employment and deeper demand.
Comparable transactions should therefore be used wherever possible. The comparison should consider location, building age, property size, quality, tenure, amenities and other characteristics that affect the actual market value.
Capital Growth and Rental Income Are Different Strategies
Property investors sometimes combine capital appreciation and rental income into a single expected return. They are driven by different factors and should be assessed separately.
Rental income depends on tenants, rents, vacancies and operating costs. Capital appreciation depends on changes in demand, supply, land values, economic activity and the market's willingness to pay for the property in the future.
A property can therefore have reasonable rental demand without delivering strong capital appreciation, or it can have substantial development potential while producing weak current rental income.
Liquidity Is an Important Investment Consideration
Liquidity is often overlooked when property is compared with other forms of investment. A property cannot necessarily be sold quickly at the price an owner expects.
International investors should investigate the depth of the local resale market, the number of comparable properties, the typical buyer profile and the conditions affecting transactions.
Luxury property and unusual commercial assets can have particularly narrow pools of potential buyers. This can matter considerably if the investor later needs to exit the investment.
Infrastructure Can Create Investment Opportunities
Infrastructure investment can change the economic geography of a city. Rail, metro systems, roads, airports and other transport connections can improve accessibility and alter where people live and businesses operate.
For investors, the important distinction is between infrastructure that exists and infrastructure that has merely been proposed.
A future transport connection can form part of an investment thesis, but it should not be treated as an existing benefit. The project's status, expected completion and surrounding development should all be independently investigated.
Foreign Buyers Need a Separate Due Diligence Process
International investors cannot assume that the rules applying to a domestic Chinese purchaser will automatically apply to them.
Foreign ownership, eligibility, purchase restrictions, documentation, foreign-exchange arrangements and the intended use of a property can all affect a transaction. Requirements may also vary according to the city, property type and circumstances of the buyer.
This is particularly important when comparing residential property with commercial or development opportunities. The legal and financial structure of an investment may be substantially different from that of an ordinary residential purchase.
IPD's China foreign ownership research should be considered alongside professional legal and financial advice before a transaction is undertaken.
Currency and Financing Need to Be Included
An overseas investor should calculate the investment in both the property's local currency and the investor's own currency.
Exchange-rate movements can affect the effective purchase price, rental income and eventual sale proceeds. Financing conditions can also alter the investment outcome, particularly where the investor is borrowing in one currency while the property generates income in another.
Transfer costs, taxes, banking charges and other transaction expenses should be included before comparing the expected return with alternative investments.
IPD's currency and international money transfers guide provides the broader framework for this part of the research.
China Property Investment Requires Market-Level Research
The most useful China property investment analysis begins with the market rather than the property advertisement.
Identify the city and district, understand the economic activity supporting demand, examine population and employment trends, map existing and future property supply, investigate rents and comparable sales, and then assess the individual property.
For development property, add developer and construction risk. For rental property, add tenant demand and operating costs. For commercial property, investigate the business activity supporting the asset. For every investment, establish the legal position and the rules applying to the international buyer.
China Property Investment Is a Research Exercise
China remains one of the world's largest and most complex property markets, but its scale makes broad investment assumptions particularly unreliable. The country contains mature metropolitan markets, secondary cities, industrial centres, tourism markets, redevelopment areas and newly planned districts, each with different investment characteristics.
The recent adjustment in the property sector reinforces the need to distinguish between locations, property types and individual projects. Current market conditions, prices, regulations, financing and developer circumstances should be verified at the time of investment rather than carried forward from historical information.
For international investors, the most durable approach is to research the economic market first, identify the property segment that matches the investment objective, investigate supply and demand, and then undertake detailed due diligence on the individual property. China property investment is therefore best approached as a research process rather than a simple search for a rising market or a low purchase price.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
|
