
Currency and Money Transfers for Property Buyers in Asia Pacific
Buying property in Asia Pacific often means moving money between countries, currencies and banking systems. For an overseas buyer, the property price is only part of the financial equation. The currency used for the purchase, the currency in which income is earned, the timing of exchange and the method used to transfer funds can all affect the final cost of acquiring and owning property.
Asia Pacific is particularly diverse in this respect. A buyer may be purchasing in a market where the local currency is widely traded, in a smaller island economy with more limited banking infrastructure, or in a market where foreign buyers commonly fund purchases from accounts held abroad. Understanding how money moves through the transaction is therefore an important part of buying property in Asia Pacific.
The Property Price Is Not the Same as the Currency Cost
A property may be advertised at a straightforward price in the local currency, but an overseas buyer ultimately needs to consider how much that price represents in the currency used to fund the purchase. If the buyer earns income or holds savings in another currency, the exchange rate becomes part of the effective property price.
This distinction becomes particularly important when comparing markets. A property priced at the equivalent of a certain amount in US dollars, euros, pounds or Australian dollars can become more or less expensive to the buyer without the local seller changing the asking price. Currency movements can therefore alter the relative affordability of markets even when local property prices remain broadly stable.
For international buyers researching several countries, it is useful to separate the underlying property price from the currency conversion. The two are related, but they represent different sources of financial risk.
Asia Pacific Is a Multi-Currency Property Region
There is no single currency environment across Asia Pacific. Major economies such as Japan, Australia, China and South Korea operate very different monetary and banking systems from smaller Southeast Asian or Pacific Island markets. The same is true of the way property transactions are structured and the currencies accepted by sellers, developers, banks and professional advisers.
Some markets have highly liquid and internationally traded currencies. Others may have currencies that are less familiar to overseas buyers, or property transactions in which a foreign currency such as the US dollar has an important practical role. In some markets, the currency in which a property is marketed may also differ from the currency ultimately required for settlement.
This makes international buyer research more important than simply converting an advertised price into the buyer's home currency.

|
PHILIPPINES |
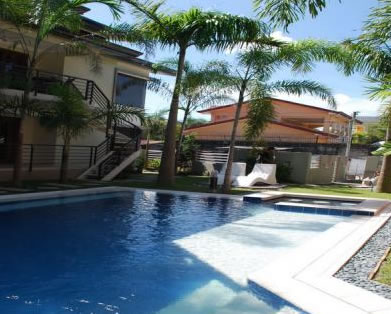
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Exchange Rates Can Change the Cost Before Completion
Currency risk is often underestimated because the buyer agrees to a property price at one point in time while the funds may not be transferred until weeks or months later. During that period, exchange rates can move in either direction.
This is particularly relevant where a transaction involves a deposit followed by one or more later payments. An overseas buyer may initially convert enough money for the deposit but still have a substantial balance to fund at completion. If the exchange rate changes between those stages, the amount required in the buyer's home currency can change even though the property price has not.
Off-plan purchases can introduce a much longer period of currency exposure. A development may require staged payments over an extended construction period, meaning the buyer may be exposed to several different exchange rates rather than one conversion at the beginning of the transaction.
Compare the Full Cost of Currency Conversion
The exchange rate shown by a bank or money-transfer provider is not necessarily the only cost involved. Buyers should look at the complete transaction cost, including the exchange-rate margin, transfer fee, intermediary banking charges and any receiving-bank fees that may apply.
A transfer provider offering a lower advertised fee may not necessarily produce the lowest overall cost if its exchange-rate margin is wider. Conversely, a service with a visible transfer fee may provide a more competitive conversion rate. The meaningful comparison is the amount that ultimately arrives in the required account.
For a substantial property purchase, even a relatively small difference in the effective exchange rate can represent a significant amount of money. Buyers should therefore compare providers using the actual amount required for the transaction rather than relying on headline fees alone.
Timing a Property Currency Transfer
There is no universally correct time to convert a large sum of money. Trying to predict short-term currency movements can turn a property transaction into a speculative exercise, particularly when the buyer's primary objective is to complete the purchase rather than trade currencies.
A more practical approach is to understand when money will be required and what degree of currency exposure the buyer is prepared to accept. The transaction timetable should be established early, including the dates for the deposit, contract payments, taxes, professional fees and final settlement.
Where a transaction involves several future payments, the buyer can discuss the available currency-management options with a regulated financial institution or currency specialist. The appropriate arrangement will depend on the buyer's circumstances, the currencies involved and the rules applying in the countries concerned.
Using a Bank Account in the Property Market
Opening a local bank account can sometimes make property ownership and ongoing expenses easier, particularly where the buyer expects to receive rental income or pay regular local bills. However, opening an account is not necessarily a simple step for a non-resident.
Banks may require identification, proof of address, information about the source of funds and evidence explaining the purpose of the account. Requirements vary considerably between jurisdictions and between resident and non-resident customers.
An overseas buyer should not assume that establishing a local account is essential to purchase property. The transaction may instead be completed through a lawyer, notary, escrow arrangement or other authorised settlement structure, depending on local practice. The important point is to establish the required payment route before money needs to be transferred.
This is closely connected with lawyers and notaries in Asia Pacific property transactions.
Make Sure the Recipient and Payment Instructions Are Verified
Large international property payments should never be treated like routine online transfers. Before sending funds, the buyer should independently verify the beneficiary, account details, payment reference and purpose of the transfer with the appropriate professional involved in the transaction.
Particular care is warranted if bank instructions change shortly before a payment is due. A request to send money to a different account should be independently checked rather than accepted simply because the instruction appears to come from a familiar person or company.
Property transactions can involve agents, developers, lawyers, notaries, escrow providers, banks and other parties. The buyer should know exactly who is receiving each payment and why. Maintaining a clear record of contracts, invoices, payment instructions and transfer confirmations also makes it easier to demonstrate the legitimate source and purpose of funds when required.
Source of Funds Can Become Part of the Transaction
International property purchases can involve financial checks in both the buyer's home country and the destination market. Banks and property professionals may need to establish where the money originated and how the buyer accumulated the funds.
This can be particularly relevant for large transfers, transfers involving several jurisdictions, company or trust structures, or transactions involving funds from more than one person. Buyers should be prepared to provide appropriate documentation rather than assuming that possession of the money is sufficient.
Trying to avoid financial checks by splitting payments, using unexplained third-party accounts or changing the source of funds during a transaction can create additional problems. Clear documentation and a transparent payment structure are generally much easier to manage.
Currency Risk Does Not End at Completion
Currency exposure can continue after the property has been purchased. This is particularly important for investors who earn rental income in one currency while mortgage payments, taxes, management expenses or personal expenditure are paid in another.
A property can therefore produce an acceptable rental return in its local market while the investor's return in their home currency is affected by exchange-rate movements. The same consideration applies when a property is eventually sold and the proceeds are converted back into another currency.
This is one reason why international investors should consider the currency profile of an investment alongside its property characteristics. The issue belongs within the wider assessment of Asia Pacific property investment, rather than being treated simply as a payment issue at purchase.
Mortgages Add Another Currency Layer
Where a property is financed, the relationship between the loan currency, property currency and income currency becomes important. A buyer may earn income in one currency, borrow in another and own a property whose value and expenses are denominated in a third.
This can create a mismatch even when the mortgage itself appears affordable. A change in exchange rates may affect the cost of servicing the debt when measured against the buyer's income in their home currency.
Buyers considering borrowing should therefore examine the currency of the mortgage as carefully as the interest rate and loan terms. The financing decision should be considered alongside the wider issues covered in Asia Pacific mortgages and property finance.
New Build and Off-Plan Purchases Require Extra Planning
Currency planning becomes more complicated where a property is purchased before construction is complete. Deposits, construction-stage payments and final balances may fall at different points in the currency cycle.
The buyer should understand whether each payment is fixed in the local currency, another currency or a contractual amount that can change under specified conditions. The contract should also make clear when payments become due and which account should receive them.
This is especially relevant when considering off-plan property in Asia Pacific, where the period between purchase and completion can be considerably longer than for an established property.
Selling Property Creates the Reverse Currency Problem
Currency planning is not only a buyer's issue. An owner selling property in Asia Pacific may need to convert the sale proceeds into another currency after completion. The amount received in the owner's home currency can therefore differ from the apparent local-currency sale price.
There may also be taxes, professional fees, mortgage repayment obligations or other deductions before the proceeds can be transferred overseas. Buyers and sellers should establish the likely payment route before committing to a transaction rather than treating currency conversion as an administrative detail at the end.
The same principle applies to owners living abroad who receive rental income. Regular transfers can create ongoing exchange costs and exposure, making currency management part of the practical process of managing property from abroad.
A Practical Currency Checklist for International Buyers
Before committing to an Asia Pacific property purchase, an overseas buyer should establish the currency in which the purchase price is legally payable, the currency used for the deposit and subsequent instalments, the expected settlement date and the account into which each payment must be made.
The buyer should then identify the likely costs of converting and transferring the funds, determine whether a local bank account is required, understand what documentation may be needed to demonstrate source of funds and establish how future property expenses will be paid.
For larger transactions, it is sensible to obtain professional advice before moving substantial funds. The buyer's bank, property lawyer, notary, tax adviser and any regulated currency provider may each have a different role. Their responsibilities should be understood rather than assuming that one party is managing the entire financial process.
Currency Should Be Part of the Property Decision
For an international buyer, the financial commitment to an Asia Pacific property is determined by more than the advertised price. Exchange rates, transfer costs, payment timing, banking arrangements, financing and future income can all influence the eventual cost and return.
Currency should therefore be considered during property research, not after a property has already been selected. A buyer comparing markets should look at the local property price, transaction costs and financing structure together with the practical realities of moving money into and out of the country.
Understanding these issues does not require trying to forecast currency markets. It requires knowing which currencies are involved, when funds will be needed, what the transfer will actually cost and where the financial risks remain after completion. That provides a more complete foundation for researching property across the diverse markets of Asia Pacific.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

