
China Property Market Data: Understanding Prices, Sales and Market Trends
China's property market is too large and regionally diverse to be understood from a single national house-price figure. For an international buyer researching property from outside China, useful market data needs to show not only what prices are doing, but also where transactions are taking place, how much new property is being built, what is available for sale, how the rental market is developing and how financing and economic conditions are affecting demand.
China's official statistics provide extensive data on real estate development, new-home sales, second-hand transactions, investment, construction and inventory. The challenge is interpreting that information in the context of individual cities and property markets rather than treating national figures as representative of every location.
Why China Property Market Data Matters
Property market data helps establish the structure and direction of a market before an overseas buyer begins examining individual properties. It can show whether a market is dominated by new development or established housing, whether transaction volumes are changing, whether construction is expanding or contracting and whether available stock is building up or being absorbed.
This is particularly important in China because the market includes major metropolitan areas, provincial capitals, rapidly developing cities, smaller urban markets and very different regional economies. The data for Beijing, Shanghai, Shenzhen or Guangzhou cannot automatically be used to describe conditions in another city.
For broader background, see the China property markets guide before moving from national data to individual locations.

|
PHILIPPINES |
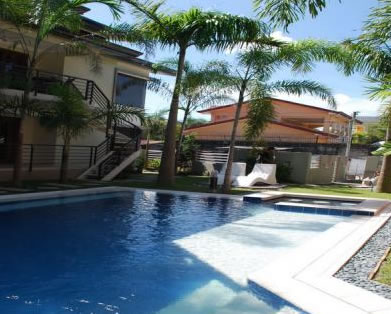
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


The Main Types of China Property Market Data
China property research can be divided into several connected groups of data. Price data measures changes in property values, while transaction data shows whether buyers are actually purchasing. Development data measures new supply, construction and completion. Inventory data indicates the amount of property still available. Rental data provides a different view of demand and investment potential.
Financial and economic data adds another layer. Interest rates, mortgage conditions, household income, employment, population movement, infrastructure investment and business activity can all influence property demand without appearing directly in a house-price index.
A useful research process therefore looks at several indicators together rather than attempting to interpret one number in isolation.
China Property Prices and Price Indices
Property price data is one of the most visible forms of Chinese real estate information, but it needs careful interpretation. Official price indices track changes in residential property prices across selected cities and categories. These indices are useful for identifying direction and comparing periods, but they are not the same as the asking price of a particular apartment or house.
Actual property prices can vary substantially according to neighbourhood, building age, floor level, orientation, transport access, school catchment, development quality, tenure arrangements and property type. A citywide average can therefore conceal significant differences between districts.
International buyers should distinguish between an index showing the movement of prices and a dataset showing actual transaction values. They answer different questions. An index can indicate whether prices are generally rising or falling, while transaction evidence can help establish what buyers are actually paying in a particular location.
For a more focused discussion of valuation and price research, see China property prices.
New-Build Property Sales Data
New-build sales are an important component of China's property market data. Official statistics measure both the floor area of newly built commercial properties sold and the value of those sales. Residential property represents the largest component of this market.
These figures can provide an indication of transaction activity, but they should not be confused with demand for every type of property. New development sales are influenced by developer launches, financing, local planning, incentives, pricing strategy and the availability of completed and unfinished projects.
For example, a decline in new-home sales can occur at the same time as activity in existing housing increases. This is why new-build figures should be considered alongside second-hand transaction data.
Second-Hand Property Market Data
The established or second-hand market is particularly important when researching mature urban locations. Transactions in existing homes can provide evidence of what buyers are doing away from developer sales programmes.
China's national statistics now include data on the online transaction registration area for second-hand housing. This provides an additional measure of market activity and can be compared with new-home sales data.
The distinction matters to international buyers because an established property may offer a very different research proposition from a new development. Existing properties allow comparison with completed buildings, established neighbourhoods, actual rental performance and observable resale transactions.
Construction and New Supply
Development statistics show how much property is being constructed and how the supply pipeline is changing. Important measures include floor space under construction, newly started floor space and completed floor space.
A rising level of new construction can indicate expanding development activity, but it does not automatically mean that demand is strong. Conversely, falling construction may reflect weaker demand, changes in developer finance, land availability or a deliberate reduction in new supply.
China's official data for the first eight months of 2026, for example, showed real estate development investment and new starts continuing to contract compared with the same period a year earlier. This type of information is more useful when examined as part of a longer trend and alongside sales and inventory rather than treated as a standalone market forecast.
For the development side of the market, see China property development.
Property Inventory and Unsold Stock
Inventory is one of the most important indicators when assessing the balance between property supply and demand. Official statistics report the floor area of commercial buildings for sale, including residential, office and commercial categories.
Inventory data needs context. A large amount of property for sale does not necessarily mean that all of it competes directly for the same buyers. Newly completed apartments in one city may have little relevance to established homes in another district, while commercial and residential stock represent entirely different markets.
Changes in inventory can nevertheless reveal whether stock is being absorbed, remaining stable or accumulating. The age of the inventory can also matter because newly completed property and long-standing unsold stock can have very different implications for developers and buyers.
China Rental Market Data
Rental data provides an alternative way to examine property demand. Sale prices can change while rents behave differently, and this distinction is important for investors considering rental property rather than owner occupation.
Useful rental research includes asking rents, achieved rents where available, vacancy, tenant demand, rental supply, lease lengths and differences between furnished and unfurnished accommodation. These figures are often more fragmented than national sales and development statistics, making local research particularly important.
Rental demand should also be linked to employment centres, universities, transport, population movement, business districts and expatriate concentrations rather than simply assuming that a large city automatically produces strong rental returns.
The wider China rental market guide provides further context for researching rental property.
Investment and Developer Finance Data
China's property statistics also contain information about the financial side of development. Data can include developer investment, domestic loans, self-raised funds, deposits and advance receipts and individual mortgage lending.
These indicators are useful because property development depends on financing as well as buyer demand. A market can have substantial existing housing stock while developers reduce new construction because financing conditions have changed or because they are concentrating on completing existing projects.
Developer investment should therefore be read alongside construction starts, completions, sales and inventory. The combination gives a much clearer picture of the development cycle than any individual measure.
Regional and City-Level China Property Data
National data is the starting point rather than the final answer. International buyers need to move from national indicators to provincial, metropolitan and district-level information wherever possible.
China's major urban markets have different economic structures, housing supply, population patterns, employment bases and development histories. Coastal technology and financial centres, major manufacturing cities, provincial capitals and smaller regional markets can therefore behave differently during the same national property cycle.
When comparing locations, examine the same categories of information for each market. Price movement, transaction volume, new supply, inventory, rental demand, infrastructure, employment and population trends provide a more useful comparison than simply asking which city has the highest or lowest average property price.
Population, Employment and Economic Data
Property demand ultimately depends on people and economic activity. Population growth or decline, household formation, migration, employment and business investment can influence housing demand over a much longer period than short-term price movements.
For international buyers, economic data is especially useful when researching a city that is unfamiliar to them. A location with substantial employment, universities, transport infrastructure and established commercial activity may have a different underlying housing market from a location where development has expanded ahead of local demand.
Infrastructure should also be investigated carefully. New rail connections, airports, business districts, industrial projects and urban expansion can change the geography of a property market, but the effect depends on whether the planned infrastructure is actually delivered and whether it generates sustained economic activity.
How to Read China's Property Data Without Being Misled
Property statistics can easily produce misleading conclusions when individual indicators are taken out of context. A fall in prices does not by itself establish that every property has become cheaper. A rise in transactions does not necessarily mean that values are increasing. Increased construction does not automatically mean strong demand, and reduced construction does not prove that a market is deteriorating.
Data also has a time dimension. Monthly figures can be affected by seasonal patterns, policy changes, financing conditions and the timing of development launches. Annual comparisons can be more useful for identifying structural change, while longer series help distinguish a temporary movement from a continuing trend.
International researchers should record the date, geographical coverage, property category and methodology of every dataset they use. This prevents statistics from different markets or different definitions being accidentally compared as though they measured the same thing.
Using Property Data When Buying From Overseas
Market data should narrow the field rather than replace property-level due diligence. Once a location has been selected, the next stage is to compare actual properties, neighbourhoods, buildings, ownership arrangements, transaction costs and potential rental or resale markets.
For an overseas purchaser, the research sequence can begin with national market conditions, move to the city and district, then to the property type and finally to individual properties. This helps prevent an attractive individual listing from becoming the starting point for a much larger investment decision.
Buyers should also investigate the legal framework before relying on market data. Price statistics are relevant only if the buyer can legally acquire the type of property under consideration and understands the applicable ownership, registration and tax requirements. See China foreign property ownership and buying property in China.
Where to Research China Property Market Data
The National Bureau of Statistics of China is a primary source for national real estate development, investment, sales, construction and inventory statistics. Other official bodies publish information relating to monetary policy, finance, land, housing and economic conditions.
International buyers should favour original government or institutional datasets where possible and identify the publication date and geographical scope before using the information. Commercial research reports, property portals and agent information can then be used as supplementary sources for local prices, rents and individual-market observations.
The most useful research combines official national statistics with local market evidence. Neither is sufficient on its own.
Building a China Property Market Research Picture
A practical China property research file can be built around a small group of recurring indicators: property prices, new-home sales, second-hand transactions, construction starts, completions, inventory, developer investment, mortgage activity, rental conditions, population, employment and infrastructure.
The objective is not to produce a single number describing the Chinese property market. It is to understand how different parts of the market interact and then determine how those national conditions relate to the particular city, district and property being considered.
For international buyers, that distinction is fundamental. China is a collection of highly varied property markets operating within a national economy, rather than one uniform housing market. Good market data helps reveal those differences before the research moves from the wider market to individual property.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
|
