
Asia-Pacific Property Insurance – Guide for International Buyers and Owners
Property insurance is an important part of buying and owning real estate across Asia-Pacific, particularly for international buyers who may own a property from another country. Insurance can protect against specified losses, but the availability, cost, coverage and conditions of policies vary considerably between markets and property types.
Asia-Pacific is an exceptionally diverse property region. It includes major metropolitan markets, tropical coastal destinations, earthquake-prone locations, island economies, resort developments and established residential markets in Australia and New Zealand. A beachfront villa, city apartment, rural house and off-plan condominium can therefore have very different insurance requirements.
For an overseas buyer, insurance should be investigated before purchasing rather than treated as an administrative matter after completion. The ability to obtain suitable cover, the risks excluded from a policy, the deductible and the annual cost can all affect the real cost and risk profile of a property.
Why Property Insurance Matters in Asia-Pacific
Property insurance is designed to transfer some financial exposure from the property owner to an insurer, subject to the terms of the policy. Depending on the market and policy, cover may include the building, contents, liability and specified forms of damage caused by events such as fire, storms or other insured hazards.
The precise protection is more important than the description of the policy. Terms such as comprehensive or fully insured do not by themselves establish what is covered. International buyers need to understand the actual insured risks, limits, exclusions, deductibles and conditions.
This is particularly important in Asia-Pacific because physical risks vary substantially between locations. Earthquakes, tropical cyclones, flooding, coastal exposure, landslides, volcanic activity and extreme weather can all be relevant in different markets. A property's precise location and construction can therefore influence both the need for insurance and the availability of cover.
Insurance should form one layer of a wider Asia-Pacific property risk assessment that also considers construction, maintenance, legal ownership, location, infrastructure and property management.
What Property Insurance Can Cover
There is no single standard Asia-Pacific property insurance policy. Coverage depends on the country, insurer, property, intended use and policy terms. A policy may protect the physical building against specified events and may offer separate protection for contents, fixtures, liability or other risks.
Building insurance generally concerns the physical structure and certain permanent components of the property. Contents insurance can address furniture, appliances, personal belongings and other items, depending on the policy. Liability cover may provide protection where the owner becomes legally responsible for injury or damage to another person or their property.
Investment properties can introduce additional considerations. A rental property may need insurance appropriate to tenant occupation, while a holiday property may have a different risk profile because of short-term guests and periods when the property is vacant.
Owners should establish whether the policy reflects the actual use of the property. A policy arranged for a privately occupied residence should not automatically be assumed to provide appropriate protection where the property is regularly rented to third parties.
Natural Hazards and Asia-Pacific Property Insurance
Physical risk is one of the most important reasons for investigating insurance before buying property in Asia-Pacific. Different markets face different combinations of natural hazards, and exposure can vary significantly within the same country.
Earthquake exposure is particularly relevant in parts of East and Southeast Asia and the Pacific. Tropical cyclone and typhoon exposure is important in several coastal and island markets. Flooding can affect coastal areas, river systems and low-lying urban locations, while landslides can be relevant to properties on steep or unstable terrain.
Buyers should establish whether these risks are included in the policy, require additional coverage or are excluded. The distinction can be particularly important where several hazards can affect the same property.
For example, a coastal property may face wind damage from a tropical cyclone as well as flooding or storm surge. Those risks may not necessarily be treated identically by an insurer. Similarly, earthquake damage and resulting water damage may be subject to different policy provisions.
IPD's separate guides to earthquake risk, typhoon and cyclone risk and coastal flooding provide additional context for assessing these hazards.

|
PHILIPPINES |
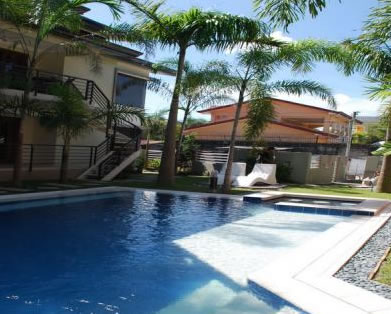
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Insurance and Climate Risk
Climate and physical risk can affect both the need for insurance and the cost or availability of cover. A property in a location exposed to repeated storms, flooding or other hazards may have different insurance conditions from a comparable property in a less exposed location.
International buyers should therefore avoid treating insurance as a fixed percentage of the property's purchase price. Premiums can reflect construction, location, age, occupancy, claims history, hazard exposure and the insurer's assessment of the particular property.
Coastal and island markets deserve particular attention. Properties may be exposed to combinations of tropical storms, flooding, erosion and infrastructure disruption. Insurance costs can become a meaningful component of the long-term economics of ownership.
The same principle applies to properties in areas with significant earthquake or landslide exposure. Insurance availability should be investigated alongside building quality and site conditions rather than being considered in isolation.
A useful starting point for overseas buyers is the wider Asia-Pacific climate and property risk framework.
Insurance Exclusions and Deductibles
The exclusions and deductibles in an insurance policy can be as important as the headline coverage. An exclusion means a particular loss or circumstance is not covered, while a deductible is the amount the owner may have to absorb before insurance contributes to a covered claim.
Natural catastrophe policies can contain substantial deductibles, particularly where a property is exposed to significant hazards. A policy can therefore provide coverage while still leaving the owner responsible for a meaningful proportion of the financial loss.
Buyers should also investigate conditions relating to maintenance, security, occupancy and vacancy. An insurer may impose particular requirements when a property is left unoccupied for extended periods. This matters to international owners who may use a property only for part of the year.
Other exclusions can relate to wear and tear, gradual deterioration, poor maintenance, defects, illegal alterations or other circumstances that do not constitute an insured event. Owners should understand the difference between sudden insured damage and ordinary responsibility for maintaining a property.
The actual policy wording should therefore be reviewed rather than relying on a summary provided by a seller, agent or property manager.
Insurance and Construction Quality
Insurance does not replace the need for good construction and proper property inspection. A building can be insured and still represent a poor purchase if it has structural defects, inadequate maintenance or construction problems that are outside the scope of the policy.
Construction can also influence the availability and cost of insurance. Buyers should investigate the property's age, materials, structural condition, roof, electrical systems, plumbing, drainage and any significant alterations.
For older buildings, records of previous damage and repairs can be useful. A history of insurance claims or major repairs does not automatically make a property unsuitable, but it can indicate areas that require further investigation.
For new developments, buyers should investigate the developer, construction specifications, approvals and completion documentation. Insurance associated with the finished property should also be distinguished from protections relating to construction defects or developer obligations.
This is especially important for overseas purchasers of off-plan property, where the completed building cannot yet be inspected in its final condition.
Apartment, Condominium and Resort Insurance
Apartment and condominium ownership can make insurance more complicated because responsibility is divided between the individual owner and the building or owners' association. The exact division depends on local law, the ownership structure and the building's management arrangements.
A building-wide policy may cover common structures and shared facilities, while the individual owner may need separate protection for the interior of the unit, contents, improvements and personal liability. Buyers should establish precisely where one policy ends and another begins.
Common facilities can include roofs, external walls, lifts, parking areas, pools, generators, drainage systems and other infrastructure. Damage to these areas may result in costs being shared among owners even where an individual apartment itself has suffered limited damage.
Resort developments can create additional considerations because roads, landscaping, pools, recreational facilities and other shared infrastructure may be essential to the operation and value of the property.
Before buying, international purchasers should request information about building insurance, recent claims, deductibles, reserve funds, maintenance arrangements and responsibility for major repairs where these records are available.
Insurance for Overseas and Second-Home Owners
Owning property from another country creates practical insurance considerations that may be less significant for a full-time local resident. An overseas owner may not be able to inspect the property regularly, respond immediately to damage or coordinate contractors following a major event.
A reliable local property manager can therefore be an important part of the overall risk-management arrangement. The owner should establish whether the manager conducts regular inspections, can respond to emergencies and is authorised to arrange urgent repairs when necessary.
Vacant properties may also be subject to different insurance conditions. Buyers should tell the insurer how frequently the property will be occupied and whether it will be rented, used as a second home or left empty for extended periods.
Where the property is intended to be rented to tourists or other short-term occupants, the owner should ensure that the insurance arrangement reflects that use. A policy designed for owner occupation may not provide appropriate protection for commercial or short-term rental activity.
Insurance should therefore be arranged around the actual ownership model rather than simply the physical property.
Insurance for Rental and Investment Property
For investors, insurance forms part of the operating cost of the property and should be included in the financial assessment before purchase. Premiums, deductibles, maintenance and potential periods of lost rental income can all affect the real return from an investment.
Rental property may require cover for the building, contents, liability and other risks associated with tenants or guests. The appropriate arrangement will depend on local regulations, the property type and how the property is rented.
Holiday and short-term rental properties can have a different exposure from long-term residential rentals because of higher turnover, guest access and potentially greater use of furnishings and facilities.
Investors should also consider what happens after a major insured event. Even where a claim is accepted, repairs can take time, tenants may leave and rental income may be interrupted. Insurance may cover some associated losses, but the policy terms need to be checked carefully.
Insurance should therefore be included alongside taxes, management, maintenance, service charges and other expenses when assessing Asia-Pacific rental property investment.
Insurance Availability Can Reveal Property Risk
The ability or difficulty of obtaining suitable insurance can itself provide useful information during due diligence. If appropriate cover is readily available from established insurers on reasonable terms, the property may present a relatively straightforward insurance proposition. If cover is unavailable, heavily restricted or subject to unusually high deductibles, the underlying reasons deserve investigation.
This does not mean that an expensive or difficult-to-insure property should automatically be rejected. Some attractive coastal, island or high-risk locations naturally carry higher insurance costs because of their physical environment.
The important question is whether the buyer understands the reason for the insurance conditions and has included the resulting financial exposure in the purchase decision.
Insurance quotations can therefore form part of the due diligence process. They should not replace technical, legal or environmental research, but they can add another useful layer of information about the property's risk profile.
Insurance and Property Value
Insurance can influence the long-term cost and attractiveness of a property. A low purchase price does not necessarily mean a low-cost asset if insurance is expensive, important risks are difficult to cover or the property requires substantial ongoing maintenance.
Conversely, a property with sound construction, good infrastructure, established insurance availability and effective maintenance arrangements may provide a more predictable ownership profile even if the initial purchase price is higher.
Insurance can also become relevant when selling. A future buyer may want to know whether the property has suitable cover, whether significant claims have occurred and whether major repairs were completed following previous events.
For international investors, the cost and availability of insurance should therefore be considered alongside rental demand, property prices, taxes, financing and the eventual resale market rather than treated as a minor annual expense.
What International Buyers Should Check Before Buying
Insurance research should begin before an overseas buyer becomes fully committed to a property. Obtaining an indicative quotation can identify potential issues while there is still time to investigate the property or reconsider the purchase.
Buyers should seek clear answers to several practical questions before completion:
• Is insurance available for the exact property and intended use?
• Which risks are covered and which are specifically excluded?
• Are earthquake, cyclone, flood, storm surge, landslide or other local hazards covered?
• What deductibles apply to major risks?
• Are there separate limits for particular types of damage?
• Does the policy cover the building, contents and liability as required?
• Does the policy permit long periods of vacancy or overseas ownership?
• Is the property being used in a way that the insurer has approved?
• For apartments, what does the building's insurance cover and what remains the individual owner's responsibility?
• Has the property experienced previous damage or insurance claims?
• Are there maintenance or security conditions that the owner must meet?
• Is the insurer or intermediary properly authorised in the relevant market?
Buyers should obtain the actual policy terms and conditions rather than relying solely on a verbal explanation. Where the insurance system is unfamiliar or the property has significant physical exposure, local professional advice can be appropriate.
Insurance as Part of Asia-Pacific Property Due Diligence
Property insurance is most useful when it forms part of a wider risk-management strategy. Appropriate insurance can reduce financial exposure, but it cannot eliminate physical risk or compensate for poor construction, inadequate maintenance or an unsuitable location.
For international buyers, the strongest approach is to assess the property as a complete ownership proposition. Location, building quality, natural hazards, insurance, maintenance, management, taxes, financing, rental income and eventual resale all contribute to the real economics of ownership.
Insurance should therefore be investigated at the same time as other property due diligence, not after the purchase decision has effectively been made. The availability and terms of cover may reveal risks that are not obvious from an estate agent's description or a property viewing.
IPD provides a wider framework for researching Asia-Pacific property markets, including buying, investment, property types, rentals, taxation and physical risk. For overseas buyers, combining these areas of research can provide a more realistic understanding of the costs, opportunities and risks associated with owning property across the region.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

