
Coastal Flooding and Property in Asia-Pacific – Guide for International Buyers
Coastal property is an important part of the Asia-Pacific real estate market. International buyers consider beachfront homes, waterfront apartments, island residences, resort developments and coastal land for personal use, retirement, rental income and long-term investment. Yet proximity to the sea can introduce environmental risks that deserve careful attention before a purchase is made.
Coastal flooding can affect property through storm surge, unusually high sea levels, waves, intense rainfall and inadequate drainage. These hazards do not affect every coastline equally, and the exposure of one property can differ substantially from another nearby. Elevation, shoreline characteristics, construction, surrounding development and local infrastructure all influence the potential consequences.
For buyers researching from overseas, the challenge is to look beyond photographs, views and advertised proximity to the beach. The relevant questions concern the specific site, the building, the reliability of local services, the availability of insurance and the potential long-term cost of ownership.
Understanding Coastal Flood Risk in Asia-Pacific
Asia-Pacific encompasses a vast range of coastal environments, from major metropolitan waterfronts in Australia, Japan, China and Singapore to tropical shorelines in Thailand, Indonesia, Vietnam and the Philippines, as well as low-lying islands across the Pacific. The physical conditions and infrastructure of these locations vary considerably.
Coastal flood risk describes the possibility that water from the sea or connected coastal systems will affect land, buildings or infrastructure. Flooding may occur during a severe storm, through wave action or storm surge, or when high coastal water levels coincide with heavy rainfall and restricted drainage.
Longer-term changes in sea level can also influence coastal exposure by raising the baseline from which tides and storm-related water levels occur. However, the actual risk at an individual property depends on local geography, natural features, protective infrastructure and the characteristics of the building.
International buyers should distinguish between a destination's general exposure and the specific risk affecting the property they are considering. A country-level climate description cannot establish whether a particular house, apartment or development site is vulnerable.
Storm Surge and Coastal Inundation
Storm surge occurs when weather conditions associated with a storm push seawater towards the coast, temporarily raising water levels above normal conditions. Strong winds, atmospheric pressure, coastal shape and the timing of tides can influence the extent of the surge.
During severe weather, storm surge can combine with waves and heavy rainfall to create more damaging conditions than any single factor would produce independently. Water may reach roads, ground-floor accommodation, parking facilities, utility systems and other areas of a coastal development.
Properties directly facing the sea may have obvious exposure, but nearby buildings can also be affected depending on elevation, shoreline configuration and the movement of water through the surrounding area. Coastal flooding should therefore not be assessed solely by measuring the distance between a property and the beach.
Buyers should investigate local storm history and available hazard information, particularly where a property is located on a low-lying shoreline. They should also establish whether previous repairs or protective works have been undertaken and whether the building's design is appropriate for the conditions experienced in the location.

|
PHILIPPINES |
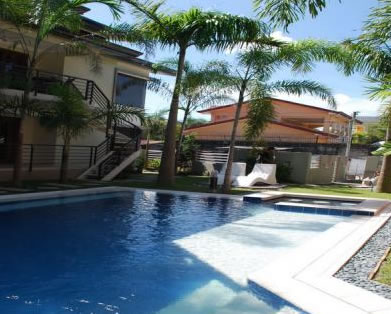
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Sea-Level Rise and Long-Term Coastal Exposure
Changes in sea level are an important consideration for property intended to be held over many years. A gradual increase in baseline sea levels can influence the frequency or severity of coastal inundation, particularly when combined with high tides, storm surge and wave action.
The consequences vary according to the local coastline. Low-lying land, small islands, coastal wetlands and some densely developed waterfront areas may face different challenges from elevated or naturally protected coastlines. Local land movement, coastal processes and the presence of protective infrastructure can also affect the outcome.
For an international buyer, the relevant issue is not whether all coastal property will experience the same future conditions. It is whether credible local information identifies potential exposure at the specific site and whether that exposure could affect the property's intended use, maintenance costs or future resale.
Buyers considering a long-term investment should investigate current coastal planning policies, available elevation information and any relevant assessments of shoreline change. Where a property is particularly exposed, specialist advice may be appropriate before a financial commitment is made.
Heavy Rainfall and Inadequate Drainage
Coastal flooding does not always begin at the shoreline. Heavy rainfall can overwhelm drains, fill low-lying streets and cause water to collect around buildings. In coastal areas, high sea levels can also restrict the discharge of rainwater through drainage systems, increasing the potential for localised flooding.
Urban development can change how water moves across a site. Extensive paved surfaces, altered natural drainage routes, construction on low-lying land and inadequate maintenance of drainage infrastructure can all influence flood exposure.
For property buyers, this means that a waterfront development with sea defences may still face rainfall-related flooding. Underground parking, basements, ground-floor apartments, electrical installations and access roads can be particularly important areas to investigate.
Buyers should establish how the site manages surface water, whether the surrounding area has a history of flooding and whether essential access routes remain usable during severe weather. The condition and capacity of local drainage infrastructure can be as important as the property's own construction.
Coastal Erosion and Changes to the Shoreline
Coastal erosion is related to, but distinct from, flooding. It involves the removal or movement of material along a shoreline and can gradually alter beaches, cliffs, dunes and coastal land. Storms and wave action can accelerate these changes in some locations.
Erosion can affect the land supporting a property, access routes, retaining structures and nearby infrastructure. It may also influence beach width, coastal amenities and the character of a location that originally attracted buyers.
Buyers should investigate whether the shoreline has changed over time and whether local authorities have identified erosion concerns or restrictions on development. A property marketed as beachfront should not automatically be assumed to have a stable shoreline or unrestricted rights to modify the coast.
Where protective structures such as seawalls are present, the buyer should establish who owns and maintains them, what they are designed to protect and whether future maintenance or repair costs could fall on individual owners or a wider development.
Which Types of Property Need Particular Attention?
Coastal flood exposure is relevant to several property categories, but the potential consequences differ according to the building, location and intended use.
Beachfront houses and villas may have direct exposure to waves, storm surge and shoreline change. Ground-floor apartments and buildings with underground parking may be sensitive to water entering lower levels. Resort developments can depend on roads, utilities, beaches and shared facilities that may be affected even when individual buildings remain undamaged.
Coastal development land requires a different assessment. Buyers should investigate elevation, access, drainage, planning restrictions, construction requirements and the feasibility of providing suitable infrastructure. Attractive sea views or a large site do not establish that the land is suitable for the intended development.
Commercial buildings, hotels and mixed-use projects may also face business interruption if flooding disrupts access or essential services. For rental investors, temporary closures and repairs can affect income even where the property remains structurally sound.
The appropriate investigation should therefore reflect the particular property type and the consequences of disruption, rather than applying one general coastal-risk assessment to every asset.
Coastal Flood Risk Across Different Asia-Pacific Markets
Asia-Pacific's coastal property markets are diverse. Major cities, established residential districts, resort destinations and remote islands have different economic roles and physical characteristics. Flood risk must be understood within that local context.
In large coastal cities, buyers may need to investigate drainage capacity, underground infrastructure, waterfront redevelopment and the relationship between the property and surrounding transport networks. In tropical resort markets, storm surge, intense rainfall, erosion and the reliability of roads and utilities may be particularly relevant.
Island locations can introduce additional considerations because alternative access routes, construction resources, emergency services and infrastructure may be limited. However, island properties are not all equally exposed: elevation, coastline shape, local development and building design can produce substantial differences.
International buyers should avoid assuming that an entire country or destination is either safe or unsafe for coastal property. Research should narrow from the country to the region, town or city, neighbourhood and individual site.
Building Design and Flood Resilience
The design and condition of a building can influence the consequences of flooding. Depending on the location, relevant features may include finished floor levels, drainage, foundations, construction materials, external openings, utility placement and the protection of electrical and mechanical equipment.
For existing property, buyers should examine the condition of the building and ask about previous flooding, water intrusion, repairs and any modifications made to address known problems. A property that appears recently renovated may still require investigation into concealed damage or the quality of previous work.
For new developments, the buyer should review the relevant specifications and approvals rather than relying solely on general statements about resilience. Where coastal exposure is material, an independent surveyor, engineer or other qualified specialist may be able to assess the building and site.
Resilience measures can reduce some risks but should not be treated as a guarantee against future damage. Their effectiveness depends on design, construction, maintenance and the conditions the property actually experiences.
Flood Risk and Property Insurance
Insurance is a central consideration when buying coastal property. Premiums, deductibles, exclusions and available coverage can influence both affordability and the financial consequences of a flood event.
Policies may treat different sources of water damage differently. Flooding, storm surge, wave damage, rainfall-related water intrusion and other hazards may not all be covered under the same terms. The existence of a general building policy therefore does not establish that the property has appropriate protection against the hazards relevant to its location.
International buyers should obtain property-specific insurance information before completing a purchase. They should establish the cost of available cover, the applicable excess or deductible, relevant exclusions and any conditions affecting the building or its use.
Insurance availability can also influence future ownership and resale. If cover becomes expensive or difficult to obtain, the property's operating costs and attractiveness to future purchasers may change. Buyers should consider this possibility as part of a broader financial assessment.
The Asia-Pacific property insurance guide provides further context for researching coverage and ownership risk.
How Coastal Flooding Can Affect Property Values
Flood exposure can influence property values through several channels. A building may require additional maintenance or repairs, insurance may become more expensive, and buyers may become more cautious about long-term ownership costs. Repeated disruption can also affect the appeal of a neighbourhood or destination.
These effects are not uniform. A coastal location may retain strong demand because of employment, transport, lifestyle amenities or limited suitable land, while individual properties within the same market may have very different levels of exposure.
For an overseas investor, it is important to assess both the attraction of the location and the financial consequences of its physical conditions. A premium price for a waterfront view should be considered alongside potential insurance costs, maintenance, access, drainage and resale demand.
Buyers should also consider the future purchaser. A property that appeals to a narrow group of international second-home buyers may have a different resale profile from one supported by a broad local residential market.
Coastal flood risk should therefore form part of the investment decision from the beginning, not merely an issue to investigate after a problem occurs.
Coastal Property and Rental Investment
Some coastal properties are purchased primarily for holiday rentals or resort-related income. In these cases, flooding can affect returns through direct repairs, temporary closures, disruption to visitor access and changes in demand following a significant event.
Investors should consider the full annual operating picture rather than relying on peak-season rental rates. Insurance, maintenance, property management, vacancy periods and potential repairs all affect net income. A coastal property may also require additional maintenance because of humidity, salt exposure and severe weather.
For developments managed by a building association or resort operator, buyers should establish how common-area repairs and infrastructure costs are allocated. Flood-related work may affect shared facilities and could lead to additional charges, depending on the ownership arrangements and applicable rules.
Rental projections should be treated as estimates rather than guaranteed returns. Buyers should test whether the investment remains financially viable if occupancy falls, costs increase or the property becomes temporarily unavailable.
The Asia-Pacific rental yield guide and property ownership costs guide provide useful frameworks for evaluating these expenses.
Buying Coastal Property From Overseas
Buying from abroad can make it harder to assess environmental conditions because the purchaser may initially rely on photographs, online listings, promotional material and information supplied by people involved in the sale. These sources may describe the property's appearance without providing enough evidence about its physical exposure.
International buyers should seek independent verification of the site's location, boundaries, elevation and relevant flood history. They should review available hazard maps and planning information, ask about previous damage and arrange a physical inspection where appropriate.
For a substantial purchase, specialist advice may be warranted. Depending on the location, this could involve a surveyor, engineer, drainage specialist, local lawyer or insurance professional. Each should address questions within their relevant area of expertise.
Buyers should also verify the seller's authority to sell, the property's title and the permitted ownership structure. Environmental due diligence does not replace legal due diligence, and a property with acceptable physical characteristics still needs to be legally suitable for the intended purchaser.
The guide to buying property from abroad and property due diligence guide provide further research pathways.
A Coastal Flood Risk Checklist for International Buyers
Before committing to coastal property, buyers should work through a structured checklist that considers the site, building, insurance, infrastructure and intended use.
- Establish the property's precise location, elevation and relationship to the shoreline.
- Investigate available flood maps, local hazard information and records of previous flooding or storm damage.
- Assess drainage, surface-water movement, access roads and the reliability of essential services.
- Research storm surge, erosion and other coastal hazards relevant to the location.
- Review the building's construction, condition, maintenance history and relevant approvals.
- Confirm whether protective structures exist and establish responsibility for their maintenance.
- Obtain property-specific insurance information and examine exclusions, deductibles and coverage limits.
- Estimate recurring ownership costs, including maintenance, insurance, service charges and potential repairs.
- Consider the effects of disruption on personal use, rental income and future resale.
- Obtain independent professional advice where the property's value or exposure justifies further investigation.
The purpose of this checklist is to identify questions that require reliable answers before the buyer becomes financially committed. If important information is unavailable or contradictory, further investigation may be necessary before proceeding.
Coastal Flooding as Part of Wider Property Risk
Coastal flooding should not be assessed in isolation. It can interact with climate conditions, building quality, infrastructure, insurance, ownership costs and the strength of the local property market. The overall effect depends on the location and the individual asset.
International buyers should also consider other physical hazards relevant to the area, including tropical cyclones, extreme rainfall, earthquakes, landslides and heat. A property can face several different risks, and the most important ones may not be obvious from a listing description.
IPD's Asia-Pacific climate risk guide provides a broader overview of environmental considerations, while the property risks guide covers the wider legal, financial, market and physical issues that can affect overseas purchases.
Researching Coastal Property Before Making a Decision
Coastal property can offer lifestyle appeal, access to tourism markets and opportunities for residential or commercial investment. Those attractions need to be weighed against the physical conditions of the site and the long-term costs of owning and operating the asset.
The most useful approach is to move from general market research to location-specific and property-specific investigation. Establish the local coastal environment, verify the site's exposure, assess the building and surrounding infrastructure, obtain insurance information and calculate realistic ownership costs.
For buyers researching Asia-Pacific from overseas, this process helps separate the general appeal of a coastal destination from the suitability of an individual property. It also provides a stronger basis for comparing locations, evaluating investment assumptions and considering future resale.
Coastal flooding does not automatically make a property unsuitable. It makes informed due diligence essential. The objective is to understand the exposure, establish the potential consequences and decide whether the property remains appropriate for the buyer's intended use, financial position and holding period.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

