
Asia-Pacific Vacation Rentals – Holiday Property and Rental Investment
Vacation rental property is an important part of the real estate market across many Asia-Pacific destinations. Holiday apartments, private villas, resort residences and other accommodation serve visitors who want alternatives to conventional hotels, while offering property owners the possibility of generating rental income when they are not using the property themselves.
The region contains a wide range of vacation rental environments, from established coastal destinations and tropical islands to major cities, cultural centres, mountain resorts and emerging tourism locations. Each operates under different conditions. Visitor demand, transport connections, seasonality, accommodation supply, local regulations and property management all influence whether a particular property can function as a viable vacation rental.
For overseas buyers, the key is to understand the tourism market behind the property before relying on projected occupancy or rental income. A desirable holiday destination does not automatically make every property within it a successful rental investment.
Understanding Asia-Pacific Vacation Rental Markets
Vacation rentals serve travellers seeking short-term accommodation for holidays, family visits, leisure activities, business trips and extended stays. The properties involved range from individual apartments and houses to villas, serviced residences and accommodation within resort developments.
Tourism plays different roles across Asia-Pacific. Some destinations have established international visitor markets, while others depend more heavily on domestic tourism, regional travel or particular seasons. Major cities can combine leisure visitors with business travellers, whereas island and coastal destinations may rely more directly on holiday demand.
The wider Asia-Pacific rental markets guide provides the regional context for understanding these differences.
Holiday Homes, Villas and Apartments
Vacation rental property is not a single asset class. The type of accommodation influences the likely guest profile, purchase price, operating costs, maintenance requirements and management arrangements.
A city apartment may appeal to couples, business travellers or visitors who want convenient access to restaurants, transport and attractions. A larger house or villa may suit families and groups seeking more space, privacy and outdoor facilities. Resort apartments can appeal to visitors who value shared facilities, reception services and access to leisure amenities.
Property selection should begin with the accommodation requirements of the intended guest rather than simply the appearance or advertised facilities of the property.
IPD's guides to Asia-Pacific apartments, houses and resort property provide further context on these different property types.

|
PHILIPPINES |
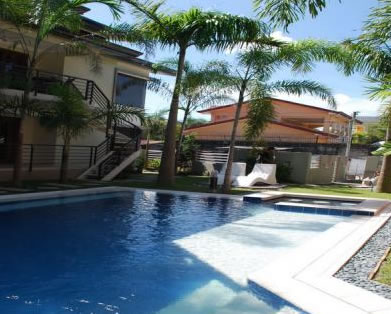
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Beachfront and Island Vacation Rentals
Beachfront and island destinations attract visitors looking for coastal scenery, swimming, water sports, relaxation and access to tourism facilities. Vacation accommodation can include apartments near beaches, private villas, island homes and residences within resort developments.
Location is particularly important in these markets. A property described as beachfront may have a different appeal from one requiring transport to reach the coast. Access to restaurants, shops, activities, airports and local services can also influence the type of visitor the property attracts.
Coastal properties may face additional maintenance and insurance considerations associated with humidity, salt exposure, storms, erosion and flooding. These factors can affect operating expenses and the long-term condition of the asset.
Explore the IPD guides to beachfront property and island property when assessing these specialised markets.
What Creates Vacation Rental Demand?
Vacation rental demand is connected to the reasons people visit a destination. Beaches, cultural attractions, heritage sites, outdoor activities, events, business centres, medical services and transport connections can all influence visitor numbers and accommodation requirements.
Different attractions generate different patterns of demand. A destination known for a particular holiday season may experience concentrated occupancy, while a major city with several visitor markets may attract guests throughout more of the year.
Accessibility also matters. Flight connections, airport transfers, ferry services, road access and local transport can influence how convenient a destination is for visitors. The presence of attractions alone does not establish that a particular neighbourhood will attract sufficient paying guests.
Investors should research the destination, the immediate location and the accommodation market separately. This helps identify whether demand is broad-based or dependent on a limited number of attractions, seasons or visitor groups.
Tourism Seasonality and Occupancy
Seasonality is one of the central considerations in vacation rental investment. Some destinations experience changes in visitor demand associated with weather, school holidays, festivals, public holidays or seasonal travel patterns. Others combine several tourism and business segments that help spread demand across the year.
A property with high occupancy during a peak holiday period may still experience extended vacancies during quieter months. Annual income therefore depends on the complete booking calendar rather than the strongest weeks of the year.
When examining a rental projection, investors should ask how occupancy estimates were calculated, which months they cover, whether they reflect comparable properties and whether the figures are based on completed operating results or promotional assumptions.
Realistic analysis should allow for quieter periods, cancellations, maintenance closures and the time required to prepare a property between guests.
Calculating Vacation Rental Income
Vacation rentals may charge nightly or weekly rates, but the amount advertised is not the same as the income retained by the owner. The financial result depends on achievable rates, occupied nights, operating expenses and the amount of time the property is available for letting.
Revenue estimates should be based on comparable accommodation with similar location, size, facilities, condition and guest capacity. A premium rate achieved by an exceptional villa may not be a realistic comparison for a standard apartment in the same destination.
Operating costs can include management commissions, booking platform charges, cleaning, laundry, utilities, internet, repairs, replacement furnishings, insurance, taxes, building charges and guest services. Depending on the property, the owner may also need to budget for marketing, inspections and periodic refurbishment.
Investors should distinguish between gross booking revenue, income after operating expenses and the final return after financing and tax. These measures answer different questions and should not be treated as interchangeable.
Vacation Rentals Compared With Long-Term Rentals
Vacation rentals and conventional long-term rentals operate under different business models. Short-term accommodation may offer greater flexibility in setting rates and allowing personal use, but it can require more active management and involve greater variation in occupancy.
Long-term residential rentals generally involve fewer tenant changes and a different pattern of maintenance and administration. Their income is usually assessed through agreed rental payments over a longer tenancy, rather than nightly bookings.
The appropriate comparison depends on the location, property type, legal framework and owner's objectives. A vacation rental should not automatically be assumed to generate more net income than a comparable long-term rental once vacancy, management, cleaning, utilities and other costs are included.
The Asia-Pacific long-term rental guide provides a useful comparison with conventional residential letting.
Foreign Ownership and Short-Term Rental Rules
International buyers need to establish two separate matters before purchasing vacation rental property: whether they can legally acquire the property and whether they can operate it as short-term accommodation.
Foreign ownership rules vary across Asia-Pacific. Restrictions may relate to land, apartments, property tenure, purchaser eligibility, location or the structure of ownership. Even where a foreign buyer can acquire a property, that ownership may not provide unrestricted permission to operate a vacation rental.
Local rules may require registration, permits, licences, safety compliance, tax reporting or approval for particular forms of accommodation. Building management rules, condominium regulations and development agreements can also restrict short-term letting.
These requirements should be verified for the specific country, municipality and property before purchase. The Asia-Pacific foreign ownership guide provides a starting point for researching the ownership side of the decision.
Resort Developments and Managed Holiday Property
Some vacation rental properties are purchased within resort or hospitality developments. These may offer shared facilities, reception, maintenance services, leisure amenities or access to an established tourism environment.
Management arrangements differ. Some developments allow owners to appoint their own managers, while others use an operator or offer a structured rental programme. The agreement may determine how bookings are allocated, how revenue is distributed, which expenses are deducted and when owners can use the property personally.
Before committing to a managed resort property, buyers should examine the complete agreement rather than relying on verbal descriptions of expected income. They should establish who controls bookings, how fees are calculated, what maintenance obligations apply and whether the owner can leave the rental programme or sell the property subject to existing arrangements.
The Asia-Pacific property development guide provides wider context on developments and the considerations involved in assessing them.
Buying New-Build or Off-Plan Vacation Property
New-build holiday apartments and villas can appeal to buyers seeking modern accommodation, contemporary facilities and reduced immediate refurbishment requirements. Some developments are marketed specifically towards second-home owners and rental investors.
Purchasing before completion introduces additional uncertainty. The final property, facilities, surrounding environment and local supply may differ from the original expectations, while completion delays can postpone the start of rental operations.
Investors should investigate the developer, planning approvals, construction arrangements, contract terms, payment schedule, completion provisions and intended management structure. They should also consider how many competing properties may enter the market before the development opens.
IPD's guides to new-build property and off-plan property explain the broader issues associated with these purchases.
Managing a Vacation Rental From Abroad
Distance can make vacation rental ownership more demanding for international buyers. Guest enquiries, bookings, arrivals, cleaning, maintenance, complaints and emergency repairs may need to be handled while the owner is in another time zone.
A local management company can coordinate these activities, but its responsibilities, fees and performance standards should be clearly understood. The owner should establish how bookings are reported, how expenses are approved, how rental income is transferred and who is responsible for inspecting the property.
Maintenance is particularly important in coastal and resort locations where humidity, salt exposure, heavy rain or periods of vacancy can contribute to deterioration. Regular inspections and prompt repairs can help protect both guest experience and the underlying property.
The managing property from abroad guide explores the practical responsibilities of remote ownership.
Personal Use and Rental Availability
Some buyers want a holiday property that they can use for part of the year and rent to visitors during other periods. This can combine lifestyle benefits with the possibility of generating income, but personal use reduces the number of nights available for bookings.
The timing of owner visits matters. If the property is reserved for personal use during periods of strong visitor demand, the financial effect may be different from using it during quieter months. The owner's preferred dates may also coincide with school holidays or peak tourism seasons.
Buyers should decide how much personal use they expect before calculating potential rental income. A property purchased primarily for family holidays may require a different financial assessment from one intended to operate as a full-time rental business.
Property Condition and Guest Expectations
Vacation rental accommodation competes on more than location. Cleanliness, maintenance, reliable facilities, comfortable furnishings, internet access, safety and accurate property descriptions can influence guest satisfaction and repeat bookings.
Guest expectations vary by price point and property type. A luxury villa may require landscaping, pool maintenance, specialist servicing and higher standards of presentation, while a smaller apartment may have fewer facilities but still require consistent cleaning and reliable equipment.
Investors should allow for the ongoing cost of keeping the property suitable for paying guests. Furniture, appliances, linens, air-conditioning systems and other equipment may need periodic repair or replacement, even when the property itself remains structurally sound.
Environmental and Insurance Considerations
Many Asia-Pacific vacation rental destinations are coastal, tropical or island locations. Depending on the property, relevant risks may include storms, flooding, coastal erosion, earthquakes, landslides, extreme heat or other local environmental conditions.
These risks can affect building condition, access, maintenance, operating interruptions and insurance availability. A property with attractive holiday appeal should still be examined for drainage, construction quality, exposure to natural hazards and the practical availability of suitable insurance.
Buyers should investigate the specific location rather than assume that all properties in a destination share the same risk profile. The Asia-Pacific climate risk guide provides additional context for assessing environmental factors.
Currency, Tax and Ownership Costs
International owners may receive rental income in a local currency while paying some expenses or measuring investment returns in another currency. Exchange-rate movements can change the value of income transferred home, even when local booking revenue remains stable.
Tax obligations can arise in the property location and, depending on the owner's circumstances, in the country where the owner is tax resident. Applicable rules may cover rental income, property ownership, business activity, transaction costs and eventual disposal.
Other ownership costs can include property management, building charges, insurance, utilities, maintenance and professional services. These should be considered alongside purchase costs and any financing commitments before the property is acquired.
The currency and money transfers guide covers the financial considerations of cross-border property ownership.
Vacation Rental Risks and Exit Planning
Vacation rental investment can be affected by changes in visitor demand, competition, accommodation regulations, operating costs and local economic conditions. A property may perform differently from its original projections if new accommodation enters the market or the destination's visitor profile changes.
Investors should also consider the eventual resale market. Some holiday properties appeal to both personal-use buyers and rental investors, while others depend on a narrower group of purchasers or a specific management arrangement.
Ownership restrictions, lease terms, building condition, location, ongoing costs and the ability to transfer management agreements can all influence resale options. The property risks and exit and liquidity guides provide wider context for this assessment.
Researching a Vacation Rental Investment
A structured research process begins with the destination and then narrows to the local accommodation market, property type and individual asset. Buyers should establish the source of visitor demand, the seasonality of bookings, the competing supply and the practical accessibility of the location.
The next step is to verify foreign ownership eligibility and the rules governing short-term letting. The property's title, condition, management agreement, insurance, taxes and operating costs should then be investigated independently.
Finally, projected rental income should be tested against realistic occupancy, achievable rates, all operating expenses and the owner's intended personal use. For new developments, the assessment should also consider construction risk and the supply of competing properties expected to enter the market.
Asia-Pacific Vacation Rental Property Research
Vacation rental property across Asia-Pacific encompasses city apartments, beach houses, private villas, island residences and managed resort accommodation. These properties may share a tourism connection, but their operating models, tenant demand, costs and ownership arrangements can be very different.
For overseas buyers, the essential task is to understand both the destination and the individual property. Tourism demand must translate into realistic bookings, the property must be legally suitable for its intended use, and the expected income must account for management, maintenance, vacancy and other expenses.
Explore the wider Asia-Pacific rental property section for rental investment, long-term rentals, rental yields and property management, or use the Asia-Pacific property markets guide to continue researching countries and locations before narrowing your search to individual vacation properties.
Asia Pacific Residential Rental Yield Comparison by Key International Markets (2026)
| Location | Typical Rental Property | Indicative Gross Rental Yield | Rental Market Character |
|---|---|---|---|
| Singapore | Condominiums, luxury apartments, serviced residences, penthouses, landed homes and investment properties | Approx. 2.5% - 4% Prime luxury property generally toward the lower end |
Singapore is one of Asia's most established and expensive residential investment markets. High property prices tend to keep percentage rental yields relatively modest, although well-located smaller apartments can provide stronger income returns. Strong tenant demand, limited land and international business activity support a deep rental market. Current broad-market data places Singapore among Asia's lower-yield residential markets. |
| Hong Kong | City apartments, luxury apartments, serviced residences, penthouses, waterfront homes and investment properties | Approx. 2.5% - 4% | Hong Kong combines extremely high property values with a substantial long-term rental market. Smaller apartments and properties outside the most expensive districts can produce higher percentage yields than prime luxury residences. Current 2026 data indicates average gross residential yields of around the mid-3% range, making Hong Kong primarily a capital-intensive international market rather than a high-yield market. |
| Tokyo, Japan | City apartments, investment apartments, luxury residences, serviced apartments, detached homes and new developments | Approx. 3.5% - 5.5% Smaller investment apartments can be higher |
Tokyo has a deep and highly developed rental market supported by a huge metropolitan population, employment, tourism and international investment. Smaller apartments can provide stronger percentage yields than large luxury residences. Japan's established legal and infrastructure environment also makes Tokyo an important income-property market for international investors. Current broad Asian data places Japan around the mid-4% average range. |
| Osaka and Kyoto, Japan | City apartments, investment apartments, traditional houses, vacation homes, luxury residences and resort properties | Approx. 4% - 6% | Osaka generally offers a broader and more income-oriented rental market than Tokyo, while Kyoto has a stronger tourism and short-term accommodation component. Smaller apartments and properties close to transport and employment centres can produce attractive gross yields. Holiday letting can produce different revenues but involves greater management and seasonality. |
| Seoul, South Korea | Luxury apartments, high-rise residences, smaller investment apartments, serviced residences and new developments | Approx. 3.5% - 5% | Seoul is a large and sophisticated metropolitan rental market dominated by apartments. Prime residential values can compress percentage yields, while smaller units and locations outside the most expensive districts can provide stronger income returns. South Korea's major employment, technology and cultural centres support substantial rental demand. Broad 2026 data places South Korea around the low-to-mid 4% range. |
| Taipei, Taiwan | City apartments, smaller investment apartments, luxury residences, new-build apartments and mixed-use developments | Approx. 2% - 3.5% | Taipei is a mature urban rental market with strong domestic demand and substantial technology-sector employment. High purchase prices relative to rents limit gross yields, particularly in prime districts. Smaller apartments and properties outside the most expensive central areas can provide better income percentages. Current broad-market data places Taiwan toward the lower-yield end of Asia Pacific. |
| Shanghai, China | Luxury apartments, high-rise residences, serviced apartments, villas and investment properties | Approx. 2.5% - 4% | Shanghai has a large and sophisticated residential rental market supported by business, finance, technology and international employment. Prime property values tend to suppress gross yields, while smaller apartments and properties in established rental districts can produce stronger returns. China's broader residential rental market remains considerably more yield-oriented in some secondary locations than in Shanghai's prime districts. |
| Beijing, China | Luxury apartments, high-rise residences, villas, serviced residences and investment apartments | Approx. 2.5% - 4% | Beijing is a major employment and administrative centre with a large conventional rental market. Rental performance varies significantly between central luxury districts, established residential areas and outer metropolitan locations. Current broad-market data places China's residential yields below most Southeast Asian markets, with Beijing generally toward the lower end of the regional range. |
| Bangkok, Thailand | Condominiums, serviced apartments, luxury apartments, investment units, townhouses and new developments | Approx. 5% - 7% Smaller investment units can be higher |
Bangkok is one of Southeast Asia's major international rental and investment markets. Condominiums near mass transit, employment centres and established expatriate districts are particularly relevant to overseas investors. Current 2026 data places Thailand among the higher-yielding established Asian markets, with country-level gross yields around the mid-6% range. |
| Phuket and Thai Resort Markets | Resort apartments, condominiums, beachfront villas, branded residences, holiday homes and investment properties | Approx. 5% - 8% Short-term holiday yields can vary considerably |
Phuket combines long-term residential demand with a major international tourism and holiday-rental market. Well-located condominiums can produce attractive gross yields, while villas and luxury resort properties often rely more heavily on seasonal and short-term letting. Occupancy, management fees and tourism cycles can materially affect actual returns. |
| Kuala Lumpur, Malaysia | Condominiums, serviced residences, luxury apartments, investment units, penthouses and gated developments | Approx. 4.5% - 6% | Kuala Lumpur provides one of Southeast Asia's more accessible major-city investment markets. Large condominium and serviced-residence supply provides a wide choice of rental property. Central business districts, established expatriate areas and properties close to transport can attract stronger tenant demand. Current broad-market data places Malaysia around the mid-5% gross-yield range. |
| Penang, Malaysia | Condominiums, waterfront apartments, serviced residences, landed homes, heritage properties and resort residences | Approx. 4% - 6% | Penang combines conventional residential demand with tourism, expatriate and lifestyle rental markets. Apartments and condominiums in established locations can provide reasonable gross rental returns, while premium waterfront and heritage properties may produce lower percentage yields. The market is generally more accessible than Singapore. |
| Bali, Indonesia | Villas, resort residences, apartments, branded residences, holiday homes and tourism-linked properties | Approx. 6% - 10% Short-term villa yields can vary substantially |
Bali is one of Asia's major international lifestyle and tourism rental markets. Villas and resort residences can produce strong gross rental income where occupancy is high, particularly in established tourism areas. However, short-term rental performance is highly dependent on seasonality, management, furnishing, local regulations and operating costs. Current Indonesia-wide data is among the highest in Asia Pacific. |
| Jakarta, Indonesia | Luxury apartments, condominiums, serviced residences, investment apartments and high-rise developments | Approx. 6% - 9% | Jakarta has a substantial urban rental market supported by business, employment and expatriate demand. Apartments can provide relatively strong gross yields compared with the city's purchase prices, particularly in established business and expatriate districts. Indonesia's current broad-market residential yield is among the strongest in Asia Pacific, although individual Jakarta properties vary considerably. |
| Manila, Philippines | Condominiums, apartments, serviced residences, investment units, penthouses and new developments | Approx. 4.5% - 6% | Manila has a large condominium rental market supported by business services, expatriate employment, population growth and tourism. Smaller units in locations close to employment and transport can produce stronger yields than premium residences. Current Philippine residential yield data is around the 5% level on a broad-market basis. |
| Cebu and Philippine Resort Markets | Condominiums, resort apartments, beachfront residences, villas, holiday homes and investment properties | Approx. 5% - 8% Holiday rentals can produce higher gross revenues |
Cebu combines a conventional urban rental market with tourism and resort demand. Condominiums close to employment, universities and transport can provide relatively consistent long-term rental income, while resort properties depend more heavily on tourism, occupancy and seasonal demand. Management and operating costs should be assessed carefully. |
| Ho Chi Minh City, Vietnam | Luxury apartments, condominiums, serviced residences, investment apartments and new developments | Approx. 3% - 5% | Ho Chi Minh City has a large and expanding apartment rental market supported by business, manufacturing, professional employment and expatriate demand. Prime luxury developments generally produce lower percentage yields than more affordable investment apartments. Current Vietnam-wide gross residential yields are around the high-3% range, with individual city districts varying substantially. |
| Hanoi, Vietnam | Luxury apartments, condominiums, serviced residences, villas, gated communities and investment properties | Approx. 3% - 5% | Hanoi has a substantial conventional rental market alongside growing demand for modern apartments and expatriate-oriented housing. Yields vary by district, property type and purchase price. Modern apartments in established employment and international districts can provide stronger rental performance than high-end luxury residences. |
| Phnom Penh, Cambodia | Condominiums, serviced apartments, apartments, villas, gated communities and investment properties | Approx. 6% - 9% | Phnom Penh is one of the more income-oriented emerging residential markets in the region. Condominium and serviced-apartment developments provide a substantial rental-investment sector, while lower purchase prices can support higher gross yields than the mature gateway markets. Cambodia's broad 2026 residential yield is among the highest in Asia Pacific. |
| Goa, India | Villas, apartments, resort residences, holiday homes, gated communities and investment properties | Approx. 4% - 7% | Goa combines conventional residential rentals with tourism and seasonal holiday accommodation. Villas and apartments in established tourism areas can generate attractive gross income, but occupancy can vary considerably through the year. Long-term and short-term rental economics should be assessed separately. |
| Mumbai, India | Luxury apartments, high-rise residences, smaller investment apartments, serviced residences and branded residences | Approx. 3.5% - 5.5% | Mumbai is one of India's highest-value residential markets, with strong rental demand from financial, professional and business sectors. High capital values limit percentage yields in many prime districts, while smaller apartments and properties in established rental locations can produce stronger income returns. India's broad residential yield is currently around the 5% level. |
| Delhi and National Capital Region, India | Apartments, luxury residences, gated communities, villas, serviced apartments and investment properties | Approx. 4% - 6% | Delhi and the wider National Capital Region provide a large and diversified rental market. Gurgaon and Noida have developed substantial modern apartment sectors linked to business and technology employment. Smaller investment apartments can offer stronger percentage yields than premium family residences and large villas. |
| Maldives | Resort residences, beachfront villas, branded residences, private-island properties and hotel-linked accommodation | Approx. 4% - 8% Highly dependent on resort performance and management structure |
The Maldives is a specialist luxury tourism property market rather than a conventional urban rental market. Rental income is closely linked to resort occupancy, tourism performance, management agreements and the structure of branded or hotel-linked residences. Gross income figures should therefore not be compared directly with conventional long-term residential yields. |
| Sri Lanka | Beachfront villas, apartments, resort residences, furnished apartments, city residences and holiday homes | Approx. 4% - 7% | Sri Lanka combines conventional urban rental demand with tourism and coastal holiday accommodation. Colombo provides the main long-term residential market, while southern and western coastal areas have greater exposure to tourism and seasonal demand. Villas and holiday properties can produce different gross returns from conventional apartments. |
| Sydney, Australia | Apartments, luxury apartments, waterfront residences, detached houses, townhouses and investment properties | Approx. 3.5% - 5.5% Smaller apartments generally toward the upper end |
Sydney is a mature and highly developed rental market with strong long-term tenant demand but very high property values. Apartments generally provide higher percentage yields than detached houses and prime waterfront residences. Current 2026 market data shows Sydney apartment yields around the mid-4% to mid-5% range depending on location and unit size. |
| Melbourne, Australia | Apartments, detached houses, townhouses, investment apartments and new developments | Approx. 3.5% - 5.5% | Melbourne provides a large diversified rental market supported by employment, education, population growth and international students. Apartments generally provide stronger gross yields than higher-value detached houses. Current Australian data places the broad market around the 5% level, although city and property-type differences are substantial. |
| Brisbane and Queensland, Australia | Apartments, houses, waterfront properties, townhouses, resort residences and investment properties | Approx. 3.5% - 5.5% | Brisbane and Queensland combine metropolitan, coastal and lifestyle rental markets. Population growth and constrained housing supply have supported rental demand, while coastal and tourism markets introduce additional seasonal factors. Current market conditions vary considerably between Brisbane, Gold Coast, Sunshine Coast and other Queensland locations. |
| Auckland, New Zealand | Apartments, detached houses, townhouses, waterfront homes, lifestyle properties and investment residences | Approx. 3.5% - 5% | Auckland has New Zealand's largest conventional residential rental market. Detached houses form a major part of the rental stock, while apartments can provide higher percentage yields in selected locations. Current broad-market data places New Zealand around the low-4% range, with substantial variation between Auckland neighbourhoods and property types. |
| Fiji | Beachfront villas, resort apartments, resort residences, holiday homes and investment properties | Approx. 4% - 7% Tourism properties can vary considerably |
Fiji provides a specialist resort and lifestyle rental market rather than a large conventional urban investment market. Rental performance is closely linked to tourism, occupancy, resort management and location. Beachfront and resort properties can generate attractive gross income, but management and seasonal costs can be significant. |
| Macau | High-rise apartments, luxury residences, serviced apartments, waterfront developments and investment properties | Approx. 1.5% - 3% | Macau is a highly developed and densely built residential market with strong connections to tourism, hospitality and the wider Greater Bay Area. Very high property values relative to residential rents result in relatively low gross yields compared with Southeast Asian markets. Current broad-market data places Macau among Asia Pacific's lowest-yield residential markets. |
Rental yields shown are broad indicative gross rental yields for 2026 and are intended as a market comparison guide rather than formal investment forecasts. Gross yield is generally calculated from annual rental income divided by the property's purchase price before service charges, maintenance, management fees, vacancy, insurance, taxes, financing costs and other ownership expenses. Current Asia Pacific data shows substantial differences between markets: Indonesia and Cambodia are among the higher-yield markets, while Singapore, Hong Kong, Taiwan and Macau generally produce lower percentage yields because of high property values relative to rents. Japan, Thailand, Malaysia, India and the Philippines occupy a broad middle range, although individual cities and property types can vary considerably. Apartments and smaller investment units often produce higher percentage yields than large houses, prime waterfront properties and ultra-luxury residences. Short-term and holiday rentals can produce different gross revenues but involve greater management requirements, seasonality, furnishing costs, vacancy risk and operating expenses. Resort markets such as Bali, Phuket, the Maldives and Fiji should not be directly compared with conventional long-term residential markets without considering occupancy and management arrangements. Overseas buyers should consider purchase price, rental demand, occupancy, service charges, taxation, ownership rules, currency movements, financing, property management, liquidity and local market conditions before relying on any rental-yield figure. Rental yields and property regulations can change, so current local data should be verified before making an investment decision.
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

