
Asia-Pacific Property Exit and Liquidity Risk – Guide for International Buyers
Buying property in Asia-Pacific is often approached from the perspective of acquisition: where to buy, what property to choose and what price to pay. For an international buyer, however, the eventual exit can be just as important. At some point the owner may want to sell, transfer, refinance, pass the property to another owner or simply recover the capital invested.
This creates an important distinction between property value and property liquidity. An asset may have a substantial theoretical value but still take considerable time to sell if the pool of potential buyers is small. This is particularly relevant to overseas owners who may be selling from another country and cannot easily manage viewings, negotiations and documentation themselves.
Asia-Pacific contains highly liquid metropolitan markets alongside emerging cities, remote locations, resort destinations, islands and specialist property markets. Exit conditions can therefore vary dramatically between countries, cities, neighbourhoods and property types.
What Is Property Liquidity?
Property liquidity refers broadly to how easily a property can be sold at a reasonable market price within an acceptable period. Unlike a financial asset traded on an exchange, a property requires an individual buyer, due diligence, negotiation, legal documentation and completion.
Liquidity is therefore not simply a question of whether properties are selling. A market can have active transactions while a particular property remains difficult to sell because it is unusually expensive, remote, specialised or subject to ownership restrictions.
For an international buyer, the relevant question is not only whether property changes hands in the market, but whether this particular property is likely to have a sufficiently broad pool of future purchasers.
Why Exit Risk Matters Before Buying
Exit planning should begin before the purchase rather than when the owner decides to sell. By then, the buyer has already committed capital to the location, property type and ownership structure.
Before purchasing, an international buyer should ask who is likely to purchase the property in the future. Potential buyers could include local households, domestic investors, expatriates, retirees, businesses, developers, neighbouring owners or other international buyers.
The answer matters because a property dependent on one narrow category of purchaser may be more vulnerable if that demand weakens. A conventional apartment in an established city may have several potential buyer groups, while a remote villa, development parcel or specialist tourism property may depend on a much smaller audience.

|
PHILIPPINES |
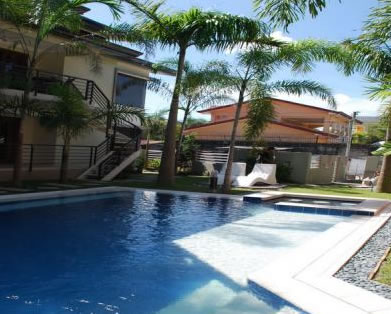
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Local, Regional or International Demand?
The depth of the future buyer market can be considered at several levels. Some properties are primarily purchased by local residents. Others attract domestic investors, while particular city or resort markets may have substantial regional or international demand.
A property marketed internationally is not necessarily internationally liquid. Global advertising can create exposure, but exposure does not guarantee that a sufficient number of qualified buyers can legally purchase, finance and complete the transaction.
Foreign ownership rules may also reduce the future buyer pool. If only certain categories of overseas purchasers can acquire the property, the owner may be competing for buyers within a much smaller market than the headline population of the country suggests.
The Asia-Pacific foreign buyers guide provides wider context on how ownership rules can affect international purchasers.
Location and Resale Liquidity
Location is one of the most important influences on resale demand. Major metropolitan areas can provide access to employment, education, transport, services and established residential markets. Smaller cities and emerging locations may offer growth potential but can have a narrower resale market.
Within the same city, liquidity can vary between neighbourhoods. A property close to established transport, employment and amenities may appeal to a broader group than an otherwise similar property dependent on a future infrastructure project.
Remote and island properties require particular attention. Limited transport, smaller populations and dependence on tourism can restrict the number of buyers. The lifestyle appeal may be strong, but the future resale market can still be relatively narrow.
Property Type and the Size of the Buyer Pool
Property type can have as much influence on liquidity as location. Standard residential apartments and houses may appeal to a broad range of buyers, while specialised assets can require a more specific purchaser.
Luxury property, beachfront villas, resort residences, development land, commercial assets and unusual properties can all have smaller buyer pools. This does not make them inherently poor investments, but it can mean that selling requires more time, specialist marketing or a greater adjustment to the asking price.
Development property can present a particularly different exit profile. A buyer acquiring land may eventually need another developer or investor rather than an ordinary residential purchaser. The market therefore needs to be assessed according to the actual use and legal characteristics of the property.
Price Can Affect Liquidity
Price is not simply an indicator of value; it can directly influence the number of potential buyers. A property may be correctly valued within its market but still have limited liquidity because relatively few buyers can afford it.
This is particularly relevant to luxury and high-value property. The higher the price, the smaller the potential purchaser pool may become. The owner may therefore need to allow for longer marketing periods and a more specialised sales process.
Overpricing can reduce liquidity further. If comparable properties are available at lower prices, prospective buyers have little reason to accept a premium unless the property has clear advantages in location, quality, tenure, views, amenities or another measurable characteristic.
Market Conditions and Timing the Exit
Property liquidity changes with market conditions. During periods of strong demand, buyers may compete for desirable property and transactions can move relatively quickly. When financing becomes more difficult or buyer confidence weakens, the same property can take longer to sell.
International owners should therefore avoid assuming that a property can always be sold quickly simply because the market was active when they purchased it. Interest rates, economic conditions, employment, migration, tourism, construction activity and investor sentiment can all influence demand.
Supply is equally important. A large number of competing properties can give buyers greater choice and reduce the negotiating power of individual sellers. New developments may also compete directly with existing properties by offering new specifications, payment plans or incentives.
The Asia-Pacific property market cycles guide provides a wider framework for considering changing market conditions.
Off-Plan and New Development Exit Risk
Off-plan purchases can create a different type of exit risk because the owner may want to sell before the property is completed. Some contracts restrict assignment, require developer approval or impose conditions before a purchaser can transfer their interest.
Even after completion, the resale market may contain a large number of units from the same development. If many original buyers attempt to sell at the same time, competition between owners can affect prices and selling periods.
Buyers considering off-plan property should therefore examine not only the anticipated completed value but also the rules governing resale before completion and the expected volume of competing stock at handover.
The Asia-Pacific off-plan property risk guide provides additional information on this area.
Foreign Ownership and the Future Buyer
Foreign ownership rules can affect liquidity in two directions. They may restrict the original buyer's ability to acquire a property, and they may also restrict who can purchase it later.
An overseas owner should establish whether the property can be sold to another foreign buyer, whether the purchaser must meet residency or nationality requirements and whether any approvals are required for transfer.
Leasehold arrangements can introduce additional considerations. The remaining term of a lease may become increasingly important as the property approaches expiry, while renewal rights and costs can affect the property's attractiveness to future buyers.
Ownership structure should therefore be considered as part of exit planning rather than only as a purchase requirement.
Selling Property From Overseas
International ownership can make the practical process of selling more complicated. An owner living thousands of kilometres away may need someone locally to coordinate inspections, maintenance, documents, agents, lawyers and the completion process.
Remote selling is easier where professional property management and established legal and agency services are available. It can be more difficult in markets where transactions depend heavily on personal involvement or where the international owner has limited local contacts.
Before buying, the owner should consider how the property could realistically be marketed and sold without being physically present. A property that requires frequent local supervision may have a different practical exit profile from a professionally managed apartment in an established city.
The Asia-Pacific guide to selling to international buyers provides further context for overseas property transactions.
Transaction Costs Can Reduce the Exit Value
The amount received by a seller is not necessarily the same as the property's headline market value. Legal fees, agency commissions, taxes, transfer charges, outstanding service costs, maintenance requirements and other transaction expenses can reduce the net proceeds.
International owners should also consider whether tax rules differ for residents and non-residents and whether selling property can create a capital gains or other tax liability. These costs can materially affect the return from an investment, particularly where the property has only appreciated modestly.
The Asia-Pacific property transaction costs guide and capital gains tax guide provide broader research starting points.
Currency Risk at Exit
For an international buyer, the final return may depend on more than the property's local sale price. Currency movements can change the value of the proceeds when converted into the owner's home currency.
An owner may have purchased when the exchange rate was favourable and sell when it has moved significantly in the opposite direction. The local property may have increased in value while the owner's home-currency return is substantially different from the apparent local gain.
This becomes more complex where the buyer's income, mortgage, property value, rental income and eventual sale proceeds are all denominated in different currencies. Currency should therefore be considered alongside the intended holding period and exit strategy.
See the Asia-Pacific currency risk guide for additional context.
Rental Property and Exit Liquidity
Rental income can make a property attractive during ownership, but it does not guarantee an easy exit. A property should be assessed according to both its income characteristics and its eventual resale market.
A rental property in an established residential market may have several potential buyer groups, including owner-occupiers and investors. A specialist holiday rental may depend much more heavily on investor expectations about tourism and future rental income.
Changes to short-term rental regulations, tourism patterns, vacancy rates or management costs can also affect the attractiveness of the property to future buyers.
The Asia-Pacific rental investment guide provides a wider framework for assessing income-producing property.
How to Assess Liquidity Before Buying
A practical liquidity assessment should start with the future purchaser rather than the current seller. Identify the groups most likely to buy the property and then consider how large and active those groups are.
Next, examine recent comparable transactions where reliable information is available. Consider the number of competing properties, typical marketing periods, financing availability, ownership restrictions and the difference between asking prices and achievable selling prices.
The assessment should then be repeated under a less favourable scenario. What happens if prices remain flat? What if the property takes a year or more to sell? What if the buyer pool is smaller than expected? What if the owner needs to sell during a weaker part of the market cycle?
This approach does not predict the future, but it can reveal whether the investment depends on being able to sell quickly at an optimistic price.
A Property Exit Checklist for International Buyers
Before buying, an overseas purchaser should be able to answer several practical questions. Who is likely to buy the property in the future? Can both local and foreign buyers acquire it? Is the property type widely traded? How large is the competing supply? Can buyers obtain finance?
The buyer should also understand the ownership structure, remaining lease term if applicable, taxes on resale, agency and legal costs, currency exposure and the practical arrangements required to sell from overseas.
For investment property, the assessment should include both rental demand and eventual resale demand. For development or off-plan property, assignment rights, completion risk and future competing supply should also be considered.
Liquidity Is Part of the Investment, Not an Afterthought
The most attractive property is not always the property with the highest projected appreciation. For an international owner, the ability to sell when circumstances change can be equally important.
A property with broad demand, clear ownership, established infrastructure, accessible financing and a substantial resale market may provide a different risk profile from a cheaper property that depends on a narrow group of future buyers.
Asia-Pacific offers opportunities across major cities, emerging markets, resorts, islands and specialist property sectors. Each can have a valid role in an international property portfolio, but the future exit needs to be considered alongside the original purchase decision.
The key question is simple: if you needed to sell this property in the future, who would buy it, why would they buy it and how easily could the transaction actually take place?
Answering those questions before purchasing can help international buyers distinguish between a property that merely appears attractive to acquire and one that also has a credible long-term exit market.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

