
East Asia Property Investment Markets - International Investor Guide
East Asia contains some of the world's most established property markets alongside markets with very different ownership structures, development cycles and investment characteristics. For an overseas investor, therefore, East Asia is not a single property market. China, Japan, South Korea, Taiwan and Mongolia each present a different combination of economic structure, urban development, property types, regulation, financing and access for international buyers.
This makes geographical research particularly important before comparing investment opportunities. An investor researching the region from outside Asia Pacific may initially see East Asia as a collection of major cities, but the underlying property markets can operate very differently. Tokyo's mature urban market, Seoul's highly developed metropolitan economy, China's large and varied city system, Taiwan's concentrated urban markets and Mongolia's resource-linked economy each require a different approach.
The broader East Asia property markets guide provides the geographical framework for understanding these differences. Investment analysis then becomes more useful when individual markets are considered according to their location, property type, ownership rules, rental demand, development activity and intended investment period.
Why East Asia Requires a Market-by-Market Investment Approach
Property investment across East Asia is shaped by major differences in population concentration, land availability, urban density, infrastructure, planning systems and economic activity. A strategy that makes sense in a large metropolitan market may have little relevance in a smaller or more specialised market.
Major cities are particularly important because property demand tends to concentrate around employment, transport, education, business services, tourism and established infrastructure. Yet even within one country, the relationship between the principal city and secondary locations can vary considerably. Investors therefore need to distinguish between national economic conditions and the characteristics of the particular city or property market being considered.
This geographical perspective is especially important for international buyers. Someone purchasing a property from overseas is not simply selecting an asset; they are also selecting a legal jurisdiction, currency exposure, management environment and local market in which they may have limited firsthand experience.

|
PHILIPPINES |
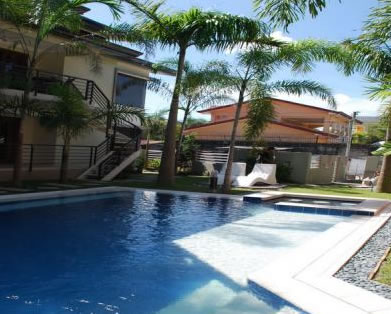
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Established Markets and Different Investment Profiles
Japan and South Korea illustrate how established East Asian markets can still contain very different investment opportunities. Japan has a highly developed property system extending from major metropolitan offices and residential property to hotels, logistics, retail and regional markets. Tokyo is the dominant international reference point, while Osaka, Kyoto and Fukuoka demonstrate how different city economies can create distinct property conditions.
South Korea is similarly urbanised but has its own highly concentrated metropolitan structure. Seoul is the principal international investment centre, while Busan and other locations provide a different combination of residential, commercial, industrial, tourism and redevelopment opportunities. The relationship between land, transport infrastructure and population concentration is particularly important when assessing Korean property.
China operates on a much larger geographical scale. Its property markets range from global business centres to rapidly changing regional cities and specialised tourism or development locations. China should therefore be approached as a network of city and regional markets rather than as one uniform investment environment. China property investment requires consideration of the particular city, property sector, ownership structure and applicable rules.
China: Scale, Urbanisation and Market Diversity
China's size creates one of the most important distinctions in East Asian property research. Beijing, Shanghai and Shenzhen have very different economic roles, development histories and property characteristics, despite all being major metropolitan markets.
Beijing's importance is closely associated with government, business, professional services, education and established urban districts. Shanghai has a strong international commercial role and a broad property base extending across residential, retail, office, logistics and hospitality uses. Shenzhen has a particularly important relationship with technology, advanced manufacturing, entrepreneurship and the wider Pearl River Delta economic system.
These differences matter to investors because property demand is connected to the underlying economy of each city. A city dominated by financial and professional services will generate different occupier requirements from a manufacturing and technology centre or a tourism-oriented location.
For overseas investors, China's foreign ownership framework, transaction procedures and taxation also need to be examined before investment decisions are made. Property investment should not be separated from the legal structure through which the asset is acquired and held.
Japan: Mature Urban Markets and Multiple Property Sectors
Japan provides a useful example of why a mature property market should not be treated as a single investment proposition. Tokyo has a vast metropolitan property economy, while Osaka, Kyoto and Fukuoka each have different demographic, commercial, tourism and residential characteristics.
The investment landscape extends beyond conventional residential property. Investors may examine apartments, hotels, commercial buildings, logistics facilities, development opportunities and other specialised assets. The appropriate property type depends heavily on the location and the intended source of demand.
International investors researching Japan should therefore move from the national market to the individual city and then to the property sector. The IPD Japan property investment guide can be considered alongside the individual Tokyo property market, Osaka property market, Kyoto property market and Fukuoka property market pages.
South Korea: Metropolitan Concentration and New Investment Sectors
South Korea's property investment structure is strongly influenced by its metropolitan concentration and the economic importance of Seoul. The capital region contains a substantial proportion of the country's business, employment, education and infrastructure activity, making location within the wider metropolitan area an important part of property analysis.
Seoul also demonstrates how an established property market can develop new investment sectors. Residential accommodation, offices, logistics, hospitality and specialised living assets can all respond to different forms of urban demand. Busan provides a contrasting market with a major port, tourism activity and a different metropolitan scale, while Jeju has a distinct relationship with tourism, second-home demand and island geography.
International investors should examine these markets through the country's foreign ownership and property buying frameworks rather than assuming that local and overseas purchasers face identical circumstances.
Taiwan: Urban Property, Industry and Location
Taiwan's property market is closely connected to its concentrated urban structure and globally significant industrial economy. Taipei has a different property profile from other urban and regional markets, while locations connected to technology, manufacturing, universities and transport infrastructure can develop their own sources of demand.
For an overseas investor, the relationship between employment centres and housing is particularly relevant. Residential property should be considered in relation to commuting patterns, transport links, employment concentrations and local development rather than simply comparing headline prices between cities.
Taiwan also illustrates why investment research should include the ownership and transaction framework before an asset is selected. The Taiwan foreign ownership guide and Taiwan property buying guide provide the next stages of that research.
Mongolia and the Role of Smaller East Asian Markets
Mongolia demonstrates a substantially different investment environment. Its property market is closely associated with the country's geography, urban concentration and economic dependence on natural resources. Ulaanbaatar dominates the country's urban property landscape, creating a very different relationship between city development and national population from the larger East Asian economies.
For investors considering a smaller or less mature market, liquidity, infrastructure, development quality, local demand and exit options become particularly important. An apparently attractive entry price does not by itself establish an investment case. The ability to rent, manage, finance and eventually sell the property is equally important.
The Mongolia property investment and Mongolia foreign ownership resources should therefore be considered together when assessing the market.
Residential Property Versus Commercial Investment
International investors often begin with residential property because it is easier to understand as an asset class. However, East Asia provides a broad commercial property landscape in which offices, logistics, retail, hotels, student accommodation, serviced accommodation and other specialised sectors can play important roles.
Residential investment itself covers a wide range of assets. Apartments in dense metropolitan districts behave differently from detached houses, resort property or development land. The intended use of the property also changes the analysis. A home intended for personal use may be assessed primarily through location and lifestyle, whereas a rental investment requires evidence of tenant demand, operating costs and property management.
IPD's broader apartments, houses, luxury property, commercial property and development land resources allow investors to follow the property type rather than treating every asset as equivalent.
Rental Demand as an Investment Consideration
Rental demand is one of the clearest ways to connect an investment property with the underlying economy. Employment centres, universities, tourism, transport infrastructure and population movement can all influence the type and location of rental demand.
International buyers should distinguish between long-term residential rental markets and short-term or tourism accommodation. These can have different tenant profiles, operating requirements, management arrangements and regulatory considerations. A property that appears suitable for short-term rental may therefore require a different assessment from one intended for conventional residential letting.
The regional Asia Pacific rental property and managing property from abroad guides provide useful context for investors who will own an East Asian property while remaining overseas.
Development Markets and Infrastructure
Property investment should also be viewed through the development cycle. New transport infrastructure, employment districts, redevelopment zones, tourism investment and urban regeneration can alter the relationship between established neighbourhoods and emerging locations.
Development land and off-plan property introduce another layer of risk because the investor is relying on a future asset rather than an established property. Construction costs, financing, planning, developer capability, completion arrangements and the eventual supply of competing property can all affect the outcome.
The IPD property development, off-plan development and developer risk resources are therefore relevant when an East Asian investment involves construction or redevelopment rather than an established property.
Comparing East Asian Investment Markets
There is no single measure that adequately compares East Asian property markets. International investors may need to examine liquidity, ownership access, property supply, rental demand, development activity, infrastructure, financing, taxation, currency exposure and the likely depth of the eventual resale market.
These factors can point in different directions. A large and liquid metropolitan market may provide greater choice but also greater competition. A smaller market may offer a different entry point but require more careful consideration of resale liquidity. A tourism market may have strong visitor demand while being more exposed to seasonal conditions. A development location may benefit from new infrastructure while carrying greater completion and timing risk.
This is why the compare property markets resource is a useful part of the research process. The objective is not simply to identify a market that appears attractive on one measure, but to understand how several characteristics interact.
Researching an East Asian Property Investment from Overseas
For an investor based outside Asia Pacific, the research process should normally move from geography to market structure, then to ownership, property type and transaction requirements. Starting with an individual listing can conceal important information about the wider market in which that property sits.
A more structured process begins by identifying the country and city, understanding the local property market, examining the types of property available to international purchasers, and then investigating ownership, taxation, financing and transaction procedures. Rental or investment analysis can follow once the underlying asset and location are understood.
Due diligence remains essential. Overseas investors may need local legal advice, independent property inspections, title verification, tax advice, currency planning and professional property management. The international property due diligence guide and lawyers and notaries guide address these parts of the purchase process.
East Asia as Part of a Wider International Property Search
East Asia should ultimately be assessed within the wider international property market. Investors comparing Tokyo with another global city, a Chinese metropolitan market with another major Asian centre, or a tourism property in East Asia with a European or Pacific destination need a consistent framework for understanding location, ownership, asset type, rental demand and investment risk.
The wider Asia Pacific investment markets section places East Asia within the larger regional property system, while the international capital and Asia Pacific property guide considers the relationship between overseas capital and regional markets.
For international buyers, the value of East Asia lies in the diversity of its property markets rather than in a single regional investment formula. Understanding the geography first, then narrowing the research to the country, city, property type and ownership structure, provides a more useful foundation for evaluating individual opportunities.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|
