
Mortgages and Property Finance in Asia Pacific - International Buyer Guide
Financing a property purchase in Asia Pacific can be very different from financing a home in the buyer's country of residence. Mortgage availability, deposit requirements, lending criteria, interest rates, currencies and rules affecting overseas buyers vary substantially between markets. A buyer who can readily obtain a mortgage at home cannot assume that the same borrowing structure will be available when purchasing property in another Asia Pacific country.
For international buyers, the financing question therefore begins before comparing mortgage rates. The first issues are whether the buyer can obtain local finance, what type of property can be financed, how much the lender may advance, which income and assets will be accepted, and whether the loan currency creates additional exposure.
Asia Pacific contains established mortgage markets such as Australia, New Zealand, Japan and Singapore alongside developing and resort-oriented markets where financing can be more restricted. The appropriate approach is to understand the characteristics of the particular market and then compare the available financing with the buyer's wider financial position.
Local Finance Is Not Automatically Available to an Overseas Buyer
One of the most important distinctions for an international purchaser is between being legally permitted to own property and being able to borrow locally to purchase it. These are separate questions.
A country may permit a foreign buyer to acquire a particular type of property while local banks apply more conservative lending criteria to non-residents. The bank may require a larger deposit, accept only certain types of property as security, require additional documentation or decline an application altogether.
Residency can also affect the financing calculation. Banks commonly distinguish between residents and non-residents because income earned overseas, foreign tax arrangements, different credit-reporting systems and currency exposure can make underwriting more complicated.
The Asia Pacific guide for foreign property buyers should therefore be considered alongside mortgage research rather than treating ownership eligibility and finance as the same issue.
The Deposit Is More Than a Down Payment
The deposit is the part of the purchase price that the buyer provides without borrowing against the property. Its size directly affects the loan-to-value ratio, or LVR, and therefore the amount of financing required.
For an international buyer, however, the required cash contribution may extend beyond the deposit itself. The buyer may also need funds for taxes, registration, legal work, valuation, inspections and other acquisition costs. These expenses normally need to be budgeted separately from the amount available for the property deposit.
A larger deposit can reduce the size of the mortgage and may improve the overall lending profile, but the buyer should not assume that every additional dollar of available capital should automatically be committed to the purchase. Maintaining sufficient liquidity for completion and subsequent ownership is particularly important when buying from abroad.
Loan-to-value rules can also be imposed at the banking-system level. In New Zealand, for example, current Reserve Bank settings limit the proportion of new residential lending that banks can make above specified LVR thresholds, while individual banks retain their own lending criteria.

|
PHILIPPINES |
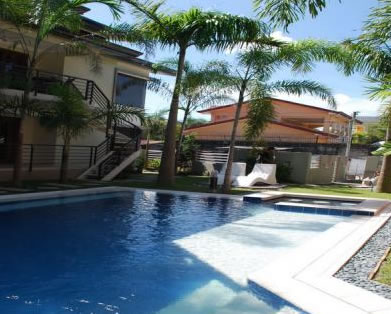
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


How Loan-to-Value Ratios Affect International Buyers
The loan-to-value ratio compares the amount borrowed with the value of the property securing the loan. A property purchased for $800,000 with a $600,000 mortgage has an LVR of 75 percent, leaving the buyer to provide the remaining 25 percent from other funds.
LVR is useful because it provides a common way of comparing mortgage structures between markets. It does not, however, mean that a bank will automatically lend up to that percentage. A lender can impose a lower maximum based on the borrower, property, income, currency or other circumstances.
New Zealand demonstrates the distinction clearly. Its Reserve Bank currently permits a defined share of new owner-occupier lending above 80 percent LVR and a smaller share of investor lending above 70 percent LVR, but individual banks still apply their own lending policies.
For an overseas purchaser, the practical question is therefore not simply “What is the maximum LVR?” but “What LVR is realistically available to this borrower for this property?”
Income Assessment Can Be More Complicated From Abroad
Mortgage lenders need to establish that a borrower can meet the loan repayments. For an international buyer, proving this can be more complicated when income is earned outside the country where the property is located.
A lender may need evidence of salary, business income, investment income, existing debts, assets and tax obligations. Documents may need to be supplied in a particular format, translated or independently verified. Income received in another currency may also be assessed differently from local-currency income.
Self-employed buyers can face additional documentation requirements because lenders may need several years of accounts, tax returns or other evidence of sustainable earnings. Buyers whose income varies substantially from year to year may also be assessed differently from salaried employees.
The result is that two buyers with identical property budgets may have very different borrowing capacity depending on how their income is structured and documented.
Debt-to-Income and Serviceability Tests
Mortgage approval is not based solely on the value of the property. Banks also assess whether the borrower can continue making repayments if financial circumstances become less favourable.
Serviceability assessments may take account of income, existing debts, household commitments, the proposed mortgage payment and an assumed interest-rate level. Some banking systems also use formal debt-to-income restrictions that limit the amount of lending available to borrowers with high levels of debt relative to income.
New Zealand, for example, introduced debt-to-income restrictions for new residential lending in 2024 alongside its LVR framework. The Reserve Bank explains that these restrictions apply to both owner-occupiers and investors, with banks also continuing to apply their own lending criteria.
Australia provides another example of formal serviceability requirements. APRA confirmed in May 2026 that the mortgage serviceability buffer remained at three percentage points, meaning banks continue to assess borrowers against a higher repayment rate than the actual loan rate.
Interest Rates Are Only One Part of the Mortgage
Interest rate comparisons can be useful, but the lowest advertised rate does not necessarily produce the lowest overall financing cost. The structure of the mortgage can be equally important.
International buyers should examine whether the rate is fixed, variable or linked to another reference rate; how long a fixed period lasts; whether the loan can be repaid early; whether there are arrangement or administration fees; and whether the borrower is required to purchase additional insurance or banking services.
The repayment structure also matters. A mortgage may require principal and interest payments, while some investment loans or specialist financing arrangements may offer interest-only periods. The initial monthly payment can therefore provide an incomplete picture of the eventual cost of borrowing.
When comparing mortgages in different countries, the buyer should compare the complete financing structure rather than simply placing headline interest rates side by side.
Fixed and Variable Rate Mortgages
Fixed-rate borrowing provides greater certainty over the interest rate for the agreed period, while variable-rate borrowing can move as market conditions and lender pricing change. Some mortgages combine the two, allowing part of the loan to be fixed and another part to remain variable.
For an international buyer, the choice can have an additional dimension because the buyer may already be exposed to currency movements. A mortgage with a predictable interest rate does not eliminate the possibility that the buyer's home currency will move significantly against the currency of the property.
Loan structure should therefore be considered together with the buyer's income currency, asset base and intended holding period. A financing arrangement that looks straightforward when assessed solely in local currency may have a different risk profile when the buyer's wealth and income are held elsewhere.
Borrowing in the Property Currency
International buyers sometimes have a choice between borrowing in the currency of the property and borrowing in another currency. The decision can create important financial consequences.
When the mortgage and property income are denominated in the same currency, the financing and rental cash flow may be more closely aligned. When income, mortgage debt and property value are spread across different currencies, exchange-rate movements can alter the effective cost of servicing the loan.
This is particularly relevant to investors receiving rental income from an Asia Pacific property while earning their main income elsewhere. Currency movements can affect the amount that has to be transferred each month to meet the mortgage.
The Asia Pacific currency and money-transfer guide provides the wider context for international funds movement and exchange-rate exposure.
Foreign Currency Risk Can Continue After Completion
Currency risk does not end when the purchase completes. A buyer who funds a mortgage from overseas income remains exposed throughout the life of the loan unless the relevant cash flows are otherwise matched.
Consider an investor earning income in euros while making mortgage payments in an Asia Pacific currency. If the local currency strengthens against the euro, the amount of euros required to make the same local-currency payment increases. The reverse can also occur.
The same principle applies to rental income. If rent is received in the property's local currency but mortgage repayments are made in another currency, movements between the two can affect the effective return.
This is one reason why financing should be considered as part of the wider investment structure rather than as an isolated mortgage decision.
Financing an Investment Property
An investment property introduces another variable into the lender's assessment: expected rental income. Banks may consider rental income when assessing borrowing capacity, but the amount recognised and the conditions attached to it vary between lenders and markets.
Investors should not build a financing plan on the assumption that every dollar of projected rent will be treated as available income. Lenders may apply allowances for vacancy, management expenses or other costs, and some may treat short-term or seasonal rental income differently from a conventional long-term tenancy.
The type and location of the property can also influence the financing assessment. A standard apartment in an established urban market may present a different lending proposition from a remote holiday property, resort unit or development project.
Mortgage affordability should therefore be tested against realistic rental assumptions and the wider Asia Pacific rental market, rather than relying on an advertised rental yield.
Mortgages for New Build and Off-Plan Property
Financing a completed property is not necessarily the same as financing an off-plan purchase. New developments can involve staged payments, construction milestones and a period between signing the purchase contract and completion.
The buyer needs to understand when the mortgage becomes available and how the lender values the property at that point. A lender's willingness to finance a completed unit does not necessarily mean the same arrangement will apply to an unfinished development.
Construction delays can also change the timing of the buyer's financial commitments. If the buyer's personal circumstances or lending conditions change during a lengthy construction period, the eventual mortgage approval may need to be reassessed.
This makes financing an important part of researching off-plan property and off-plan development.
Financing Land and Development Property
Land and development projects can require a different financing approach from a conventional residential mortgage. A lender may assess planning status, permitted use, infrastructure, access, construction plans, development experience and the eventual exit strategy.
Development finance can also involve staged drawdowns rather than providing the entire loan at completion. The lender may release funds as construction or other agreed milestones are achieved.
For an international developer or investor, this can make the financing relationship more complex. Local professional advice may be necessary to understand planning, construction, security and tax requirements before the financial structure is finalised.
The Asia Pacific development land and development land investment research provides the appropriate wider context.
Using Finance From the Buyer's Home Country
Local mortgage finance is not the only possible source of funding. Some international buyers use cash held in their home country, borrow against another property, use private banking facilities or arrange financing through an international financial institution.
Borrowing against an existing property can allow the buyer to fund an overseas acquisition without taking a mortgage secured directly against the foreign property. This can simplify some aspects of the overseas purchase, but it also transfers the borrowing risk to the property or assets supporting the home-country loan.
Another consideration is currency. If the buyer borrows in one currency to purchase property in another, exchange-rate movements can affect the effective cost of the acquisition and the debt service.
The most suitable structure depends on the buyer's circumstances, the destination market and the availability of regulated finance. It should be assessed on its complete terms rather than simply by comparing nominal interest rates.
Cash Purchases Are Not Necessarily Simpler
A cash purchase removes mortgage interest and lender approval from the transaction, but an international cash buyer still needs to demonstrate the source of funds and comply with applicable banking and legal requirements.
Large international transfers can involve compliance checks, documentation and delays, particularly where funds move between several countries or financial institutions. The buyer should allow sufficient time for the transfer process rather than assuming that funds can be moved instantly when completion is due.
Cash also does not remove the need for due diligence. Ownership, title, planning, property condition and legal status still need to be established before funds are committed.
Mortgage Approval Should Precede Serious Property Selection
International buyers can reduce unnecessary risk by investigating their realistic financing capacity before becoming committed to a particular property. A preliminary assessment can establish whether the intended price range is compatible with the buyer's income, deposit and other financial commitments.
This is especially useful in markets where suitable properties vary widely in price. Establishing the financing range first can prevent a buyer from negotiating for a property that ultimately proves difficult to finance.
Pre-approval is not necessarily a guarantee that a particular purchase will receive final financing. The lender may still need to value the property, investigate the title and assess the specific transaction before releasing funds.
The distinction is important when dealing with a seller or developer who expects a firm completion timetable.
The Property Itself Is Part of the Lending Decision
A mortgage is secured against an asset, so the lender is assessing both the borrower and the property. Location, property type, condition, marketability and valuation can all influence the lender's willingness to provide finance.
A bank may be comfortable lending against a conventional residential property in a major city but apply different criteria to unusual properties, remote locations, leasehold interests, development land or properties with complicated ownership structures.
This is particularly relevant to international buyers attracted to specialist property such as beachfront homes, island property, resort developments or luxury real estate. The fact that a property is legally available for purchase does not necessarily mean it will be straightforward to finance.
The Asia Pacific property types structure can therefore be read alongside financing research when assessing a particular purchase.
Budget for the Full Financing Cost
The cost of borrowing includes more than interest. Buyers should investigate arrangement or application fees, valuation charges, legal expenses, mortgage registration, account fees, insurance requirements, early repayment charges and any other lender-specific costs.
These should be added to the broader acquisition budget rather than considered separately. The Asia Pacific property buying costs guide provides the wider framework for understanding the expenses surrounding completion.
For an investment property, financing costs should then be combined with ownership and rental expenses. A mortgage that appears affordable based on the monthly payment can look quite different once property management, maintenance, insurance, taxes and vacancy are included.
Think Beyond the Initial Interest Rate
Mortgage finance should be assessed over the period the buyer expects to hold the property. Interest-rate changes, refinancing conditions, currency movements, rental performance and changes in personal income can all affect the long-term cost of borrowing.
A buyer should also consider what happens if the property needs to be sold earlier than planned. Some loans have restrictions or costs associated with early repayment, while an overseas property may take time to sell and convert back into the buyer's home currency.
These considerations connect mortgage finance with the broader question of property exit and liquidity. Financing should remain manageable even if the eventual sale does not occur according to the original timetable.
A Practical Finance Checklist for International Buyers
Before proceeding with an Asia Pacific property purchase, establish whether local mortgage finance is available to the buyer's particular residency or citizenship status. Confirm the types of property that the lender will finance, the likely deposit requirement, the maximum realistic LVR and the documentation required to prove overseas income and assets.
Then compare the complete cost of borrowing, including interest, fees, valuation, legal and registration expenses and any insurance requirements. Establish whether the loan is fixed or variable, how repayments are calculated, whether early repayment is restricted and what happens when a fixed period ends.
Currency should be assessed at the same time. Identify the currency of the property, mortgage, income and expected rental receipts, and consider how exchange-rate movements could affect the repayment burden.
Finally, test the financing against less favourable circumstances. Consider higher interest rates, lower rental income, vacancy, currency movements, unexpected maintenance and a longer-than-expected ownership period. The purpose is not to predict these events, but to establish whether the financing structure remains workable if the original assumptions change.
Mortgage Finance Is Part of the Wider Property Decision
For an international buyer, mortgage finance should not be treated as a separate banking exercise. It interacts with property price, foreign ownership, taxation, location, property type, rental potential and the eventual sale of the asset.
The most useful financing structure is therefore one that fits the entire transaction. A buyer needs to know not only how much a bank may lend, but how much capital must be committed, how the debt will be serviced, which currency creates the liability, what happens if circumstances change and how the property fits the buyer's longer-term plans.
Asia Pacific offers a wide range of property markets, and mortgage systems are correspondingly diverse. The appropriate financing approach in a major established market may be unsuitable for an island resort, emerging city, development project or property in a jurisdiction with more limited access to foreign finance.
For that reason, international buyers should establish the financing structure early, verify current lending conditions with regulated lenders and qualified advisers, and then assess individual properties within the limits that have been realistically established.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

