
Asia Pacific Development Land Investment: Land, Projects and Opportunities
Asia Pacific development land investment covers the acquisition and repositioning of land for future residential, commercial, tourism, industrial and mixed-use development. For overseas investors, development land can provide access to property markets at an earlier stage of the development cycle, but it also introduces planning, financing, construction and market risks that do not apply in the same way to completed property.
The region contains a wide variety of land markets. Established cities such as Tokyo, Singapore, Sydney and Seoul have limited development land in many established districts, while expanding metropolitan areas in Southeast and South Asia can contain much larger development corridors. Coastal destinations, tourism markets, logistics hubs and new infrastructure zones create additional opportunities.
Development land should therefore be researched as a combination of geography, planning, economics and property demand. The value of a site depends not only on its current land price but also on what can legally and economically be developed on it.
Why Invest in Development Land in Asia Pacific?
Land can provide exposure to property development without requiring an investor to purchase a completed building. Where urban expansion, infrastructure investment or changing land use is creating new demand, development sites can become increasingly important to the property market.
Investors may acquire land for residential subdivisions, apartment developments, houses, hotels, resorts, offices, retail, logistics, industrial facilities or mixed-use projects. The appropriate strategy depends on the location, planning framework, infrastructure and expected demand.
Land can also be acquired as part of a longer development programme. In some markets, investors may assemble several parcels, obtain planning approvals and then sell the approved site to another developer rather than constructing the project themselves.
Development Land and Urban Growth
Urban expansion is one of the most important factors affecting development land. As cities grow, demand can extend beyond established central districts into suburban corridors and satellite towns.
Infrastructure can accelerate this process. New roads, railways, airports, industrial zones and business districts can improve accessibility and encourage developers to consider land that was previously less attractive.
However, an infrastructure announcement should not automatically be treated as evidence of future land value growth. Investors need to establish the status of the project, its expected completion, the surrounding planning framework and whether actual development is occurring along the proposed corridor.

|
PHILIPPINES |
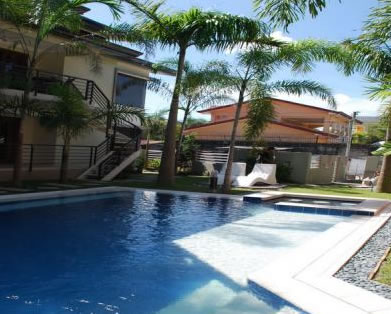
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Residential Development Land
Residential development is one of the largest potential uses for development land across Asia Pacific. Land may be suitable for detached housing, townhouses, apartments, retirement communities, student accommodation or larger master-planned developments.
The appropriate residential format depends on local housing demand and planning controls. A site close to a major employment centre may support higher-density apartments, while a peripheral location may be better suited to lower-density housing if infrastructure and transport access are sufficient.
Developers should also consider competing supply. A location with strong population growth can still experience weak development economics if large volumes of new housing are being delivered at the same time.
City Development Land
Development land in major cities can command substantial prices because of its proximity to employment, transport, retail and established communities. Sites in central areas may be suitable for high-density residential, offices, hotels or mixed-use projects, subject to local planning rules.
Urban redevelopment can also create opportunities where older buildings or underused sites are replaced with higher-value uses. Brownfield and regeneration projects may require more complex due diligence than undeveloped land but can provide access to established infrastructure and existing demand.
Tokyo, Sydney, Singapore, Seoul, Bangkok, Mumbai, Bengaluru and other major cities illustrate the importance of understanding development land at district level. The economics of a site can change dramatically within a relatively short distance.
Emerging Markets and Development Land
Emerging property markets can provide larger development opportunities where land availability, urbanisation and economic expansion are supporting new construction. Southeast Asia and South Asia contain numerous cities where industrial investment, technology, manufacturing, tourism and population growth are changing the geography of development.
India, Vietnam, Indonesia and the Philippines are examples of markets where developers are responding to expanding urban populations and infrastructure investment. Secondary cities can also provide opportunities where a strong economic driver is creating demand outside the principal metropolitan centre.
These markets require careful assessment of planning systems, infrastructure capacity, land title and future supply. Lower land prices alone do not make a development site attractive if the eventual project cannot be delivered or sold at viable prices.
Coastal and Tourism Development Land
Coastal land is an important component of Asia Pacific development investment. Beach resorts, hotels, villas, branded residences and mixed-use tourism projects can create substantial demand for well-located development sites.
Thailand, Indonesia, Vietnam, the Philippines, Sri Lanka, Australia, New Zealand and Pacific island markets all contain coastal locations where tourism influences development economics. Accessibility, airport connections, tourism infrastructure and the quality of the destination are often central to the investment case.
Coastal development also requires additional environmental and physical due diligence. Flooding, erosion, storm exposure, drainage, water availability and insurance can affect both development costs and long-term asset value.
Commercial Development Land
Commercial development land can support offices, retail, hotels, healthcare, education, logistics and other specialist uses. The suitability of a site depends heavily on its relationship with transport infrastructure and the businesses or consumers expected to occupy the completed development.
Current Asia Pacific investment research points to continued demand for high-quality offices in core locations, while logistics, living, data centres and hospitality remain important sectors. This creates opportunities for landowners and developers where suitable sites can support the required infrastructure and development economics.
Commercial land should be assessed according to the eventual occupier market. A site with excellent road access may be valuable for logistics but unsuitable for an office project, while a central urban parcel may have very different economics.
Industrial and Logistics Development Land
Industrial and logistics land has become increasingly important as supply chains, e-commerce, manufacturing and regional distribution networks expand across Asia Pacific.
Locations near ports, airports, highways, rail freight infrastructure and major population centres can attract logistics development. Manufacturing sites may require additional access to power, water, labour and transport networks.
Development costs can vary substantially depending on site preparation, infrastructure connections and building specifications. In some emerging markets, the availability and reliability of infrastructure can be more important than the headline cost of the land itself.
Data Centre Development Land
Data centres represent a specialised form of development land investment. Unlike conventional offices or warehouses, data centre projects depend heavily on electricity supply, grid capacity, fibre connectivity, cooling requirements and planning considerations.
Major Asia Pacific markets including Tokyo, Sydney, Singapore and other established technology hubs have attracted substantial interest from operators and investors. New development is also expanding into locations where land, power and connectivity can support large-scale facilities.
For overseas investors, data centre land should be treated as specialist infrastructure property rather than simply another commercial development opportunity. Power availability and development feasibility need to be established before the land's potential can be properly assessed.
Land Assembly and Development Sites
Some development opportunities involve assembling several adjoining parcels rather than acquiring a single large site. Land assembly can allow developers to create a project of sufficient scale for apartments, mixed-use development, retail or master-planned communities.
The process can be complex because ownership, title conditions, access rights and negotiations may differ between parcels. One unresolved parcel can affect the feasibility of the entire project.
Investors should therefore assess the probability and cost of assembly rather than valuing an incomplete site as though the entire proposed development area were already under control.
Planning and Development Rights
Planning permission is one of the most important determinants of development land value. The same parcel can have very different values depending on whether it is permitted for residential, commercial, industrial, tourism or mixed-use development.
Density, building height, site coverage, floor-area ratios, setbacks, parking requirements and environmental restrictions can all affect the amount of development that can be achieved.
Overseas investors should establish the current planning designation and development rights before relying on a proposed project. A seller's expectation that land can be rezoned is not equivalent to an approved planning entitlement.
Infrastructure and Development Land
Development land needs more than a favourable location. Roads, electricity, water, sewage, telecommunications and other infrastructure can determine whether a site is actually developable.
Infrastructure costs can become particularly significant on peripheral or newly urbanising land. Developers may need to contribute to roads, utilities or other public infrastructure before construction can begin.
Infrastructure capacity should therefore be incorporated into the development appraisal from the beginning. A large parcel with limited infrastructure may have less immediate development potential than a smaller site within an established urban network.
Development Land and Construction Costs
Construction costs are a major part of land development economics. Rising material, labour, financing and compliance costs can reduce the amount a developer can afford to pay for land even when final property prices remain strong.
Current Asia Pacific research continues to identify construction and land costs as important constraints on new development in several markets. High costs can reduce development pipelines and make redevelopment or acquisition of existing assets more attractive than building from scratch.
For this reason, land valuation should be based on a realistic development appraisal rather than simply comparing the site with other advertised parcels.
Development Land Valuation
Development land is commonly assessed by considering the value of the completed project and deducting the costs required to create it. These can include land acquisition, planning, professional fees, construction, infrastructure, financing, marketing, taxes and an allowance for development risk.
The remaining amount provides an indication of what the land may be worth to a developer. Changes in any major assumption can materially alter the result.
Overseas investors should therefore examine several development scenarios rather than relying on one projected sale price or construction budget. Conservative assumptions can reveal whether a project remains viable if costs increase or sales take longer than expected.
Foreign Ownership of Development Land
Foreign ownership is a critical issue for international land investors because the rules governing land can be considerably more restrictive than those governing completed buildings.
Some Asia Pacific countries allow foreign ownership of particular property types while restricting direct ownership of land. Others impose approval requirements, ownership limits, minimum investment levels or restrictions based on the intended use of the property.
Corporate structures may provide different legal options in some markets, but establishing a local company does not automatically remove land ownership restrictions. The proposed ownership structure should therefore be reviewed by local legal advisers before land is acquired.
Taxes and Costs on Development Land
Land acquisition can involve transfer taxes, stamp duties, registration charges, legal fees, planning costs and other transaction expenses. Development itself may create additional taxes and statutory charges.
Holding costs can also become significant if planning or construction takes longer than expected. Interest, land taxes, security, maintenance and professional fees can continue throughout the development period.
International investors should model the full cost from acquisition through to completion and sale rather than concentrating on the initial land purchase price.
Development Land and Joint Ventures
Joint ventures can provide a way for international investors to participate in development without undertaking every part of the project themselves. A local landowner may contribute the site while an investor or developer provides capital, expertise and project management.
Joint ventures can also combine international capital with local knowledge of planning, construction, sales and property management. However, the agreement needs to establish ownership, funding obligations, decision-making, development responsibilities, profit distribution and exit arrangements.
Local partnerships should be subjected to the same due diligence as the land itself, including verification of ownership, financial capacity, development experience and legal authority.
Development Land Risks
Development land carries several layers of risk. Planning approval may take longer than expected, construction costs may rise, financing may become more expensive and the completed property may sell more slowly than forecast.
Market conditions can also change between land acquisition and project completion. A residential market may weaken while a development is under construction, or competing projects may enter the market at the same time.
Environmental conditions, title problems, access restrictions, infrastructure deficiencies and construction delays can create additional risks. Overseas investors should allow sufficient time and financial capacity for problems that cannot be resolved immediately.
How to Research Development Land
Development land research should begin with the wider geography. Understand the city, region or destination, its economic drivers, population patterns, infrastructure and existing property market before examining individual sites.
The next stage is to establish what can actually be developed. Planning designation, permitted uses, density, height, access, utilities, environmental restrictions and development approvals should all be verified independently.
Only after these questions have been answered should the financial appraisal be prepared. Expected sale prices or rents should be tested against realistic land, construction, financing, tax, marketing and professional costs.
Development Land and Exit Strategies
A development land investment does not necessarily have to end with construction. Depending on the market, an investor may sell the site after obtaining planning permission, enter into a joint venture, sell part of a larger landholding or proceed to full development.
The appropriate exit depends on the value created during each stage. A site with planning approval may appeal to a developer that does not want to undertake the initial planning process, while a fully completed project may attract a wider range of buyers.
Understanding potential exits before purchasing the land can help determine the appropriate acquisition price and development strategy.
Asia Pacific Development Land Investment Outlook
Development land remains closely connected to the region's long-term urban and economic growth. Infrastructure investment, expanding cities, logistics networks, technology industries and changing housing requirements continue to create demand for new development in selected markets.
At the same time, development economics are becoming more demanding. Construction costs, financing costs, planning requirements and infrastructure expenses can reduce the amount developers are prepared to pay for land. Current regional research also indicates that constrained future supply in some mature markets could support existing property values while making new development more difficult.
This creates an important distinction between land that is merely available and land that is genuinely developable. For overseas investors, the quality of the planning position, infrastructure, location and eventual property demand is often more important than the size of the site.
Research Asia Pacific Development Property Markets
IPD provides geographical and property research for overseas buyers, investors and developers examining markets across Asia Pacific. Start with the Asia Pacific property markets section to understand the wider region before researching individual countries and cities.
Development land should also be considered alongside other investment strategies. Research into Asia Pacific property investment, city property investment, coastal property investment and tourism property investment can help place individual development opportunities within the wider market.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

