
Asia-Pacific vs North America Property
Asia-Pacific and North America are two of the largest and most diverse property regions considered by international buyers. Both contain major global cities, established residential markets, large investment sectors, extensive coastlines and rapidly changing development areas. Both also attract substantial cross-border capital.
Yet the property experience can be very different. Asia-Pacific stretches across a vast collection of countries and island groups, with major differences in ownership systems, urban density, infrastructure and development. North America combines the United States, Canada and Mexico, creating another broad regional market in which property structures, planning systems, currencies and buyer conditions differ substantially from one country to another.
For an overseas buyer, the useful comparison is therefore not simply Asia-Pacific versus North America. It is an opportunity to understand how the two regions organise cities, housing, investment, coastal property, development and international ownership before narrowing the research to a specific country and market.
Two Enormous Property Geographies
Geography has a particularly strong influence on this comparison. Asia-Pacific includes some of the world's most densely populated urban areas alongside tropical islands, mountain regions, agricultural areas, desert environments and sparsely populated territories.
North America has a similarly broad physical range. Major metropolitan areas extend from the Atlantic to the Pacific and from the Canadian border to Mexico, while large interior regions contain agricultural, rural, recreational and resource-based property markets.
Both regions therefore contain property markets where the relationship between city, suburb, coast and countryside is very different.
In Asia-Pacific, the distance between two countries may represent a dramatic change in property law, language, climate and development structure. In North America, crossing a national border from the United States into Canada or Mexico can likewise produce a substantial change in taxation, ownership, financing and transaction procedures.
The Asia-Pacific property geography guide provides the first regional layer before research moves into individual countries and cities.

|
PHILIPPINES |
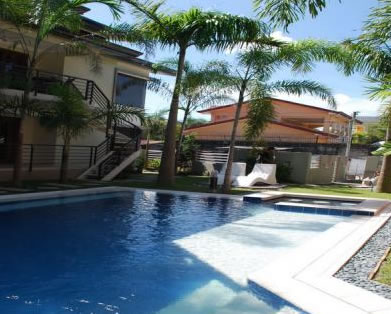
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Major Metropolitan Markets
Both regions contain some of the world's most influential metropolitan property markets.
Asia-Pacific includes Tokyo, Singapore, Sydney, Seoul, Hong Kong, Shanghai, Bangkok, Mumbai and many other major cities. Their property structures range from extremely dense urban environments to metropolitan regions containing extensive suburban and peripheral development.
North America includes New York, Los Angeles, Toronto, Vancouver, Miami, Mexico City, Chicago, Dallas, San Francisco and numerous other metropolitan systems. The physical size of these urban areas can be substantial, with property demand distributed across central districts, suburbs and separate municipalities.
This creates an important research principle for overseas buyers: the city name is only the beginning.
A buyer researching New York property needs to understand the difference between individual boroughs, neighbourhoods and property types. The same principle applies to Tokyo, Sydney, Toronto, Singapore or Mexico City. Employment, transport, housing supply, planning, schools, amenities and development can produce very different property conditions within the same metropolitan area.
Density, Houses and Apartments
One of the clearest differences between some Asian and North American markets is the balance between high-density and lower-density housing.
Major Asian cities frequently contain extensive apartment and condominium markets. High-density development can be closely associated with rail networks, commercial centres and concentrated employment. Apartments may therefore represent both a primary form of urban housing and an important investment category.
North American cities also have extensive apartment markets, but detached and semi-detached houses occupy a particularly important position in many metropolitan housing systems. Large suburban areas can extend considerable distances from central business districts.
This difference changes the way an overseas buyer evaluates location. In a dense Asian city, proximity to a railway station or established commercial district can be central to the property's usefulness. In a North American suburban market, road access, commuting patterns, schools, local services and the characteristics of the wider neighbourhood may carry greater significance.
Neither model applies universally. Asian cities contain extensive low-density housing, while North American cities increasingly include high-density urban redevelopment and condominium development.
Buyers can use the IPD Asia-Pacific apartments guide as one part of a wider property-type comparison.
The Suburban Question
Suburban property is particularly important when comparing North America with densely developed parts of Asia-Pacific.
Many North American metropolitan regions have been shaped by decades of suburban expansion. Residential neighbourhoods can be closely linked to highways, employment corridors, schools, shopping centres and municipal infrastructure.
Asia-Pacific contains suburban development on a massive scale as well, particularly around Australian, Japanese, Chinese and Southeast Asian cities. However, the relationship between suburban housing and public transport can be quite different from one market to another.
For an international buyer, this means that a property described simply as being "outside the city" provides very little useful information. The important questions concern travel times, infrastructure, local employment, population growth, services and the future development pattern of the area.
A suburban property should be evaluated as part of a metropolitan system rather than as an isolated house or building.
Coastal and Resort Property
Coastal property creates another strong connection between the two regions. Asia-Pacific contains extensive tropical and subtropical coastal markets, including major resort destinations in Southeast Asia, Australia, the Pacific Islands and South Asia.
North America has equally diverse coastal property, from Florida and California to the Caribbean-facing areas of Mexico, the Pacific coast, Atlantic coastal communities and resort destinations in Canada.
The reasons buyers choose these locations can overlap: retirement, second homes, lifestyle, tourism, rental income and long-term investment. But the demand structure can be quite different.
A coastal market supported primarily by permanent residents is not the same as a seasonal tourism market. A major resort can have a different rental cycle from an established coastal city, while an isolated waterfront community may have a much narrower resale market.
International buyers considering coastal property should therefore examine accessibility, seasonality, infrastructure, local employment, tourism, climate exposure and the future supply of competing properties.
IPD's resources covering coastal property and resort property provide useful background for this type of research.
Foreign Ownership Is Country Specific
Foreign ownership is one of the areas where a regional comparison can quickly become misleading.
North America does not have one unified foreign ownership system. The United States, Canada and Mexico each have their own legal and administrative structures, while individual states, provinces and municipalities can also affect property transactions.
Asia-Pacific is even more varied. Countries can differ substantially in their treatment of foreign ownership, land, condominiums, leasehold arrangements, approvals and residency-related property rights.
The distinction between buying a building and acquiring land beneath it can be particularly important in some Asian markets. In North America, the ownership structure may be more familiar to some overseas buyers, but tax, residency, financing and state or provincial rules can still create significant differences.
The correct process is therefore to identify the country first, then the property type and ownership structure. General statements about whether foreigners "can buy property" are rarely sufficient.
The Asia-Pacific foreign ownership guide can provide the regional starting point before country-specific legal research.
Investment Markets and International Capital
Asia-Pacific and North America both contain deep real estate investment markets. Current institutional research illustrates the scale of capital moving through both regions. In the first quarter of 2026, global direct real estate transactions increased year over year, with both Asia-Pacific and the Americas recording substantial growth in investment activity.
Within Asia-Pacific, major markets such as Tokyo, Sydney, Singapore and Seoul continue to feature prominently in cross-border investment research. North America contains an equally broad collection of established investment centres, together with rapidly growing metropolitan markets and specialist property sectors.
However, the institutional investment market is not identical to the private residential market. A global investment fund may acquire an office building, logistics portfolio, apartment community or data centre under conditions that have little connection with an individual overseas buyer purchasing a home.
For private buyers, international capital flows are therefore useful background information rather than a substitute for local property analysis.
Residential Investment Has Different Structures
Residential investment provides an interesting contrast between the regions.
In many Asian markets, condominiums and apartments can be purchased by individual investors and rented to local residents, expatriates or other international tenants. In North America, single-family rental property, multifamily housing and condominium investment can all form part of the residential investment landscape.
The difference is particularly relevant to an overseas investor considering a portfolio rather than a single home. The management requirements, financing, taxation and regulatory environment can vary substantially depending on whether the asset is an individual apartment, house, multifamily building or professionally managed residential development.
Current North American investment research continues to identify multifamily housing as an important sector, while Asia-Pacific research also shows strong institutional interest in living-sector property. These broad trends provide useful context, but they should not be interpreted as a guarantee of demand for an individual property.
The appropriate analysis remains property specific: tenant profile, achievable rent, vacancy, operating costs, management, financing, taxation and exit liquidity.
Rental Markets and Tenant Demand
Rental demand in both regions is influenced by employment, migration, education, household formation, population growth and housing supply. The balance between these factors varies considerably between cities.
Asian metropolitan rental markets can have significant demand from local professionals, expatriates, students and internationally mobile workers. Some cities also have strong short-term accommodation sectors associated with tourism.
North American rental markets can include long-term local households, students, migrants, professionals and corporate tenants. In some metropolitan areas, the rental sector is closely connected with high housing costs and the difficulty of entering the ownership market.
For an overseas investor, the most useful question is therefore not "What is the rental yield?" but "Who is the tenant, and why will that tenant remain in this location?"
Rental calculations should include vacancy, management, maintenance, insurance, taxes, service charges, financing and currency movements. A high advertised rent does not automatically create a strong investment case.
Development and Infrastructure
Development patterns provide another important contrast.
Several Asian markets are experiencing rapid urban expansion, new transport systems, large mixed-use developments and the creation of new commercial and residential districts. Infrastructure can sometimes transform the property geography of an entire metropolitan area.
North American development is often more closely associated with suburban expansion, urban redevelopment, infill, transit-oriented development and the growth of particular metropolitan corridors. Large master-planned communities also form an important part of the market in some locations.
In both regions, the buyer should distinguish between existing infrastructure and proposed infrastructure. A completed railway, highway or airport provides a different basis for analysis from a project that is still awaiting approval or funding.
The same principle applies to new residential communities. Buyers should examine the timing of infrastructure, schools, retail, utilities, transport and other services rather than relying entirely on the developer's future vision.
For those considering new-build property or off-plan property, development due diligence should be treated as a separate part of the purchase process.
Planning, Land and Development Potential
Planning systems can have a major influence on property value in both regions. The ability to add floors, subdivide land, change use or construct additional buildings depends on local planning and zoning rather than simply the physical characteristics of the property.
North American cities commonly divide land into detailed municipal zoning categories, although the exact system varies between jurisdictions. Asia-Pacific markets also contain sophisticated planning systems, but the structure and terminology differ between countries.
For an overseas buyer considering development land, redevelopment property or a building with expansion potential, professional planning and legal advice can therefore be more important than the property's current appearance.
A large site is not necessarily a development opportunity. The relevant questions include permitted use, density, access, infrastructure, environmental restrictions, title, planning approvals and development costs.
Climate and Physical Risk
Both regions contain a wide range of physical property risks.
Asia-Pacific includes areas exposed to earthquakes, cyclones, flooding, volcanic activity, extreme heat and other climate-related hazards. North America contains hurricane zones, wildfire areas, floodplains, earthquake regions, severe winter climates and areas exposed to extreme heat.
These risks should be assessed at property level rather than by applying a general regional label.
Construction standards, elevation, drainage, insurance availability, building maintenance, local infrastructure and the precise location of the property can all affect the practical exposure.
For an international buyer, insurance deserves particular attention because coverage, deductibles, exclusions and premiums can materially affect the cost of owning a property in a higher-risk location.
Currency and Financing
Currency is particularly important when comparing Asia-Pacific and North America because an overseas buyer may be moving between several major currencies.
A buyer may earn income in euros, pounds or Canadian dollars while purchasing in US dollars, Australian dollars, Japanese yen or another local currency. Rental income and eventual sale proceeds may then be received in a different currency again.
Currency movements can therefore affect the buyer's actual financial result even if the property itself performs as expected in local terms.
Financing also requires country-specific research. Mortgage availability for non-residents, required deposits, income verification, interest rates, currency requirements and local banking relationships can differ substantially.
International buyers should establish the financing structure before comparing properties on headline price alone.
The International Buyer Market
Both regions have substantial international buyer activity, but the sources of demand can be different.
In the United States, recent international residential transaction research continues to identify Canada, Mexico and China among important sources of foreign buyers. Florida, California, New York and other markets have long attracted international purchasers for a mixture of investment, lifestyle and residential reasons.
Asia-Pacific similarly receives international buyers from across Asia, Europe, North America and the Middle East. The reasons can include business, education, relocation, retirement, investment and second-home ownership.
The important point is that "international buyer" is not a single category. A family relocating permanently has a different objective from an investor purchasing a rental apartment, while a retirement buyer has different requirements from someone acquiring development land.
The buyer's purpose should therefore be established before comparing markets.
Liquidity and the Future Buyer
Exit planning is essential when buying internationally. A property that is easy to understand and finance for the original buyer may not necessarily be equally easy for the next buyer.
Large metropolitan markets can provide broad pools of potential purchasers, but individual neighbourhoods and property types can still have narrow demand. Specialist resort property, unusual homes, remote land and highly priced properties may depend more heavily on international demand.
The same principle applies in Asia-Pacific. An internationally marketed property may attract attention from buyers around the world, but the eventual resale market may still be relatively small.
Before purchasing, the buyer should ask who is likely to acquire the property later, whether local buyers participate in the market, how easily the property can be financed, and what transaction costs may affect resale.
IPD's exit and liquidity guide provides a framework for including this question in the original research.
A Practical Asia-Pacific and North America Comparison
The most useful comparison is a layered one.
Begin with the purpose of the purchase: residence, second home, retirement, rental investment, capital investment, development or land.
Then identify the geographical environment: major city, suburban market, regional centre, coastal community, resort, rural location or island.
Next examine the property type. Apartments, houses, villas, land, new developments and commercial property each involve different ownership and operating considerations.
Finally, investigate the country-specific legal and financial environment, including foreign ownership, taxation, financing, insurance, rental rules, professional requirements and resale.
This process prevents the regional comparison from becoming too broad to be useful.
From Regional Comparison to Individual Property
Asia-Pacific versus North America is ultimately a comparison between two enormous property environments rather than two individual markets. Both contain mature cities, emerging markets, coastal destinations, investment sectors and property opportunities for international buyers.
Recent market research also demonstrates the depth of cross-border investment connecting Asia-Pacific and the Americas. Institutional capital continues to move between the regions, while private residential buyers maintain their own distinct patterns of international demand.
For an overseas buyer, the most useful research path is therefore regional first, then country, city, district and property. The final assessment should bring together ownership, location, property condition, local demand, rental economics, financing, physical risk, currency exposure and resale.
IPD's Asia-Pacific property comparison resources can be used as the next step. The purpose of the regional comparison is not to treat Asia-Pacific or North America as a single market, but to identify the individual markets that justify deeper research.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|
