
Foreign Owner Taxes in Asia-Pacific – Property Tax Guide for Overseas Owners
Owning property in another country can create tax obligations that are different from those faced by a local resident. For an international property owner in Asia-Pacific, the relevant issues can include taxes on acquisition, recurring property taxes, rental income, capital gains, inheritance and the eventual sale or transfer of the property.
The important point is that being a foreign owner does not automatically produce one particular tax treatment. The position depends on the country where the property is located, the owner's tax residence, the type of property, how it is used, how it is owned and whether it generates income.
An overseas owner may therefore own a house or apartment in one Asia-Pacific country, remain tax resident in another country and receive rental income into a bank account somewhere else. Each part of that arrangement can create separate reporting or tax considerations.
Foreign Ownership and Tax Residence Are Different
Property ownership, immigration residence and tax residence should be treated as separate questions. Buying property in an Asia-Pacific country does not necessarily make the owner tax resident there, just as remaining a non-resident does not necessarily remove local tax obligations arising from the property.
Tax residence is generally determined under the rules of the relevant jurisdiction and can involve factors such as physical presence, permanent home, family and economic connections. The rules differ between countries.
An international owner should therefore establish three separate positions: whether they can legally own the property, what local taxes arise from owning or using it, and what must be reported in their country of tax residence.
The Main Taxes Affecting Foreign Property Owners
Foreign owner taxation is not one single tax. An overseas property owner may encounter acquisition and transfer taxes, annual property or land taxes, rental income tax, capital gains tax and other charges associated with ownership or disposal.
There can also be registration fees, municipal charges, withholding arrangements, development-related taxes and taxes associated with company ownership. Not all of these are technically property taxes, but all can affect the financial outcome of owning property abroad.
IPD's broader Asia-Pacific property tax guide provides an overview of the different tax categories that can affect an international property transaction.
Taxes When Foreigners Buy Property
The first tax consideration can arise when an overseas buyer acquires property. Depending on the country, the transaction may involve transfer tax, stamp duty, registration charges or other government fees.
The calculation can depend on the purchase price, assessed value, property type, location and status of the buyer. Some countries also apply different rules to particular categories of foreign purchaser or property.
These costs should be established before signing a contract because they form part of the real acquisition cost. A property that appears affordable from its advertised price can require substantially more capital once taxes and professional transaction costs are included.
IPD's Asia-Pacific transfer tax guide provides further context on purchase and transfer-related taxation.

|
PHILIPPINES |
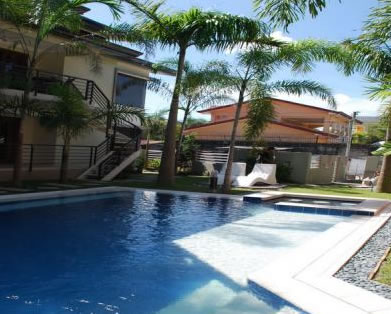
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Owning property in another country can create tax obligations that are different from those faced by a local resident. For an international property owner in Asia-Pacific, the relevant issues can include taxes on acquisition, recurring property taxes, rental income, capital gains, inheritance and the eventual sale or transfer of the property.
The important point is that being a foreign owner does not automatically produce one particular tax treatment. The position depends on the country where the property is located, the owner's tax residence, the type of property, how it is used, how it is owned and whether it generates income.
An overseas owner may therefore own a house or apartment in one Asia-Pacific country, remain tax resident in another country and receive rental income into a bank account somewhere else. Each part of that arrangement can create separate reporting or tax considerations.
Foreign Ownership and Tax Residence Are Different
Property ownership, immigration residence and tax residence should be treated as separate questions. Buying property in an Asia-Pacific country does not necessarily make the owner tax resident there, just as remaining a non-resident does not necessarily remove local tax obligations arising from the property.
Tax residence is generally determined under the rules of the relevant jurisdiction and can involve factors such as physical presence, permanent home, family and economic connections. The rules differ between countries.
An international owner should therefore establish three separate positions: whether they can legally own the property, what local taxes arise from owning or using it, and what must be reported in their country of tax residence.
The Main Taxes Affecting Foreign Property Owners
Foreign owner taxation is not one single tax. An overseas property owner may encounter acquisition and transfer taxes, annual property or land taxes, rental income tax, capital gains tax and other charges associated with ownership or disposal.
There can also be registration fees, municipal charges, withholding arrangements, development-related taxes and taxes associated with company ownership. Not all of these are technically property taxes, but all can affect the financial outcome of owning property abroad.
IPD's broader Asia-Pacific property tax guide provides an overview of the different tax categories that can affect an international property transaction.
Taxes When Foreigners Buy Property
The first tax consideration can arise when an overseas buyer acquires property. Depending on the country, the transaction may involve transfer tax, stamp duty, registration charges or other government fees.
The calculation can depend on the purchase price, assessed value, property type, location and status of the buyer. Some countries also apply different rules to particular categories of foreign purchaser or property.
These costs should be established before signing a contract because they form part of the real acquisition cost. A property that appears affordable from its advertised price can require substantially more capital once taxes and professional transaction costs are included.
IPD's Asia-Pacific transfer tax guide provides further context on purchase and transfer-related taxation.
Annual Property Taxes for Foreign Owners
Foreign owners may have continuing tax obligations after completing the purchase. These can include property taxes, land taxes, municipal charges or other recurring government assessments.
The fact that an owner lives overseas does not necessarily remove these obligations. A property can remain subject to local taxation even when the owner occupies it only for a few weeks each year or leaves it vacant.
The basis of taxation varies between markets. It may be linked to assessed property value, land value, annual value, property classification or another local measure. Buyers should establish the actual calculation method rather than assuming that a fixed percentage of the purchase price applies.
Foreign Owners and Rental Income
Rental income is one of the most important tax considerations for overseas property owners. Income generated by property is often connected with the country where the property is located, even if the owner lives abroad and the rent is paid into an overseas bank account.
The tax treatment can depend on whether the property is rented long term, operated as a holiday rental, used for commercial purposes or managed as part of a wider property business.
Owners should establish whether tax is calculated on gross rental income or on taxable income after permitted expenses. Depending on local rules, potentially relevant costs can include management, maintenance, insurance, service charges, financing and professional fees.
IPD's dedicated Asia-Pacific rental income tax guide provides further information on this area.
Foreign Owners and Property Management
An overseas owner frequently uses a local property manager or agent to handle tenants, maintenance, rent collection and other practical matters. This can make ownership easier but does not necessarily transfer the owner's tax responsibilities.
A local agent may have responsibilities for collecting rent, issuing documents, withholding amounts or assisting with local reporting. The owner should nevertheless understand what has been paid, what has been withheld and what remains the owner's responsibility.
Owners should retain statements showing gross rental income, management fees, repairs, taxes and amounts remitted to them. These records can be important for both local and home-country tax reporting.
Capital Gains Tax for Foreign Owners
The sale of an overseas property can create a tax liability on any gain. The rules differ substantially across Asia-Pacific and can depend on the owner's residence, the length of ownership, the property type and whether the property was held as a private asset or investment.
The taxable gain may involve the original acquisition cost, qualifying improvements, transaction expenses and sale proceeds. Currency conversion can also become relevant where the owner's home tax return uses a different currency from the property market.
A foreign owner should establish the potential tax position before purchasing rather than assuming that the entire increase in the property's market value represents an after-tax profit.
See IPD's Asia-Pacific capital gains tax guide for a wider discussion.
Selling Property as a Foreign Owner
Selling from overseas can create additional administrative and tax considerations. The owner may need to provide documentation proving ownership, settle outstanding property charges, deal with local tax authorities and arrange for the sale proceeds to be transferred internationally.
Some jurisdictions can also have withholding or tax-clearance procedures involving non-resident sellers. The exact requirements depend on the country and transaction.
Foreign owners should establish their likely net sale proceeds before accepting an offer. The calculation should account for taxes, agent commissions, legal fees, registration or transfer costs, mortgage repayment and currency conversion.
Foreign Owner Tax and Residency
Tax residence can affect how an overseas owner's property income or capital gains are treated. A person may remain tax resident in their home country while owning and renting property in another country, creating potential reporting obligations in both jurisdictions.
Property ownership should not be confused with immigration residency. Some countries offer residence programmes connected with investment, while others allow foreign property ownership without granting any automatic right to live in the country.
Where a property purchase is connected with relocation, the buyer should consider tax residence separately from immigration status. IPD's Asia-Pacific residency and property guide provides broader context.
Double Taxation and Overseas Property
A foreign owner may have to declare rental income or gains in their country of tax residence even when the property is already subject to tax in the country where it is located. This can create the possibility of taxation in more than one jurisdiction.
Double-taxation agreements can sometimes provide relief, but their application depends on the countries involved, the owner's tax residence and the type of income or gain. Relief may be provided through a credit, exemption or another mechanism.
International owners should not assume that paying tax locally automatically satisfies their home-country obligations. The two systems need to be considered together.
Foreign Property and Home-Country Reporting
Depending on the owner's country of tax residence, foreign property may create reporting requirements even when the property is not rented. Rental income, capital gains, foreign accounts or ownership through a company can introduce additional reporting considerations.
The requirements are particularly important for owners who move between countries during the period of ownership. A person's tax position can change even though the property itself remains unchanged.
International owners should retain purchase contracts, title documents, tax statements, rental records, improvement invoices, sale documentation and relevant currency records so that the property can be properly reported when required.
Foreign Owners and Property Ownership Structures
The way a property is held can affect its tax and reporting treatment. An individual owner, joint owners, company or other legal structure can have different obligations.
A company may be appropriate for certain commercial or development investments, but it should not be assumed that corporate ownership automatically reduces taxation. Company administration, accounting, annual filings, transfer taxes, inheritance considerations and taxation when profits are distributed can all affect the result.
International buyers should obtain legal and tax advice before establishing an ownership structure rather than selecting one solely on the basis of an advertised tax advantage.
Foreign Owner Taxes on Second Homes
Second-home ownership can create recurring tax obligations even when the property is used privately. A holiday apartment or villa may remain subject to local property taxes and other ownership charges throughout the year.
Because a second home may produce little or no income, these costs can be particularly important to the overall ownership budget. Insurance, maintenance, management and utilities should be considered alongside tax.
IPD's Asia-Pacific second-home guide provides a wider framework for evaluating overseas lifestyle property.
Foreign Owner Taxes on Vacant Property
Overseas owners sometimes leave property vacant between visits or while searching for tenants. Vacancy does not necessarily remove annual property taxes or other government charges.
Some jurisdictions may also have particular rules concerning vacant, unused or investment property. Owners should establish the treatment of an empty property rather than assuming that no occupation means no tax.
Vacant property also creates practical costs, including security, maintenance and insurance, which can materially increase the annual cost of ownership.
Foreign Owners and Property Inheritance
Inheritance can create a separate set of tax and administrative issues for international property owners. The property may be located in one country while the owner, beneficiaries and other assets are located elsewhere.
Inheritance or estate taxes may apply depending on the jurisdictions involved, while local succession rules can determine how ownership is transferred. A property held through a company or other structure can introduce additional considerations.
International owners planning to retain property as a family asset should consider succession arrangements before purchasing. IPD's inheritance and property guide provides a wider overview.
Foreign Owner Taxes and Different Property Types
Tax treatment can vary according to what is being owned. A private apartment, detached house, commercial property, development land, resort unit or mixed-use property may be subject to different rules.
The intended use can also matter. A home used personally may have a different tax profile from an apartment rented to tenants, a serviced residence operated commercially or land acquired for development.
Buyers should therefore identify the precise asset and intended use before attempting to estimate the tax burden.
Foreign Owners and Property Development
Foreign investors involved in development can encounter a more complex tax environment than an individual buying a home. Land acquisition, construction, sales, rental operations and company profits can each have separate tax consequences.
Development structures can also involve corporate and indirect taxes that do not apply in the same way to a private residential owner.
Anyone considering development should establish the tax position at the feasibility stage. A project that appears commercially attractive before tax can produce a very different return after development costs, financing, taxes and disposal expenses are included.
IPD's Asia-Pacific property development guide provides a wider framework for international development research.
Foreign Owner Taxes and Currency
Currency is an important consideration for an overseas property owner because income, expenses and tax may be denominated in different currencies. Rental income may be received in the local currency while the owner's tax return is prepared in another.
Exchange-rate movements can affect the value of rental income and the apparent capital gain when measured in the owner's home currency. They can also change the effective cost of recurring taxes and property expenses.
Owners should retain appropriate records of currency conversions where these are relevant to tax calculations and reporting.
Foreign Owner Taxes and Property Costs
Taxes should be included in a complete ownership budget rather than considered separately. The total cost of holding an overseas property can include annual property taxes, land charges, insurance, management, maintenance, service charges, utilities, financing and vacancy.
For rental property, the calculation should start with gross rent and then deduct legitimate operating costs and applicable taxes. For a personal second home, the calculation should focus on the annual cost of holding and maintaining the property without rental income.
IPD's Asia-Pacific ownership costs guide provides a broader framework for making this calculation.
Foreign Owner Taxes and Buying From Abroad
An overseas purchaser should investigate taxation before committing to a property rather than waiting until completion. The purchase contract, title documentation and local tax position should be reviewed as part of normal due diligence.
This is especially important where the buyer is unfamiliar with the country's legal system or language. A local lawyer or tax adviser can establish the applicable charges and explain which payments are the responsibility of the buyer, seller or another party.
IPD's buying property from abroad guide provides a wider framework for an international purchase.
Foreign Owner Taxes Are Country Specific
Asia-Pacific contains a wide range of tax systems and property markets. Australia, Japan, South Korea, China, Southeast Asian countries and Pacific island markets do not apply one common approach to foreign property owners.
Even within a country, the treatment can differ by property type, location, ownership structure, residency and intended use. A tax rule that applies to one city or category of property should not automatically be applied to another.
This is why regional research should be followed by country-level and property-level research before a transaction is completed.
Keeping Records as an Overseas Property Owner
Good records are particularly important when property is owned across national borders. Owners should retain the original purchase documents, title records, tax assessments, payment receipts, rental statements, management invoices, improvement costs and eventual sale documentation.
These records can help establish the acquisition cost, support legitimate deductions, demonstrate tax payments and calculate any gain when the property is sold.
They can also make it easier for professionals in different countries to coordinate the owner's tax affairs.
A Foreign Property Owner Tax Checklist
Before purchasing property in Asia-Pacific, an overseas buyer should establish the tax treatment of acquisition, annual ownership, rental income and eventual sale. The buyer should also check whether nationality, residency, property use, ownership structure or property value changes the calculation.
Where the property will be rented, the owner should establish how income is declared, what expenses may be deductible and whether local withholding or registration requirements apply. Where the property will be sold, potential capital gains, withholding, clearance and transfer requirements should be investigated before the transaction begins.
The owner should also determine what must be reported in the country of tax residence and whether a tax treaty or other mechanism may affect double taxation.
Professional Advice for Foreign Property Owners
International property taxation can become complicated because two or more legal and tax systems may apply to the same investment. General research can identify the issues, but final calculations should be based on the current rules applying to the specific property and owner.
A local property lawyer or tax adviser can explain the obligations in the country where the property is located, while an adviser in the owner's country of tax residence can address home-country reporting and taxation.
This is particularly important where the property is rented, held through a company, inherited, sold or connected with a relocation or residency programme.
Foreign Owner Tax Should Be Considered Before Buying
Foreign owner taxation is part of the wider economics of international property ownership. The purchase price alone does not reveal what an overseas property will cost to acquire, own, operate or eventually sell.
The strongest approach is to identify the property and ownership structure first, establish the local tax obligations, consider the owner's tax residence and then calculate the complete cost of the investment. This allows properties in different countries to be compared on a more realistic basis.
Asia-Pacific offers a broad range of opportunities for overseas buyers, from city apartments and coastal homes to retirement property, rental investments and development land. The tax position can differ substantially between them, making country-specific research essential before funds are committed.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

