
Asia-Pacific Property Taxes – Guide for International Buyers and Investors
Property taxation is an important part of buying, owning, renting and selling real estate in Asia-Pacific. For an international buyer, the tax position can be more complicated because the buyer may be dealing with a country where they are not resident, earning rental income across borders or eventually selling a property from overseas.
There is no single Asia-Pacific property tax system. Australia, New Zealand, Japan, Singapore, China, India, Southeast Asia and the Pacific island markets each have their own tax structures, definitions and administrative requirements. Rates and rules can also vary according to property type, ownership structure, residency, nationality, intended use and the transaction itself.
Tax should therefore be considered from the beginning of the property search rather than added to the calculation after a purchase price has been agreed. The complete cost of acquisition, ownership, rental operation and eventual disposal can be substantially different from the advertised property price.
Why Property Tax Matters to International Buyers
An overseas buyer may encounter taxes at several stages of the property lifecycle. There can be charges when the property is purchased, recurring taxes while it is owned, taxes on rental income if the property is let, and potential taxation when it is eventually sold.
Some markets also apply different treatment to foreign purchasers or non-residents. In other markets, the tax position may depend more heavily on the property type, ownership structure or purpose of the purchase.
IPD's wider Asia-Pacific foreign buyers guide explains why taxation needs to be considered alongside foreign ownership rules rather than as a separate issue.
Property Purchase Taxes
The acquisition of property can trigger taxes or government charges at the time of purchase. Depending on the country, these may include stamp duty, transfer tax, land transfer charges, registration fees or other transaction-related taxes.
The amount payable can sometimes depend on the purchase price, property type, location, buyer status or whether the property is residential or commercial. Some jurisdictions also have different treatment for new construction and established property.
For an international buyer, these costs should be calculated before making an offer. A property that appears affordable based on its asking price may require a significantly larger amount of capital once acquisition taxes and professional fees are included.
Taxes for Foreign Property Buyers
Foreign buyers can face tax rules that differ from those applying to domestic purchasers. Some countries apply additional taxes or surcharges to overseas buyers, while others use residency or ownership-status tests to determine the applicable rate.
Foreign buyers should not assume that a property advertised internationally will have the same tax treatment as a comparable purchase by a local resident. The relevant rules should be confirmed for the buyer's nationality, residency status, property type and intended use.
Tax treatment can also change. Buyers considering a long-term investment should use current local professional advice rather than relying on an old tax rate or an online property article that may no longer reflect the law.
Stamp Duty and Transfer Taxes
Stamp duty and transfer taxes are commonly associated with the acquisition or transfer of real estate. The terminology varies between countries, but the economic effect is similar: the buyer may have to pay a government charge in connection with transferring the property.
These taxes can represent a significant part of the initial transaction cost, particularly for higher-value properties. Some markets use progressive rates, while others have fixed or property-specific structures.
Buyers should establish whether the tax is paid by the buyer, seller or both parties, when it becomes payable and whether any exemptions or special provisions apply.
IPD's dedicated property transfer tax guide provides a more focused starting point for this part of the transaction.

|
PHILIPPINES |
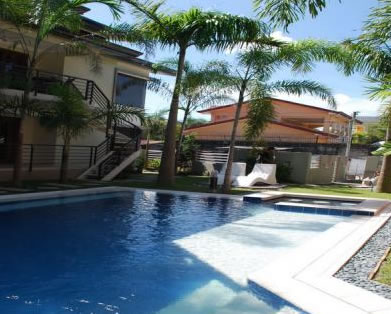
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Annual Property and Land Taxes
Buying property does not necessarily end the tax obligations. Some Asia-Pacific jurisdictions impose recurring property, land, municipal or local government charges on owners.
The basis of taxation can differ considerably. It may be related to the property's assessed value, land value, annual value, location, use or other local criteria. Some systems distinguish between residential and commercial property, while others provide different treatment for owner-occupied and investment property.
International owners should establish the recurring tax obligations before purchasing because these costs continue regardless of whether the property produces rental income.
The wider Asia-Pacific property tax guide covers recurring property taxation in more detail.
Tax on Property Rental Income
An international owner who rents out property may become liable for tax on rental income in the country where the property is located. The calculation may be based on gross rental income or, depending on the local system, income after allowable expenses.
Potential deductions and expenses can include property management, maintenance, insurance, service charges, interest or other costs, but these rules vary substantially between jurisdictions.
Rental income can also create reporting obligations in the owner's home country. A property owner should therefore consider both the local tax position and any tax obligations that arise from being resident elsewhere.
IPD's rental income tax guide provides a dedicated overview of the issues international landlords should investigate.
Capital Gains Tax on Property
The eventual sale of a property can create another layer of taxation. Some Asia-Pacific markets tax gains made on the disposal of real estate, although the calculation, rate and exemptions vary widely.
The taxable gain may involve the difference between the acquisition cost and sale price, adjusted for qualifying expenses or improvements. The length of ownership can also affect the treatment in some jurisdictions.
International owners should investigate potential capital gains taxation before buying rather than waiting until a sale is being negotiated. A property investment should be assessed using its potential after-tax outcome, not simply its expected sale price.
IPD's Asia-Pacific capital gains tax guide provides further context.
Taxes When Selling Property
The tax position on disposal can involve more than capital gains. There may also be transfer-related charges, withholding arrangements or reporting requirements depending on the country and the status of the seller.
This can be particularly relevant to non-resident owners. A seller who lives overseas may have additional documentation or tax obligations when disposing of local property.
Buyers should also remember that the costs of selling can affect the investment return. Agent commissions, legal fees, taxes and other disposal costs may reduce the amount ultimately received from the sale.
For the wider sales process, see IPD's guide to selling property in Asia-Pacific.
Inheritance and Property Ownership
Property can also create tax and administrative issues when an owner dies. The treatment of inherited real estate varies substantially across Asia-Pacific and can depend on the country where the property is located, the owner's residence and the relationship between the owner and beneficiaries.
Inheritance, estate and succession rules should therefore be considered when purchasing property intended to remain within a family for many years.
This is particularly important for international families because ownership may involve more than one country. A property located in one jurisdiction can form part of an estate whose other assets and beneficiaries are located elsewhere.
IPD's inheritance and property guide covers the issue in greater detail.
Tax and Property Ownership Structure
The way property is owned can affect its tax treatment. An individual, joint owners, company or other legal structure may face different obligations, and the appropriate structure can depend on the purpose of the purchase.
However, an ownership structure should not be selected simply because it appears to reduce tax. Legal, accounting, financing, inheritance and reporting consequences may all need to be considered.
International buyers should obtain independent legal and tax advice before establishing a company or other structure to hold property. The simplest structure is not necessarily the most appropriate, while a structure used for a particular investment strategy in one country may not produce the same result elsewhere.
Property Tax and Residency
Residency can be an important factor in determining how an individual's income and property transactions are taxed. A person may own property in one country while remaining tax resident in another, creating cross-border reporting and taxation issues.
Property ownership itself should also be distinguished from immigration residency. Purchasing property does not automatically provide the right to live in a country, and obtaining a residence permit does not necessarily determine every aspect of an individual's tax position.
Buyers planning to relocate should consider property taxation together with their intended residency arrangements. IPD's Asia-Pacific residency and property guide provides wider background on this relationship.
Tax and Rental Investment
Tax is particularly important when a property is being purchased as an investment. A rental yield calculated from the advertised annual rent does not necessarily represent the income available to the owner after expenses and taxation.
Investors should consider property taxes, rental income tax, management fees, maintenance, insurance, vacancy, service charges and financing costs when estimating the actual return.
The tax treatment of rental income can also differ depending on whether the property is rented long term, used as a holiday rental or operated as part of a larger commercial activity.
IPD's Asia-Pacific rental investment guide provides a wider framework for evaluating income-producing property.
Tax and New-Build Property
New-build and off-plan property can involve different transaction arrangements from established property. Depending on the jurisdiction, taxes may be connected with the purchase price, transfer of the completed property, land or other elements of the development.
International buyers should establish which taxes are included in the advertised price and which are additional. A developer's quoted price should not automatically be treated as the buyer's final acquisition cost.
This is particularly important where the purchase involves staged payments, construction periods or completion several years after the original contract.
Tax and Property Development
Property development can involve a considerably more complex tax environment than purchasing an existing home. Developers may encounter taxes or charges associated with land acquisition, construction, sales, commercial activity, rental income and eventual disposal.
The tax treatment can also depend on whether the developer is an individual, company or other entity and whether the project is residential, commercial, tourism or mixed-use.
International developers should obtain country-specific professional advice before acquiring land or committing to a development project. Tax assumptions made at the feasibility stage can materially affect development viability.
IPD's Asia-Pacific property development guide provides broader context for assessing development opportunities.
Tax and Property Transaction Costs
Taxes form only one part of the total cost of an international property transaction. Buyers may also pay legal fees, registration charges, valuation costs, inspection fees, agent commissions, financing expenses and currency-transfer costs.
These costs should be combined with taxes to establish the true acquisition price. Similarly, when estimating the eventual investment return, selling costs should be deducted from the expected sale proceeds.
IPD's Asia-Pacific property transaction costs guide provides a broader framework for calculating these expenses.
Tax and Property Ownership Costs
International owners should distinguish between the cost of buying a property and the cost of keeping it. Recurring taxes, insurance, maintenance, utilities, management and building or community charges can continue for many years.
This is particularly important for second homes and properties that are not occupied throughout the year. An owner may have continuing tax and maintenance obligations even when the property produces no income.
A realistic ownership budget should therefore estimate annual costs rather than focusing only on the initial purchase.
Currency and Property Taxes
Currency can add another layer of complexity to international property taxation. A buyer may earn income in one currency, purchase property in another and pay taxes or receive rental income in a third currency.
Exchange-rate movements can change the effective cost of taxes and other property expenses when they are converted into the buyer's home currency. This is especially relevant for investors who measure their returns in a currency different from the one used for the property.
Currency should therefore be considered alongside taxation, financing and rental income rather than treated solely as a property purchase issue.
Keeping Tax Records for an Overseas Property
International property ownership can require more careful record keeping than a domestic purchase. Owners should retain purchase documents, contracts, tax receipts, improvement costs, rental records, management expenses, financing information and sale documentation.
Good records can be important when calculating taxable gains, supporting deductions or demonstrating the original acquisition cost. They can also make it easier for accountants and tax advisers in different jurisdictions to understand the transaction.
Owners who manage property from abroad should establish how local tax filings and payments will be handled and whether a local professional should act on their behalf.
Tax Rules Differ Across Asia-Pacific
The most important point for an international buyer is that Asia-Pacific should not be treated as one tax jurisdiction. A tax assumption that applies to property in one country may be completely inappropriate in another.
Even within the same country, tax treatment can differ according to the location, property type, ownership structure, buyer status or intended use. Rules may also change as governments alter housing, investment, development or revenue policies.
Regional comparisons are therefore useful for identifying broad differences, but final tax calculations should always be made using the current rules applying to the specific property and buyer.
A Practical Property Tax Checklist
Before purchasing property in Asia-Pacific, an international buyer should establish the acquisition taxes and charges, recurring property taxes, treatment of rental income, potential taxation on sale, inheritance implications, foreign-owner rules, residency considerations and any reporting obligations in the buyer's home country.
The buyer should also calculate legal and professional costs, registration charges, insurance, management, maintenance and currency costs. Where the purchase is financed, interest and lending costs should be included in the overall investment calculation.
These figures should be established before committing to a property rather than after a contract has been signed.
Professional Tax Advice for International Property
Property taxation can become complicated when ownership crosses national borders. General research is useful for comparing markets, but it should not replace advice based on the buyer's individual circumstances and the specific property.
An international buyer may need local legal advice, a property tax adviser and an accountant familiar with cross-border taxation. The relevant professionals should be able to explain both the taxes arising in the country where the property is located and any reporting or taxation consequences in the buyer's home jurisdiction.
Tax Should Be Part of the Property Decision
Property tax can affect whether an investment is affordable, whether a rental property produces an acceptable return and how much capital is ultimately recovered when a property is sold. It can also affect the suitability of a country for a second home, retirement property or long-term relocation.
For international buyers, the correct question is therefore not simply how much a property costs to purchase. The more useful question is what the property will cost to acquire, own, operate and eventually dispose of after taxes and other transaction expenses are taken into account.
Asia-Pacific offers a wide range of property markets and ownership opportunities, but tax systems vary significantly across the region. Buyers who understand the tax structure before choosing a country and property are in a much stronger position to compare opportunities realistically and avoid unexpected costs.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

