
Cost of Living in Asia-Pacific – Property and Lifestyle Guide for International Buyers
The cost of living is an important part of researching property in Asia-Pacific, particularly for international buyers considering relocation, retirement, a second home or an extended stay. The region includes some of the world's most expensive cities alongside lower-cost emerging markets, smaller regional centres, resort destinations and Pacific island communities.
There is therefore no single cost of living for Asia-Pacific. Expenses can vary substantially between countries, cities and neighbourhoods, and the cost of housing can change the overall picture more than almost any other individual expense. A destination with relatively affordable everyday goods may have expensive property in its most desirable areas, while a higher-cost country can offer different housing options outside its largest cities.
For an overseas buyer, the useful comparison is not simply whether one country is cheaper than another. The objective is to understand what it will actually cost to live in the chosen location, how those costs relate to property ownership or renting, and whether the budget remains sustainable if circumstances or exchange rates change.
There Is No Single Asia-Pacific Cost of Living
Asia-Pacific covers a vast geographical area and contains very different economic environments. Major financial centres such as Singapore, Hong Kong, Tokyo and Sydney operate differently from regional cities, emerging urban markets, coastal communities and island destinations.
Even within one country, the difference between the capital or principal commercial centre and a smaller city can be substantial. Housing, transport, dining, education, healthcare and entertainment may all follow different price structures depending on the location.
International buyers should therefore avoid relying on a country-wide cost-of-living figure when deciding where to purchase property. The relevant comparison is usually much more specific: the cost of living in the particular city, district or community where the buyer intends to live.
Location also affects the balance between different expenses. A central apartment may cost more but reduce the need for a car and lengthy commuting. A larger home outside the city may be cheaper per square metre while creating additional transport costs and longer journeys to schools, hospitals and other services.
The Asia-Pacific property markets guide provides a broader framework for understanding these differences.
Housing Is Usually the Most Important Cost
For people considering relocation or extended residence, housing can have the greatest influence on the overall cost of living. Rent and property prices vary widely between countries and locations, but the advertised price is only part of the calculation.
Renters should consider deposits, advance rent, utilities, internet, parking, furnishings and any building or service charges. A furnished apartment may have a higher monthly rent but reduce the initial cost of establishing a home. A cheaper unfurnished property may require a significant expenditure on furniture and appliances.
Property owners need to consider the purchase price alongside legal fees, transaction taxes, registration charges, insurance, maintenance, property taxes and building or community fees. These costs can be particularly important for overseas owners who may also need professional property management.
Housing choices can also change the rest of the household budget. A centrally located apartment may cost more but provide access to public transport and reduce car ownership. A detached property may offer more space but involve higher maintenance, security and transport costs.
International buyers should therefore compare the total cost of the housing arrangement rather than looking only at rent per month or the purchase price. The Asia-Pacific property prices guide can be used alongside location-specific research.

|
PHILIPPINES |
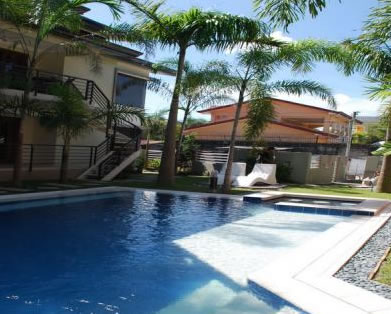
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


City Living Versus Regional and Coastal Locations
The choice between a major city and a smaller or more remote location can produce a significant difference in household expenses. Major cities generally provide extensive public transport, employment opportunities, healthcare, education, shopping and international connections, but these advantages can be reflected in property prices and rents.
Regional cities may offer larger homes or lower housing costs while retaining many of the services required for everyday living. However, access to specialist healthcare, international schools, major airports and particular professional services may be more limited.
Coastal and resort locations can provide attractive lifestyles and, in some markets, lower housing costs than major international cities. They can also have seasonal economies, limited public transport and fewer specialist services. Imported goods may cost more in island or remote locations because of transport and supply-chain costs.
For international retirees and second-home owners, the appeal of a lower-cost coastal destination needs to be balanced against the cost and frequency of travelling to and from the property. A cheaper home may not produce a lower overall budget if reaching it requires several flights or expensive transfers.
Healthcare access should receive particular attention when comparing remote and urban locations. The cost of a medical consultation is only one consideration; the distance to a hospital, availability of specialists and need for private insurance can have a greater effect on long-term financial planning.
Food, Groceries and Everyday Spending
Food costs can vary considerably across Asia-Pacific, but international residents should distinguish between locally produced goods and products imported from their home country. A destination may have relatively inexpensive local food while imported brands, specialist foods and familiar household products cost substantially more.
Local markets and locally produced food may offer different pricing from supermarkets serving international residents. Dining out also varies by location and type of establishment. A major financial centre may offer a very wide range of restaurants but at prices comparable with other global cities, while smaller destinations can provide lower-cost local options.
Households should consider their normal habits rather than an assumed average. Someone comfortable eating predominantly local food may have a very different monthly budget from a family that regularly buys imported products, eats at international restaurants or relies on specialist dietary products.
The same principle applies to household goods and services. Imported appliances, electronics, furnishings and specialist repairs may be more expensive than locally available alternatives. Buyers setting up a new home should include these costs when calculating the financial impact of relocation.
Transport and the Cost of Getting Around
Transport can alter the cost-of-living calculation significantly because housing location determines how often and how far a household needs to travel. Major Asian cities may have extensive public transport networks, allowing residents to live without owning a car. Other locations may require private transport for everyday activities.
International buyers should consider the distance between their home and the places they expect to visit regularly. These may include workplaces, schools, hospitals, supermarkets, airports and leisure facilities. A lower-cost property in a remote location may create higher transport expenses over time.
Car ownership introduces costs beyond the vehicle itself, including fuel, insurance, registration, servicing, parking and repairs. In some countries, driving conditions and road infrastructure may also influence whether an overseas resident is comfortable relying on a private vehicle.
Island and remote markets require additional consideration. Ferry fares, domestic flights and other connections can become recurring expenses for residents who need to travel to larger population centres. Weather-related disruptions can also affect the reliability of transport.
For buyers considering a property primarily as a second home, access to airports can be more important than it first appears. Regular international travel can become one of the largest recurring lifestyle expenses associated with maintaining a home abroad.
Healthcare and Insurance Costs
Healthcare should be included in any serious cost-of-living assessment, particularly for retirees and households planning to remain abroad for many years. The availability, cost and structure of healthcare services differ substantially across Asia-Pacific.
Some destinations have extensive public healthcare systems, while others have strong private healthcare markets or a combination of public and private provision. International residents may have different eligibility from citizens, and access can depend on residency status, employment or insurance arrangements.
Private healthcare can provide greater choice or faster access in some locations, but insurance premiums and coverage conditions need to be considered. Policies can vary according to age, destination, treatment, exclusions and pre-existing conditions.
Location within a country also matters. A major city may offer several hospitals and specialist providers, while a rural or island community may have only basic medical facilities. If specialist treatment requires travel, the associated transport and accommodation costs should be included in the longer-term budget.
The Asia-Pacific healthcare and property guide provides further context for comparing residential locations.
Education and Family Living Costs
Families moving to Asia-Pacific can face substantially different costs depending on the education system and location they choose. Local schools may have lower direct costs but involve language or curriculum considerations, while international schools can represent a significant addition to the household budget.
International schools are often concentrated in major cities and established expatriate communities. Families should research admissions requirements, school fees, transport, uniforms, activities and waiting lists before choosing a property.
The location of the school can also affect housing costs. Families may pay a premium to live near an international school in order to reduce daily travel. Alternatively, choosing a less expensive property farther away can increase transport time and costs.
Childcare, university education and other family-related expenses should also be considered when comparing countries. A location that appears inexpensive for a single adult may have a very different cost structure for a family with children.
Utilities, Internet and Household Services
Utility costs can vary according to climate, property type and household habits. Air conditioning can become a significant expense in hot and humid locations, while larger houses may require more electricity and water than compact apartments.
Buyers should ask about typical electricity and water consumption for comparable properties rather than assuming that a low-cost destination automatically means low utility bills. Pool maintenance, gardens, security systems and other property features can add recurring expenses.
Reliable internet can also be important for international residents, particularly people working remotely or maintaining businesses in another country. Urban areas may offer extensive connectivity, while rural and island locations can have fewer providers or higher costs.
Household services such as cleaning, gardening, maintenance and domestic assistance may be relatively affordable in some markets but should still be treated as recurring costs. For an expatriate owner, professional property management may be necessary when the home is vacant or the owner is travelling.
The guide to managing property from abroad explains some of the additional responsibilities faced by overseas owners.
Taxes and the Cost of Property Ownership
Cost-of-living comparisons should include the taxes and charges associated with owning or renting property. These can include property taxes, municipal charges, transfer taxes, registration costs, rental income taxes and taxes that may apply when a property is sold.
The rules vary considerably between countries and may also depend on nationality, residency, property type and how the property is used. A foreign owner may be subject to different charges from a local resident, while an individual who becomes tax resident may have additional reporting or taxation obligations.
Tax residency should not be confused with immigration residency. A visa or residence permit does not by itself determine how all income and assets will be taxed. Someone moving abroad may continue to have tax obligations in their original country as well as obligations in the new destination.
International buyers should therefore calculate property taxes and recurring ownership costs before deciding that one market is cheaper than another. A lower purchase price can be offset by higher transaction charges, ownership taxes or management expenses.
See the Asia-Pacific property tax guide, foreign owner tax guide and property ownership costs guide for further research.
Currency and International Income
For an overseas resident, the local cost of living is only part of the financial calculation. Income, pensions, investments or savings may be held in another currency, creating exchange-rate exposure.
A destination can become more or less expensive in the buyer's home currency without local prices changing. This can affect rent, mortgage payments, utilities, school fees, healthcare, travel and property maintenance.
Currency risk is particularly important when purchasing property because the initial transfer may be large and the investment may be held for many years. The exchange rate at the time of eventual sale can also affect the amount of money received after converting the proceeds back into the buyer's home currency.
Buyers should therefore avoid building a relocation budget around a single exchange rate. A margin for currency movement can make the financial plan more resilient, particularly for retirees or households with fixed foreign-currency income.
The Asia-Pacific currency risk guide provides further background on exchange-rate exposure.
Cost of Living Versus Cost of Property
A common mistake in international property research is assuming that a lower general cost of living automatically means cheaper property or better property value. The two measures are related but can behave very differently.
A country may have relatively low everyday costs while its most desirable coastal or urban property markets are expensive because of limited land, tourism demand or international interest. Conversely, a country with high wages and living costs may have regional property markets that are considerably less expensive than its principal city.
The relationship between housing costs and local incomes also matters. A property can appear inexpensive to an overseas buyer while being expensive relative to local purchasing power. This can affect the depth of the resale and rental market.
For investors, rental demand should be assessed alongside the cost of living. A location with low living costs may not necessarily produce strong rents or reliable occupancy. For personal-use buyers, the priority may instead be access to services, lifestyle and long-term affordability.
Property prices should therefore be researched alongside the Asia-Pacific rental market and relevant local market information rather than treated as a simple cost-of-living indicator.
Living Costs for Retirees and Second-Home Owners
Retirees and second-home owners often have different spending patterns from working expatriates. They may have less need to live close to a business district but greater requirements for healthcare, accessibility, reliable transport and a comfortable home environment.
A retiree receiving a pension from another country should consider how fixed income will respond to inflation and currency movements. Healthcare insurance, regular travel to visit family and the cost of maintaining a property during periods away can become significant long-term expenses.
Second-home owners have a different calculation because they may continue paying for accommodation in their home country while also maintaining property abroad. Travel between the two countries can become a major part of the total cost, particularly when the property is remote.
For both groups, property management may be necessary when the home is unoccupied. Insurance requirements can also be different for properties that remain empty for extended periods.
The Asia-Pacific retirement property guide and second-home guide provide additional context.
How to Compare the Cost of Living Between Locations
A useful international comparison starts by creating a realistic household budget rather than relying on a single online cost-of-living ranking. The budget should reflect the buyer's actual lifestyle, household size and property plans.
- Housing or rent, including building and community charges.
- Utilities, internet and communications.
- Groceries and normal dining expenses.
- Transport, including public transport or vehicle ownership.
- Healthcare, insurance and regular medical costs.
- Education and childcare where relevant.
- Property taxes, insurance and maintenance.
- International travel and trips to visit family.
- Property management during periods abroad.
- Taxes and financial obligations in more than one country where applicable.
- Currency-transfer costs and a contingency for exchange-rate movements.
Once these costs have been estimated, locations can be compared according to the buyer's actual circumstances. This is more useful than asking whether one country is simply “cheap” or “expensive”.
Researching Cost of Living Before Buying Property
The cost of living is an essential part of international property research because the purchase itself is only one element of the financial commitment. A property that fits the purchase budget may still be unsuitable if the surrounding cost of living, transport, healthcare, taxes or ongoing maintenance cannot be comfortably supported.
International buyers should first compare countries and locations, then investigate housing costs and the services required for their particular lifestyle. The next step is to establish the legal and tax position, calculate the full cost of ownership or renting, and consider currency and future changes in personal circumstances.
Asia-Pacific offers a wide range of potential destinations, but the best choice depends on the relationship between property, location and lifestyle rather than a simple cost ranking. International Property Directory provides a starting point for this research through its Asia-Pacific property directory, country markets and specialist guides covering property, buying, renting, residency, taxes and risk.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

