
Asia Pacific City Property Investment: Markets, Opportunities and Research
Asia Pacific city property investment covers a diverse group of urban markets ranging from established financial centres and global capitals to rapidly expanding regional cities. For overseas investors, the attraction is not simply the size of a city. Population growth, employment, infrastructure, business activity, tourism, housing supply and the structure of local property ownership can all influence the investment case.
Tokyo, Singapore, Sydney, Seoul, Hong Kong, Shanghai, Shenzhen, Mumbai, Bangkok, Jakarta, Ho Chi Minh City and other major urban centres operate within very different property systems. Some offer mature rental markets and established investment infrastructure, while others are being reshaped by urbanisation, new transport networks, manufacturing investment and expanding middle-class demand.
City property investment therefore requires more than comparing headline prices or rental yields. International investors need to understand how a city is organised, where employment is concentrated, which districts are expanding, what property types are in demand and how foreign ownership and taxation affect the transaction.
Why Invest in Asia Pacific Cities?
Major cities concentrate many of the economic activities that support property demand. Employment, education, healthcare, transport, technology, finance, tourism and business services tend to cluster in metropolitan areas, creating multiple sources of demand for residential, commercial and mixed-use property.
Urban property markets can also provide greater depth than smaller locations. A large city may contain central business districts, established residential neighbourhoods, emerging suburbs, industrial corridors, university districts, tourism areas and new development zones. These submarkets can behave very differently within the same metropolitan area.
For overseas investors, this creates the opportunity to research a city at district level rather than treating the entire metropolitan market as a single investment proposition.
Major City Property Markets in Asia Pacific
The region contains some of the world's most established international property markets alongside cities experiencing rapid structural change. Tokyo, Singapore, Sydney and Seoul have mature investment markets and substantial institutional participation. Hong Kong remains an important financial centre, while major Chinese cities such as Shanghai and Shenzhen operate within a different policy and ownership environment.
India provides another distinct group of major urban markets, including Mumbai, Delhi, Bengaluru and Hyderabad, where technology, services and business expansion influence property demand. Southeast Asian cities such as Bangkok, Jakarta, Kuala Lumpur, Manila, Ho Chi Minh City and Hanoi combine expanding urban populations with infrastructure and economic development.
City selection should therefore begin with the economic role of the location rather than property prices alone. IPD's Asia Pacific property markets section provides the wider geographical context before individual city markets are examined.

|
PHILIPPINES |
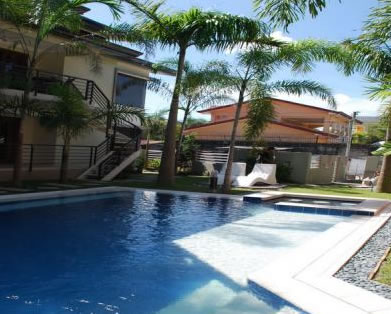
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Residential City Property Investment
Residential property is one of the most accessible ways to gain exposure to an urban market, but residential investment can mean very different things from one city to another. Apartments may dominate central districts, while detached houses and townhouses become more important toward metropolitan edges.
Demand can come from owner occupiers, local renters, expatriates, students, business travellers and international residents. The balance between these groups affects the type of property that may be suitable for rental investment.
Location within the city is particularly important. Properties near employment centres, universities, transport interchanges, established retail districts and major amenities may have a different rental profile from properties in newly developing outer districts. Investors should research the neighbourhood rather than relying on city-wide averages.
Apartments and Urban Living
Apartment investment is particularly relevant in high-density Asian cities where land availability, transport networks and population concentration support vertical development. New apartment projects may be concentrated around transport nodes, business districts and expanding residential corridors.
The investment characteristics of an apartment depend on factors including building age, tenure, management, location, floor area, parking, amenities and competing supply. A newly completed development may also face a different rental market from an established building in a mature neighbourhood.
Overseas investors should also distinguish between purchasing an individual apartment and investing through larger residential or institutional structures. The legal rights, financing arrangements and operating responsibilities can be substantially different.
Commercial Property in Major Cities
City investment extends well beyond residential property. Offices, retail property, logistics facilities, hotels, student accommodation, serviced apartments, healthcare property and other specialised assets are important components of metropolitan real estate markets.
Office markets are particularly sensitive to employment growth, corporate expansion, commuting patterns and the quality of buildings available. In 2026, regional investment research has highlighted renewed interest in high-quality offices in supply-constrained core locations, while investors continue to examine logistics, living, data centres and hospitality as alternative urban sectors.
Retail property is similarly dependent on location. Prime shopping districts can benefit from tourism and affluent consumers, while neighbourhood retail may depend more heavily on local population growth and everyday demand.
City Property and Infrastructure Investment
Infrastructure can change the geography of a property market. New metro lines, railway stations, airports, highways, bridges and other transport projects can alter commuting patterns and make previously peripheral locations more accessible.
However, infrastructure announcements should not automatically be treated as evidence of future property performance. Investors need to establish whether a project is funded, under construction or merely proposed, and then examine what development is actually occurring around the infrastructure.
Transport investment can also create competing effects. A new railway may improve accessibility and support development, while increased construction around a station can introduce substantial new property supply. Understanding both sides is essential when researching an urban investment area.
Emerging City Investment Markets
Some of the most interesting city investment opportunities may occur outside the established financial centres. Rapidly developing cities can experience population growth, industrial investment, expanding infrastructure and rising demand for housing and commercial space.
Vietnam, Indonesia, the Philippines and India contain numerous metropolitan markets where economic development is creating new property demand. Secondary cities can also attract investment when manufacturing, technology, education, tourism or transport infrastructure creates a new economic base.
These markets require particularly careful research because development can move quickly. New supply, planning changes and infrastructure projects can alter the balance between established and emerging districts within a relatively short period.
City Property Investment and Rental Demand
Rental demand is one of the key indicators for investors considering urban property. A city with a large population does not automatically provide strong rental conditions. The important question is where tenants are located and what type of accommodation they require.
Employment centres can support professional rental demand, universities can create student accommodation markets, while tourism districts may support short-term accommodation where local regulations permit it. Areas undergoing redevelopment may initially have limited rental infrastructure but develop new demand as employment and services arrive.
Investors should examine vacancy, competing supply, tenant profiles, lease structures, operating costs and achievable rents rather than relying solely on advertised rental figures.
Hotels and Tourism Cities
Tourism creates another layer of urban property demand. Gateway cities such as Tokyo, Singapore, Bangkok, Seoul, Sydney and other major destinations can combine business travel, leisure tourism, events and international transport connections.
Hotel and serviced accommodation investment is more operationally intensive than conventional residential property. Revenue depends on occupancy, room rates, seasonality, competition, management and tourism flows. Hotel development also requires consideration of construction costs, planning requirements and the availability of suitable sites.
For overseas investors, tourism should therefore be considered as part of the wider city economy rather than as a substitute for property-market research.
Development Opportunities in Asian Cities
Urban development can provide opportunities across residential, commercial, mixed-use, hospitality and specialised property sectors. Developers and investors may target redevelopment sites within established districts or larger projects on the expanding metropolitan edge.
Development economics depend on land costs, construction costs, financing, planning permissions, infrastructure requirements and achievable sale or rental values. These variables can differ considerably even between neighbouring districts.
High construction and labour costs are an important consideration across parts of Asia Pacific, while constrained supply in established locations can create different investment conditions from rapidly expanding peripheral markets. Understanding the relationship between land availability and future supply is therefore central to city property research.
Foreign Ownership of City Property
Foreign ownership rules vary substantially across Asia Pacific. Some markets permit relatively broad foreign ownership of certain property types, while others impose restrictions on land ownership, residential purchases, tenure, location or the purpose for which property can be acquired.
Rules can also distinguish between residential and commercial property and between individuals, companies and institutional investors. Local approval requirements, reporting obligations and restrictions on land ownership may apply even where a particular type of building can be purchased.
Before selecting a city, overseas investors should establish the applicable Asia Pacific property investment framework and then research the specific foreign ownership rules of the country and city concerned.
Taxes and Transaction Costs
City property investment should be assessed on the basis of total acquisition and ownership costs rather than the purchase price alone. Depending on the market, these can include transfer taxes, stamp duties, registration charges, legal fees, agency costs, financing costs and property taxes.
Rental property can introduce additional tax considerations, while selling may create capital gains or other disposal liabilities. Non-resident owners may also have different reporting or taxation requirements from domestic owners.
Because tax systems and property regulations change, overseas buyers should obtain current professional advice before completing a transaction. IPD's country research can provide the geographical starting point, but the transaction itself should be checked against the current rules applying to the property.
How to Compare City Property Markets
Comparing cities requires a consistent framework. Purchase prices and rental yields are useful starting points, but they should be considered alongside economic activity, population trends, employment, infrastructure, supply, liquidity and ownership rules.
An international investor might compare cities using questions such as: Is the population expanding? What industries support employment? Where are new infrastructure projects concentrated? Is residential supply increasing or constrained? Which districts attract tenants? How easily can an overseas owner acquire the property? What are the costs of ownership and eventual sale?
This approach avoids comparing cities simply because their property prices appear similar. A lower purchase price can reflect different levels of demand, liquidity, infrastructure or legal accessibility.
City Property Market Data
Reliable data is particularly important when researching urban investment. Useful information can include transaction prices, rental values, construction activity, vacancy, development approvals, sales volumes, building completions and infrastructure investment.
Official statistics can provide a useful foundation, while professional property research can add information about individual sectors and districts. Data should always be checked for its geographical coverage, measurement method and reporting period.
City-wide averages can also conceal substantial differences between neighbourhoods. Where possible, overseas investors should move from national data to metropolitan data and then to individual districts or property submarkets.
Risks of City Property Investment
Urban property investment carries risks that differ between cities. Interest rates can affect financing and valuations, while economic weakness can reduce employment and rental demand. New development can increase competition, and changes in planning policy can affect individual projects or districts.
Currency movements are particularly important for overseas investors. A property can perform satisfactorily in its local currency while the investor's return is affected by exchange-rate movements.
Climate and environmental risks also deserve greater attention. Flooding, extreme heat, coastal exposure and other physical risks can influence insurance, infrastructure resilience and long-term property costs. These issues can be particularly relevant when comparing dense coastal cities with inland urban markets.
Researching a City Before Investing
The most useful city property research begins with geography. Identify the city's economic role, major employment centres, transport structure and principal residential districts before looking at individual properties.
The next step is to examine the property market itself: prices, rents, supply, development activity, property types and investment demand. This should then be followed by research into foreign ownership, taxation, transaction procedures and financing.
For overseas buyers, the final stage is property-level due diligence. The building, title, planning status, ownership structure, lease arrangements, physical condition and expected operating costs should all be independently checked before committing funds.
Asia Pacific City Property Investment Outlook
Asia Pacific's major cities are likely to remain central to regional property investment because they concentrate employment, infrastructure, capital and population. Current 2026 market research points to stronger investment activity across much of the region, while also showing that performance varies considerably between cities and property sectors.
The investment landscape is becoming increasingly selective. Established cities with limited supply may offer different conditions from rapidly expanding metropolitan areas, while offices, living, logistics, hospitality and specialised property each respond to different economic drivers.
For overseas investors, the most useful approach is therefore to treat city property investment as a research process rather than a search for a single regional market. Understanding the city, its districts, its property types, its economic drivers and its legal framework provides a stronger foundation for evaluating individual opportunities.
Research Asia Pacific Property Investment Markets
IPD brings together geographical and property research for overseas buyers, sellers and investors examining markets across the region. Use the Asia Pacific property market section to move from regional research into individual countries, cities and property sectors.
For investors comparing different approaches, the wider Asia Pacific property investment section provides additional research on emerging markets, tourism property, coastal markets and other investment themes.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

