
Compare City Property Markets in Asia-Pacific – Guide for International Buyers
Asia-Pacific contains some of the world's largest and most diverse city property markets. Tokyo, Singapore, Sydney, Seoul, Hong Kong, Shanghai, Mumbai, Bangkok, Jakarta, Manila and Ho Chi Minh City all have substantial urban property sectors, but they cannot be compared simply by looking at prices or rental yields.
For an international buyer or investor, a city is often a more useful unit of comparison than an entire country. Employment, population, infrastructure, business activity, tourism, housing supply and international demand are concentrated differently within each country. A major capital can therefore have very different property conditions from a secondary city only a few hundred kilometres away.
The Asia-Pacific property market comparison provides the wider framework. This guide focuses specifically on comparing cities and understanding the factors that make one urban property market different from another.
Why Compare Cities Rather Than Countries?
National property statistics can conceal major differences between cities. A country may contain an expensive financial centre, a lower-cost regional city, a tourism destination and rapidly developing secondary markets, all operating under the same national legal system but with very different demand and supply conditions.
Property demand is usually connected to specific economic and geographical centres. Employment, universities, hospitals, transport, business districts, shopping, tourism and infrastructure tend to concentrate in particular cities and districts.
For an overseas buyer, city-level research therefore helps answer a more practical question: where within the country does the property market actually operate, and what supports demand in that location?
Major City Property Markets in Asia-Pacific
Asia-Pacific's major urban markets include established global cities such as Tokyo, Singapore, Sydney, Seoul and Hong Kong, together with major Chinese, Indian and Southeast Asian cities. These markets differ considerably in economic structure, development, property ownership and the role played by international buyers.
Tokyo and Singapore, for example, operate as highly developed international business centres. Sydney and Melbourne combine large domestic residential markets with significant international connections. Seoul, Shanghai and Shenzhen are influenced by major technology, manufacturing and business economies, while Mumbai, Delhi and Bengaluru reflect India's enormous and rapidly developing urban economy.
Bangkok, Jakarta, Kuala Lumpur, Manila, Ho Chi Minh City and Hanoi provide further contrasts, combining large populations and expanding urban infrastructure with different levels of international property participation.
Established and Emerging City Markets
One of the most useful comparisons is between established metropolitan markets and cities undergoing rapid expansion. Established cities generally have mature infrastructure, extensive professional services, established neighbourhoods and deeper resale markets.
Emerging cities or rapidly expanding districts may have stronger development activity, changing transport networks and growing employment centres. These markets can provide opportunities associated with urbanisation, but the future market may be less predictable than an established city with a long history of property transactions.
It is also possible for an established city to contain emerging property districts. A new transport corridor, business centre or regeneration area can create a different market within an otherwise mature metropolitan economy.

|
PHILIPPINES |
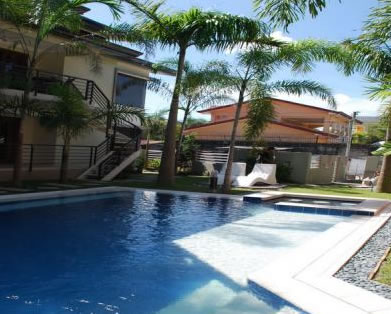
Property Type: Condo
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


City Economy and Property Demand
The economic role of a city is one of the most important factors in understanding its property market. Financial centres, technology hubs, manufacturing cities, government capitals, university centres and tourism destinations can each generate different types of property demand.
A city with several major employment sectors may have a broader residential rental base than a city dependent on one industry. Similarly, a tourism-oriented city may have significant demand for hotels, serviced residences, holiday apartments and short-term rentals but a different level of permanent residential demand.
International buyers should therefore identify what drives employment and population growth before assuming that a rising property market will continue to expand.
Population and Urbanisation
Population growth and urbanisation can be important long-term influences on city property markets. Growing populations require housing, transport, schools, healthcare, retail space and other infrastructure, while changes in household size and income can alter the type of housing required.
However, population growth alone does not guarantee property appreciation. New housing construction can increase supply at the same time, while infrastructure may expand into new areas and redirect demand away from established districts.
For overseas buyers, population trends should therefore be examined alongside employment, household formation, development supply and transport investment.
Comparing City Property Prices
Headline property prices are useful for establishing broad differences between markets, but they are not sufficient for comparing cities. A higher-priced city may have stronger infrastructure, deeper employment demand, greater liquidity and more established rental markets than a cheaper city.
Price comparisons should also consider the type of property being measured. Apartment prices in a central business district cannot be directly compared with suburban houses, resort villas or newly developed properties on the edge of a rapidly expanding city.
The Asia-Pacific property price trends section provides a wider framework for considering prices, while individual city research should examine the districts and property types relevant to the intended purchase.
Rental Markets in Major Cities
City property markets often provide multiple sources of rental demand. Tenants may include local employees, expatriates, students, corporate occupants, families and short-term visitors. The balance between these groups varies considerably from one city to another.
A large employment base can support long-term residential rentals, while tourism and international business can create additional demand for serviced apartments and short-term accommodation. These markets should not be treated as interchangeable.
International investors should compare achievable rents with purchase prices and the full cost of ownership. Management fees, maintenance, taxes, insurance, service charges and periods of vacancy can materially affect the actual return.
Central Districts and Emerging Districts
A city should rarely be treated as one property market. Central business districts, established residential neighbourhoods, suburban areas, waterfront locations, university districts and newly developing corridors can all behave differently.
Established districts may have stronger infrastructure and proven rental demand but higher property prices. Emerging districts may offer newer buildings and development opportunities, although future demand can depend more heavily on planned infrastructure and economic expansion.
For an overseas buyer, the most useful comparison often moves from city to district rather than stopping at the city boundary.
Infrastructure and Transport
Transport infrastructure is a major influence on urban property markets. Metro systems, railways, airports, highways and new transport corridors can change the accessibility of particular districts and influence where businesses and residents choose to locate.
Infrastructure should be assessed in terms of what already exists as well as what is planned. Proposed projects can affect development expectations, but international buyers should establish whether projects are funded, approved and progressing before relying on them in a property investment decision.
The effect of infrastructure can also vary by property type. A new rail station may benefit an apartment district, while a large logistics or industrial project may have a different effect on nearby commercial and residential property.
City Property Development and Supply
Development activity is another important comparison between urban markets. Some cities have limited land and strong demand, while others are expanding rapidly into new suburban or peripheral areas.
High levels of new construction can provide buyers with greater choice, but they can also create competition for existing properties. Large development pipelines should therefore be examined alongside population growth, employment and actual absorption of new housing.
International buyers considering new-build or off-plan property should also investigate the developer, project approvals, construction progress, completion arrangements and the wider supply of competing properties.
Foreign Ownership of City Property
Foreign ownership rules can significantly affect the comparison between Asia-Pacific cities. A city may have strong property demand and attractive prices but still be unsuitable for a particular overseas buyer if the relevant property cannot be acquired under the required ownership structure.
Rules can differ according to nationality, property type, land ownership, condominium legislation, location, investment status or approval requirements. Some markets distinguish between ownership of land and ownership of buildings or individual units.
International buyers should therefore establish their legal eligibility before comparing specific properties. The Asia-Pacific foreign ownership comparison provides a starting point, but the rules applicable to the individual purchase should always be confirmed before committing funds.
City Property Taxes and Transaction Costs
Purchase price is only one part of the cost of acquiring urban property. Buyers may also encounter transfer taxes, registration charges, legal costs, agent fees, financing costs and other transaction expenses.
Ownership can create additional annual costs such as property taxes, service charges, maintenance and insurance. Rental property may also generate tax obligations in the country where the property is located and potentially in the buyer's home jurisdiction.
The Asia-Pacific property transaction costs and property ownership costs guides provide broader context for comparing these expenses.
City Markets and International Buyers
International buyers do not participate equally in every city. Some urban markets have long-established international demand, while others remain overwhelmingly dependent on domestic purchasers.
International demand may also be concentrated in particular districts or property types. Overseas buyers may favour central apartments, luxury residences, branded developments, investment units or locations close to international schools and business districts, while domestic buyers dominate other segments.
This distinction matters when considering resale. A property marketed primarily to overseas buyers may have a narrower potential buyer pool than a property supported by strong domestic demand.
City Markets and Liquidity
Liquidity is an important consideration for international property investors because selling a property from overseas can be more difficult than purchasing one. Larger cities often provide a deeper pool of potential buyers and established professional services, but liquidity can still vary substantially between neighbourhoods and property types.
A centrally located apartment in a well-established market may have a different resale profile from a specialised luxury property or an investment unit in a newly developed district.
Buyers should consider who is likely to purchase the property in the future and whether the same factors attracting today's buyer are likely to remain relevant at the intended exit date.
Comparing City Investment Markets
City property investment can involve residential apartments, houses, commercial buildings, offices, retail, logistics, hotels, mixed-use developments and development land. Each sector responds to different economic conditions.
The Asia-Pacific city property investment market is particularly important because cities concentrate employment, infrastructure, business activity, education and services. However, investment conditions can change sharply between districts within the same metropolitan area.
For a private international buyer, residential property may be the most accessible sector, but that does not mean it should be evaluated without reference to the wider city economy.
How to Compare Asia-Pacific Cities
A structured comparison can use the same questions for every city. Start with the economic role of the city, population trends, employment base and infrastructure. Then examine property prices, rental demand, development supply and the type of international demand present.
The next stage is to assess foreign ownership, taxation, transaction costs, financing, currency exposure and the practical requirements of owning property from abroad. Finally, compare individual districts and properties rather than relying on the city average.
This approach makes it easier to distinguish between a city that looks attractive on a headline measure and one that actually fits the buyer's objectives.
City Property Markets by Region
East Asia includes highly developed urban markets such as Tokyo, Seoul, Shanghai, Shenzhen, Hong Kong and Taipei. These markets tend to have substantial infrastructure and complex property systems, but they differ significantly in ownership, taxation and market structure.
Southeast Asia includes Singapore, Bangkok, Jakarta, Kuala Lumpur, Manila, Ho Chi Minh City and Hanoi, together with a range of smaller and rapidly developing urban markets. Urbanisation, manufacturing, tourism and infrastructure are important influences across the region.
South Asia contains some of the world's largest metropolitan populations. Mumbai, Delhi, Bengaluru, Hyderabad, Chennai and other Indian cities have different economic and property characteristics, while Colombo, Dhaka and other regional centres provide additional market comparisons.
Australia and New Zealand provide mature urban markets including Sydney, Melbourne, Brisbane, Perth, Auckland and Wellington. These can provide useful comparisons with Asian cities because they combine established infrastructure and residential markets with different legal and ownership environments.
Researching a City Property Market from Overseas
International buyers should move progressively from region to country, then from country to city, district and individual property. Each level answers a different question. Regional research establishes the broader environment, country research identifies the legal and economic framework, and city research explains where demand and development are concentrated.
The final stage is property-level due diligence. Buyers should verify title, ownership rights, physical condition, planning status, taxes, charges, rental assumptions, management arrangements and the likely resale market. The Asia-Pacific property due diligence guide provides a wider framework for this process.
Comparing City Property Markets Across Asia-Pacific
There is no single best city property market across Asia-Pacific. Tokyo, Singapore, Sydney, Mumbai, Bangkok, Jakarta, Manila, Seoul, Shanghai and other major cities offer very different combinations of price, demand, infrastructure, regulation, rental potential and investment opportunity.
The most useful comparison is therefore based on the purpose of the purchase. A buyer seeking a permanent home may prioritise employment, schools, healthcare and transport. A rental investor may focus on tenant demand, yields, supply and management. A developer may place greater importance on land, planning, infrastructure and future demand.
For international buyers, comparing cities is ultimately about understanding what supports property demand and whether those conditions match the intended purchase. Once the right city has been identified, the research can move deeper into districts, property types and individual opportunities.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|

