
Asia-Pacific Property Market Data - Guide for International Buyers & Investors
Property market data can make international property research more useful, but only when the numbers are understood in their proper context. Asia-Pacific is not one property market and there is no single set of figures that can accurately describe the entire region.
Prices, rents, transactions, construction, investment, population, employment and development can all tell part of the story. The difficulty for an overseas buyer is deciding which information is relevant to the property being considered and whether different sources are actually measuring the same thing.
Current research illustrates the scale of these differences. Recent Asia-Pacific reports show investment activity, rental conditions and capital values moving differently between markets and property sectors. JLL's Q2 2026 residential research, for example, describes uneven capital-value momentum alongside generally steady or modest rental growth, while CBRE's Q2 figures show different patterns across office, retail and logistics markets.
The purpose of market data should therefore be to improve the quality of the research rather than provide a single number that supposedly represents an entire country or region.
Start With the Question, Not the Data
The most useful property data depends on the question being asked. A buyer looking for a permanent home needs different information from an investor assessing rental property. A developer researching land needs different data again.
Before collecting figures, establish what you are trying to understand. This could be the direction of prices, rental demand, the amount of new supply, investment activity, the depth of the buyer market or the relationship between development and infrastructure.
The Asia-Pacific property directory provides the wider geographical framework. Data can then be applied to the specific country, city, property type or transaction being researched.
This simple sequence prevents one of the most common problems with property research: collecting large amounts of information without knowing what decision the information is intended to support.

|
PHILIPPINES |
Property Type: Condo
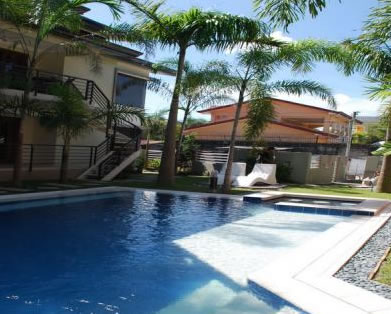
Luxurious apartments, Philippines, this luxury development comprises of 12 units, all finished and ready to move in.
Property Terms: For Sale

|
Let your friends and colleagues know about this property.
|


Asia-Pacific Data Needs a Geographical Framework
Geography is fundamental to interpreting property data. A national average can conceal substantial differences between major cities, secondary cities, coastal areas, islands and rural locations.
Even within a major metropolitan area, property markets can be divided by neighbourhood, transport access, building quality, land use and proximity to employment or services.
This is why Asia-Pacific property geography should be understood before comparing market statistics. A price series only becomes meaningful when the geographical area behind the series is known.
The same principle applies when comparing countries. A national property figure in one country may describe a very different geographical market from the corresponding figure in another.
Price Data Needs to Be Defined
Property prices can be reported in several different ways. Asking prices, achieved transaction prices, median prices, average prices and price-per-square-metre measures are not interchangeable.
An asking price reflects what a seller or developer is seeking. A transaction price reflects an actual completed sale. A median price describes the midpoint of a particular dataset, while an average can be influenced by a small number of expensive transactions.
Price-per-square-metre data can be useful when comparing similar properties, but even this measure requires care. Floor area definitions, land components, common areas, parking, balconies, building quality and property type can differ between datasets.
International buyers should therefore ask what the number represents before using it to compare properties or markets.
Rental Data Shows a Different Side of the Market
Rental data can provide useful information about underlying housing demand, but rental figures also need to be carefully defined. Long-term residential rents, short-term accommodation, furnished rentals and serviced apartments can represent very different markets.
Rental growth can also vary considerably between locations and property types. A national rental statistic may therefore be of limited use when assessing a particular apartment in a particular neighbourhood.
Recent JLL research illustrates the point: its Q2 2026 Asia-Pacific residential assessment found generally steady or modest rental growth while capital-value momentum remained uneven between markets.
For an investor, rental data should be combined with vacancy, operating costs, management expenses, taxes, financing and the purchase price rather than interpreted as an investment return on its own.
Supply Data Helps Explain Property Conditions
Property markets are affected not only by demand but by the amount and type of property available. Existing stock, new construction, vacant property and proposed developments can all influence competition.
Supply data is particularly useful when researching new-build and off-plan property. A development may appear attractive when considered on its own, but the surrounding area may contain many similar projects scheduled for completion at approximately the same time.
Conversely, a market with limited new construction may have different conditions for existing property owners and developers.
CBRE's 2026 regional research has highlighted supply pipelines as an important factor influencing investment decisions, with investors paying attention to markets where demand and supply conditions support income growth.
For the individual buyer, the important question is not simply how much property is being built, but what type of property is being added and where it is located.
Transaction Data Shows Market Activity
Transaction volumes can help indicate how active a property market is, but they need to be interpreted carefully. A rise in transactions does not automatically mean prices are rising, while a fall in transactions does not necessarily mean that a market has become less desirable.
Transactions can change because of interest rates, financing availability, investor confidence, regulation, construction activity, taxation, economic conditions or changes in the supply of properties available for sale.
Recent regional commercial property data demonstrates why transaction activity needs context. CBRE reported that Asia-Pacific commercial real estate investment volume increased year on year in the first half of 2026, while quarterly performance varied between periods.
JLL similarly reported strong first-quarter 2026 investment activity while identifying different levels of activity between individual markets and sectors.
Transaction data is therefore most useful as one part of a broader market assessment.
Investment Data Is Not the Same as Residential Data
International buyers should be particularly careful when reading property investment reports. Much of the readily available regional data concerns commercial real estate rather than individual residential purchases.
Office buildings, logistics facilities, hotels, data centres and institutional residential assets can generate enormous transaction volumes without directly describing the market for an overseas buyer looking for a house or apartment.
CBRE's 2026 Asia-Pacific investor research, for example, covers commercial real estate investment intentions across multiple sectors and reports strong interest in offices, industrial and logistics, living assets and data centres.
Such information can help explain the wider property environment, but it should not be presented as direct evidence of what an individual residential buyer will experience.
Data Centres, Offices and Other Sectors Can Still Matter
Commercial property data can nevertheless provide useful information about the broader economy of a location. Employment growth, technology investment, logistics activity, tourism and business expansion can all influence residential property demand.
For example, major investment in employment-generating sectors can affect housing demand in surrounding areas. New office districts can influence commuting patterns, while logistics and industrial development can create employment and infrastructure requirements.
Asia-Pacific's data-centre sector illustrates how new forms of development can also create changing property requirements. CBRE's 2026 research identifies rapid expansion in data-centre development across several Asia-Pacific markets, including markets outside the traditional established locations.
The residential buyer should not convert such information directly into a property prediction, but it can be relevant when researching the economic structure behind a location.
Population and Employment Data Provide Context
Property demand ultimately comes from people, businesses and other users of real estate. Population, household formation, employment, migration and economic activity can therefore provide important background to property research.
But population growth alone does not establish that every type of property will benefit. People may move toward particular employment centres while housing construction occurs elsewhere. Household size can change, and demand may favour apartments rather than houses or rental housing rather than owner-occupied property.
Employment data can similarly be more useful at the city or submarket level than at national level when assessing residential property.
International buyers should therefore connect demographic and economic information to the actual location and property type rather than treating population growth as a universal property indicator.
Transparency Affects How Data Can Be Used
The availability and quality of property data varies significantly across Asia-Pacific. Some markets have extensive transaction, land and rental information, while others provide less detailed or less accessible information.
This affects how confidently different markets can be compared. A market with limited published transaction data is not necessarily weaker; it may simply have a different level of transparency and reporting.
JLL's 2026 Global Real Estate Transparency Index highlights continuing improvements in several Asia-Pacific markets through digitisation, land registry improvements and other reforms. India, Vietnam, South Korea, Australia and Thailand were among the leading regional improvers identified in the latest research.
For an international buyer, better transparency can make due diligence and market comparison easier, but the buyer should still verify individual property information independently.
Use Multiple Sources Rather Than One Number
No single property data source is likely to answer every question. Government agencies, land registries, statistical offices, property professionals, research companies, financial institutions and market participants can all provide different forms of information.
Professional research providers such as CBRE and JLL publish regional and market-level research covering investment, rents, supply, capital values and other indicators. CBRE also provides an Asia-Pacific online data dashboard designed to bring market information together across the region.
These sources can be valuable for establishing market context, while official sources and independent professionals may be more appropriate for verifying legal, planning, ownership or transaction-specific information.
The strongest research normally compares several sources rather than allowing one headline statistic to determine the interpretation.
Check the Date Before Using Property Data
Property data becomes less useful when its date is unclear. A price figure from several years ago may still be useful for understanding a historical trend, but it should not be presented as a current market condition.
This is particularly important in markets experiencing rapid changes in financing, construction, regulation, tourism or investment activity.
International buyers should record the date of each important dataset and distinguish historical evidence from current conditions. Where forecasts are used, they should also be identified as forecasts rather than treated as established outcomes.
This approach keeps evergreen property research durable while allowing separate market updates to carry changing information.
Do Not Mix Different Measurements
Comparing figures from different sources can create misleading conclusions if the underlying definitions are different. One source may measure prime residential property while another measures the broader housing market. One may report completed transactions while another uses advertised prices.
The same problem occurs with rental yields. Gross yields, net yields, advertised rents and achieved rents can produce very different results.
Before comparing two figures, establish the geography, property type, measurement method, time period and source methodology.
This may seem excessive when looking at a simple property purchase, but international buyers are often comparing markets across different countries. Consistency becomes increasingly important as the geographical comparison becomes wider.
Market Data Should Lead to Property Research
Data is most useful when it helps the buyer ask better questions. If rental data indicates strong demand, the next question should be which properties are attracting that demand and whether the rental income remains viable after costs.
If transaction activity is increasing, the buyer should ask which sectors and locations are responsible. If development is expanding, the next question is whether the new supply complements or competes with the property being considered.
If prices appear low compared with another market, the buyer should investigate why. Differences in ownership, infrastructure, liquidity, financing, demand, taxation, construction quality or legal structure may explain the apparent discount.
This connects market data directly with the wider Asia-Pacific property price research rather than treating price as an isolated statistic.
Data Has to Be Matched to the Property Type
Different property types generate different forms of market data. Apartments may be assessed through transaction prices, rents, vacancy, new supply and absorption. Houses may require more attention to land value, neighbourhood characteristics and comparable sales.
Development land requires information about planning, zoning, infrastructure, construction and comparable land transactions. Resort property may require tourism and accommodation information in addition to residential data.
The buyer should therefore choose the data according to the property rather than choosing the property according to whichever data happens to be easiest to find.
IPD's wider property resources allow research to move from regional markets into individual property categories and locations.
International Buyers Need to Add Currency to the Data
Property data is usually reported in local currency, while an international buyer may think about the purchase in another currency. Exchange-rate movements can therefore alter the buyer's effective cost and the value of future income.
This is particularly important when comparing properties across several countries. A converted price may appear to change even when the local property price has remained relatively stable.
Currency should therefore be treated as a separate component of international property research. The buyer should understand both the local property market and the currency relationship rather than allowing one converted figure to represent the entire investment case.
Use Data to Compare Markets, Not to Rank Them
Property data can help an overseas buyer establish how markets differ, but there is rarely a meaningful single ranking of Asia-Pacific property markets. The relevant market depends on the buyer's purpose, property type, time horizon and tolerance for different forms of risk.
A market with strong rental growth may not suit a buyer seeking a permanent residence. A highly active commercial market may tell little about the house market. A lower-priced location may involve different liquidity or infrastructure conditions.
A structured comparison can instead examine prices, rents, supply, demand, development, ownership, financing, liquidity and risk using the same questions in each location.
The Asia-Pacific property markets guide provides the regional context for this approach.
From Regional Data to an Individual Property
The value of Asia-Pacific property market data ultimately lies in how it improves the research behind an individual decision. Regional figures establish the broad environment. Country data narrows the picture. City and neighbourhood information makes it more relevant. Property-level evidence then determines whether the particular asset fits the buyer's requirements.
Each layer answers a different question. Regional data explains the wider market. Local data explains the location. Property data explains the asset.
Current research demonstrates why this layered approach is necessary. Asia-Pacific investment and residential conditions are showing different patterns between sectors and markets, while improving data transparency is making some comparisons easier than before.
For international buyers and investors, the objective is therefore not to collect the largest amount of property data. It is to use relevant, dated and properly defined information to understand the market in which the property actually exists.
Asia-Pacific property market data is most valuable when it becomes part of a wider research process: region, country, location, property type, market conditions and finally the individual property and transaction.
Asia Pacific Property Market Snapshot
| Population | More than 4 billion people live across the broader Asia Pacific region, encompassing East Asia, Southeast Asia, South Asia, Australia, New Zealand and the Pacific island states. The precise geographical definition of Asia Pacific varies between organisations and sources |
|---|---|
| Area | Asia Pacific covers an extensive area stretching from South Asia and the Indian Ocean through East and Southeast Asia to Australia, New Zealand and the Pacific islands. Because regional definitions differ, the total area varies considerably between sources |
| Major Airports | Major international gateways include Singapore Changi, Hong Kong International, Tokyo Haneda and Narita, Seoul Incheon, Bangkok Suvarnabhumi, Kuala Lumpur International, Sydney, Melbourne, Auckland, Beijing Capital and Daxing, Shanghai Pudong, Delhi, Mumbai, Jakarta, Manila, Brisbane, Perth and major airports serving other regional centres |
| Currencies | Asia Pacific uses a wide range of national currencies. Major currencies include the Chinese yuan, Japanese yen, South Korean won, Singapore dollar, Australian dollar, New Zealand dollar, Indian rupee, Indonesian rupiah, Thai baht, Malaysian ringgit, Philippine peso and Vietnamese dong. Currency conditions, exchange-rate arrangements and restrictions on moving funds vary substantially between countries |
| Foreign Ownership | Foreign property ownership varies substantially across Asia Pacific and can differ according to nationality, property type, location, residency status and the structure of the purchase. Some markets provide relatively open access to residential or investment property, while others restrict foreign ownership of land or impose limits on apartments, houses, development land or agricultural property. International buyers should obtain independent local legal advice before purchasing |
| Major Property Markets | Major international property markets include Australia, Japan, Singapore, Hong Kong, China, South Korea, India, Thailand, Malaysia, Indonesia, Vietnam, the Philippines and New Zealand. Sydney, Melbourne, Brisbane, Tokyo, Osaka, Singapore, Hong Kong, Seoul, Bangkok, Kuala Lumpur, Jakarta, Bali, Manila, Ho Chi Minh City, Hanoi, Mumbai and Delhi are among the region's significant urban and investment markets |
| Main Overseas Buyers | International demand comes from a diverse mix of investors, expatriates, entrepreneurs, high-net-worth individuals, retirees, second-home buyers, lifestyle purchasers and people seeking residential property connected with employment, education or relocation. Important sources of overseas demand include neighbouring Asian countries, the Middle East, Europe, North America and Australia and New Zealand, together with substantial intra-regional investment |
| Tourism | Tourism is an important driver of property demand across much of Asia Pacific. Major tourism markets include Thailand, Indonesia, Japan, Australia, New Zealand, Vietnam, Malaysia, the Philippines and the Pacific islands. Beach resorts, tropical islands, cultural destinations, ski areas, major cities, cruise facilities and luxury hospitality developments support demand for hotels, serviced residences, vacation homes, branded residences and short-term rental property |
| Main Luxury Markets | Luxury property markets include Singapore, Hong Kong, Tokyo, Osaka, Sydney, Melbourne, Auckland, Seoul, Bangkok, Phuket, Bali, Jakarta, Kuala Lumpur, Mumbai and selected resort and island destinations across Thailand, Indonesia, Australia, New Zealand and the Pacific. Prime districts, waterfront locations, resort communities, branded residences and high-end new developments form important segments of the regional luxury market |
| Residency Routes | A number of Asia Pacific countries offer residence or migration routes connected with investment, employment, entrepreneurship, retirement, family circumstances or other qualifying criteria. Property ownership may support relocation or investment objectives in some markets, but buying property does not automatically provide residency. Eligibility, investment thresholds and programme conditions vary by country and can change over time |
| Property Taxes | Property taxes, stamp duty, transfer taxes, registration charges, land taxes, municipal charges, rental taxation, capital gains treatment and taxes affecting foreign buyers vary considerably across Asia Pacific. Some markets apply additional transaction taxes or surcharges to foreign purchasers, while others have different rules depending on property type and residency status. Buyers should assess acquisition, ownership, rental and disposal costs before purchasing |
| Investment Opportunities | Asia Pacific offers opportunities across apartments, houses, villas, luxury residences, beachfront property, resort developments, commercial real estate, hospitality, development land, new-build and off-plan projects. Major investment themes include established city markets in Australia, Japan, Singapore and South Korea; rapidly developing markets in Southeast Asia; major Indian cities; tourism destinations such as Thailand, Bali and the Pacific islands; and residential and lifestyle markets across Australia and New Zealand. Pricing, rental demand, infrastructure, taxation, regulation and foreign-buyer access vary considerably between countries and individual locations |
Major Asia Pacific Countries That Appeal to International Investors and Buyers:
Southeast Asia
 Cambodia Properties Growing urban and coastal markets attracting international buyers and investors.  Indonesia Properties Bali, Jakarta and other destinations offer apartments, villas and tourism-linked property opportunities.  Malaysia Properties Kuala Lumpur, Penang and other established markets attract international buyers and investors.  Philippines Properties Manila, Cebu and resort destinations offer apartments, condos and lifestyle property.  Singapore Properties A major international real estate centre with prime residential and investment markets.  Thailand Properties Bangkok, Phuket, Pattaya and other destinations attract substantial international property interest.  Vietnam Properties Major cities and coastal destinations offer growing opportunities for overseas buyers. East Asia
 China Properties Major metropolitan and coastal property markets with significant international connections.  Japan Properties Tokyo, Osaka, Kyoto and resort markets attract international residential investors.  South Korea Properties Seoul, Busan and other major markets offer urban and lifestyle property opportunities.  Taiwan Properties Taipei and other established markets offer apartments and residential investment opportunities. South Asia
 India Properties Mumbai, Delhi, Goa and other major markets attract overseas buyers and investors.  Maldives Properties Luxury resorts, islands and beachfront property create a distinctive international market.  Sri Lanka Properties Coastal, resort and city properties attract overseas buyers seeking lifestyle opportunities. Oceania & Pacific
 Australia Properties Sydney, Melbourne, Brisbane and major coastal markets have a long-established international profile.  Fiji Properties Beachfront and resort property provide a focused international lifestyle market.  New Zealand Properties Auckland, Wellington and lifestyle markets attract overseas buyers within regulated ownership rules. Territories
 Hong Kong Properties International property market and financial centre with a highly developed urban real estate sector. Territory.  Macau Properties Highly developed urban and resort property market with strong international connections. Territory. |
|
